

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Virtual Rehabilitation Market to Reach USD 2,429M by 2032 at 19.5% CAGR

Virtual Rehabilitation and Telerehabilitation Systems: Strategic Intelligence for 2026 Decision-Making
Executive summary
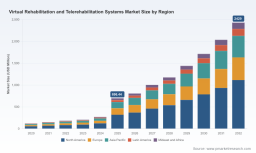
The virtual rehabilitation and telerehabilitation market is at an inflection point. After a sustained expansion through the early 2020s, the sector’s addressable market reached roughly USD 696.4 million in our base year (2025) and is projected to expand at a compound annual growth rate (CAGR) of 19.5% across the 2026–2032 forecast window, reaching approximately USD 2.43 billion by 2032. For leaders making resource allocation, product roadmap, partnership, and M&A decisions in 2026, the opportunity is clear—but nuanced: growth is robust, the competitive field is moderately fragmented, and regulatory and reimbursement shifts this year materially change the rules of market entry and scale.
Virtual Rehabilitation and Telerehabilitation Systems Market
Why 2026 is a strategic hinge year
-
Regulatory momentum is real and actionable. Early 2026 saw major programmatic shifts—most notably the FDA’s TEMPO pilot and changes in CMS policy—that lower regulatory friction for certain digital therapeutics and telerehabilitation devices while emphasizing post-market safety and real-world evidence. Firms that align regulatory strategy and evidence generation with these initiatives will shorten time-to-adoption in payer and health-system procurement cycles.
Virtual Rehabilitation and Telerehabilitation Systems Market -
Reimbursement pathways are expanding. In 2026, Medicare added new coding pathways for remote therapeutic monitoring and telerehabilitation services. This alters unit economics for care delivery models and converts pilots into reimbursable services for providers who can demonstrate validated outcomes.
Virtual Rehabilitation and Telerehabilitation Systems Market -
Technology costs and supply dynamics are shifting. Improvements in component supply—illustrated by the emergence of lower-cost, medical‑grade thermoplastic polyurethane production—reduce hardware bill-of-materials and enable slimmer device pricing or higher margin reinvestment in software and clinical support.
Market trajectory and what the numbers tell you
The market’s trajectory—from a modest single-digit base in 2020 to the 2025 inflection and onward to a multi‑billion dollar forecast—signals both adoption and commercialization maturity. A near‑20% CAGR implies sustained demand across clinical settings and home care. For corporate strategists, this combination of scale and velocity favors first-mover advantages in clinical validation and payer contracting, but also rewards disciplined capital allocation: winning requires both clinical credibility and scalable delivery models.
Competitive landscape: strategic positioning of leading actors
The competitive map is populated by specialists with distinct value stacks: platforms combining clinical workflows and clinician oversight; device-centric companies offering FDA-cleared wearables; immersive VR and motion-capture innovators; and service-oriented providers addressing specific populations such as seniors or post-surgical MSK patients. Top-tier firms hold meaningful share but do not dominate the entire value chain—creating whitespace for adjacent entrants and consolidation plays.
-
Platform clinicians + AI (example archetype): Companies delivering AI-guided virtual therapy paired with clinician oversight have made significant inroads with payers and employers. Their differentiator is a hybrid delivery model that balances automation (scale) with licensed clinician touchpoints (clinical acceptance).
-
Device + software incumbents: Firms offering FDA-cleared wearables and integrated software suites have the advantage in clinical validity and reimbursement conversations, especially in musculoskeletal (MSK) pathways where objective motion data supports billing and outcomes metrics.
-
Immersive and motion-capture specialists: Providers of VR, gait platforms, and interactive environments compete on therapeutic efficacy, engagement, and integration into existing therapy workflows. Their value proposition is strong in neurorehabilitation and balance/gait programs.
-
Specialized care-focused vendors: Solutions targeted to geriatric, post-stroke, or home‑care settings differentiate on usability, caregiver integration, and fall‑prevention outcomes—features that matter heavily for long‑term care procurement.
Notable commercial players exemplify these archetypes: developers of gamified neurorehabilitation environments and motion-capture systems, suppliers of instrumented gait and balance platforms, companies pairing wearable sensors with AI-guided therapy, and vendors focused on home-based patient engagement and senior care. Recent product launches and platform adoptions in 2025–2026 demonstrate both market validation and deepening clinical integration, while industry associations updated telerehabilitation guidelines that raise the bar for documented standards of care.
Regulation, reimbursement and the commercialization playbook for 2026
-
Regulatory engagement as strategic moat: The FDA’s TEMPO pilot and related initiatives create a pathway to market for digital rehabilitation devices that meet safety and evidence expectations while expediting access. Firms should invest in pilot participation, pre-submission strategies, and structured real-world evidence collection to accelerate routes to coverage.
-
Payer strategy is now executional: New Medicare coding decisions and additions to telehealth lists convert product efficacy into revenue potential—but only for vendors who can translate clinical outcomes into billing workflows. Investment in coding specialists, claims operations, and payer pilots will yield outsized commercial returns in 2026.
-
Evidence generation matters: Robust clinical outcomes, health economic models, and longitudinal adherence data are the currency of procurement. RCTs are valuable, but pragmatic, real‑world studies demonstrating cost avoidance and reduced utilization will accelerate uptake among systems and payers.
Technology and supply-side considerations
Hardware commoditization trends—lower-cost medical-grade components and improved sterilization-compatible materials—shrink margins in device manufacturing and shift competition toward software differentiation, service models, and data analytics. At the same time, integration capabilities (EHR, telehealth platforms, remote monitoring protocols) remain a gating factor for enterprise adoption. Companies that bundle clinical workflow integration with easy-to-deploy hardware and clinician training will capture the majority of large institutional contracts.
Strategic recommendations for executives in 2026
-
Prioritize payer‑aligned pilots: Structure pilot contracts to measure outcomes that map directly to reimbursement codes and cost-savings metrics. Short, well-defined payer pilots beat long exploratory implementations.
-
Invest in clinical operations and evidence: Allocate budget for registries, pragmatic trials, and health economic models that speak the language of CFOs and utilization managers.
-
Choose a go-to-market axis: Decide early whether to compete as a device-first company, a clinician‑centric platform, or an integrated service provider. Each axis requires different sales motions, margin structures, and capital intensity.
-
Build regulatory roadmap into product development: Use FDA pilot programs and emerging CMS rules to inform product specs, data collection frameworks, and labeling claims that unlock coverage pathways.
-
Look for targeted M&A and partnerships: Consolidation will center on software platforms that have embedded clinical networks and on device firms that can provide validated objective measures. Strategic partnerships with rehabilitation networks, large providers, and equipment OEMs can accelerate scale.
What this report contains — and why it matters to you
This PW Consulting market study is designed as an operational guide for 2026 decision-making. Contents include an audited market-sizing model and forecast (2026–2032), scenario analysis, vendor landscaping and capability scorecards, payer and provider adoption frameworks, regulatory and reimbursement pathway maps, clinical evidence templates, practical go‑to‑market playbooks, and an M&A opportunity register. The report translates macro forecasts into executable recommendations: how to prioritize R&D, which commercial pilots to run, which regulatory engagements to pursue, and where to place disciplined bets in partnerships and M&A.
Competitive highlights and recent industry moves
Across 2025–2026 the ecosystem saw product launches and platform adoptions that validate demand across clinical and home settings. New virtual-rehab stations for clinics, expanded telerehabilitation platforms with enhanced accessibility, and strategic partnerships to build rehab centers in emerging markets underscores a maturing commercialization environment. Industry association guideline updates in 2026 also raise the bar for documented care processes, which benefits vendors with robust clinical governance frameworks.
Final guidance for 2026: act with speed, but structure risk
Market momentum and regulatory tailwinds make 2026 a year for decisive—but disciplined—action. Firms that convert clinical efficacy into payer‑recognized value, who tightly align product development with regulatory pilots, and who build integration-first commercial models will secure disproportionate share as the industry scales. The market is growing quickly, but complexity around evidence, reimbursement, and deployment means that strategic clarity and operational rigor—not just capital—determine winners.
Next steps
For leaders evaluating entry, expansion, or consolidation strategies, PW Consulting’s full report provides the calibrated analysis, model access, and implementation playbooks necessary to translate market forecasts into board-level decisions. The executive summary above outlines the high-level thesis; for the detailed segmentation, adoption curves, vendor scorecards, and tactical checklists that operational teams need, consult the full market study.
For detailed analysis of this topic, please visit the official page: Virtual Rehabilitation and Telerehabilitation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com