

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
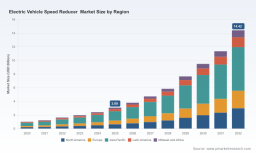
PW Consulting: EV Speed Reducer Market to Reach USD 14.42 Billion by 2032 at 18.5% CAGR

Electric Vehicle Speed Reducer Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present an executive preview of our latest Electric Vehicle (EV) Speed Reducer Market study. This briefing is designed as a strategic trailer: it demonstrates the methodological rigor, the decision-grade insights, and the scenarios that will shape supplier, OEM, and investor choices in 2026 — while intentionally reserving the granular segmentation intelligence for the full report.
Electric Vehicle Speed Reducer Market
Why this study matters for 2026
The EV speed reducer — the gearbox or reducer that adapts high-speed, high-efficiency electric motors to wheel speed and torque requirements — is a critical enabler of vehicle range, packaging, NVH (noise, vibration, harshness), and cost. Between 2020 and 2025 the market expanded rapidly, and by our base year (2025) global revenue is sized in the low single-digit billions (USD, revenue unit: Billion). With a robust compound annual growth rate (CAGR) of 18.5% projected across the forecast horizon (2026–2032), the market trajectory is set to multiply several-fold by 2032.
Electric Vehicle Speed Reducer Market
For 2026 decision cycles — product roadmaps, sourcing contracts, plant investments, and strategic partnerships — the implications are immediate: incumbents must balance scale with modularity, new entrants must prioritize torque-density innovation and supply security, and investors should prepare for consolidation even as pockets of premium engineering command elevated margins.
Electric Vehicle Speed Reducer Market
Macroeconomic and market context
-
Growth momentum: After impressive historical growth through 2025, the market enters 2026 with sustained demand driven by vehicle electrification across passenger and light-commercial segments. Our top-line projections show a multi-year expansion that results in a market several times larger by 2032 compared with 2025 — reflecting accelerated EV adoption, platform electrification, and new architecture rollouts.
-
Concentration dynamics: The supply base exhibits moderate consolidation. The three largest suppliers account for a majority share of industry revenue, while the top five capture a notably larger portion — a structure that favors scale players but leaves tactical openings for specialists focused on weight, cost, or performance niches.
-
Technology infusion: Advances in gear topology (helical, planetary stacks, and compact multi-stage systems), material substitution (aluminum and magnesium alloys), and integration of reduction units with inverters and e-axles are altering supplier value propositions. Lightweight composites and alloys can meaningfully reduce mass per unit and thereby improve system-level efficiency.
What the full PW Consulting report delivers (practical contents)
Our market study was constructed to support decisions across strategic, commercial, and operational horizons. Key deliverables include:
-
Robust top-down and bottom-up market sizing with historical (2020–2025) validation and a clear 2026–2032 scenario framework tied to vehicle electrification pathways and regulatory levers.
-
Technology landscape and roadmap: in-depth assessment of reducer architectures (single-stage, multi-stage, planetary stacks, helical gears), materials strategies, integration approaches (integrated e-axles, modular eDrive units), and the trade-offs between torque density, NVH, packaging, and cost.
-
Go-to-market playbooks for OEMs and Tier-1s: sourcing frameworks, localization strategies, cost takeout levers, and supplier scorecards that align performance KPIs with total cost of ownership.
-
Supply chain stress-testing: vulnerability analysis for key raw materials, component lead times, and potential pinch points — and tactical mitigation plans including dual-sourcing, nearshoring, and vertical integration scenarios.
-
Commercial intelligence and M&A mapping: candidate target lists, valuation heuristics, and integration risk matrices for acquirers looking to accelerate capability or access manufacturing scale.
-
Regulatory and standards impact matrix: how emission standards and vehicle CO2 rules, fast-charging infrastructure development, and safety/functional regulations reshape reducer design and procurement cycles.
Note: the above describes the functional content of the report and the type of analyses included. The full report contains cell-level segmentation and price curves that are intentionally omitted here to preserve the commercial value of the proprietary intelligence.
Competitive landscape — strategic takeaways
The EV speed reducer market is characterized by players with differentiated approaches: full-system integrators, component specialists, and modular platform vendors. Below are concise strategic profiles and implications for each major player covered in the report.
-
BorgWarner (Auburn Hills, Michigan) — Known for single-speed transmissions and integrated drive modules (e.g., eGearDrive®), BorgWarner combines established thermal and power-electronics strengths with reducer expertise. Their public showcases in early 2026 underscore a push to present bundled thermal, electronics, and battery support solutions — a strategic move to sell higher ASP (average selling price) value through systems integration rather than standalone components.
-
ZF Friedrichshafen AG (Friedrichshafen, Germany) — ZF’s eDrive platform and stacked planetary gear architectures emphasize packaging efficiency and scalable performance. Their product platform announcements reflect a classic OEM-facing strategy: build modular building blocks that serve multiple vehicle architectures, thereby capturing share through platform proliferation.
-
Magna International (Aurora, Ontario) — As a systems supplier, Magna advances scalable modules with both 1-speed and 2-speed options, targeting OEMs seeking flexible migration paths from ICE to hybrid and full-EV. Their eco-friendly, scalable product launches signal a strategy to align to customers’ decarbonization roadmaps while maintaining manufacturing breadth.
-
Nidec Corporation (Kyoto, Japan) — Vertical integration is core to Nidec’s proposition: traction motors, inverters, and reducers packaged as integrated e-axles. This reduces system-level integration risk for OEMs and can lower interface costs; it also raises the bar for component suppliers who cannot match the vertical stack.
-
Punch Powertrain (Gosselies, Belgium) — With modular E-Propulsion kits and bespoke offset/standard reducers, Punch focuses on targeted power ranges and modularity, attractive to light-commercial vehicle OEMs and new EV marques that require quick time-to-market without large upfront investments in powertrain development.
-
Aisin Seiki (Nagoya, Japan) — Aisin’s strength lies in proven transmission experience paired with EV-specific reducer designs. Their established supplier relationships with major Japanese OEMs give them privileged access to volume programs where reliability and integration heritage matter most.
-
GKN Automotive (Redditch, UK) — GKN continues to position itself as a leader in e-axles and integrated speed reducers, leveraging global manufacturing footprints and electrification expertise to serve multi-regional OEM programs.
-
Bosch (Gerlingen, Germany) — Bosch pursues a modular reducer platform strategy with a broad component portfolio. As a systems player with deep calibration and controls capability, Bosch competes on integration and scale for high-volume OEMs.
Collectively, these firms illustrate two dominant strategic vectors: (1) platform scale and systems integration, and (2) focused engineering differentiation on torque density, mass reduction, and NVH. The market reward model favors companies that can combine cost competitiveness with demonstrable system-level efficiency gains.
Regulatory and materials dynamics shaping 2026 choices
-
Regulation: Tightening CO2 and emission standards in major markets are an immediate demand-side driver. Policies that tie fleet compliance to drivetrain efficiency increase OEM willingness to pay for higher-efficiency reducer designs — especially when the incremental cost is offset by range or battery-size reductions.
-
Materials and weight: Sector analyses and government research indicate that lightweight alloys and composites yield meaningful system-level efficiency improvements and a non-trivial reduction in per-unit mass versus steel designs. For 2026, material selection and supplier capability in alloy casting, machining, and joining will be critical procurement criteria.
-
Infrastructure and charging: Expansion of fast-charging networks places new demands on torque density and thermal management to support higher discharge rates and repeated fast-charging duty cycles. Reducer suppliers that can demonstrate robust thermal performance and torque-density improvements will be prioritized in applications where rapid charging is a selling point.
Actionable strategic recommendations for 2026
-
For OEMs: Prioritize supplier evaluations that quantify system-level benefits (range, mass, NVH) rather than component price alone. Insist on integrated testing data that reflects fast-charging duty-cycles and thermal endurance.
-
For Tier-1 suppliers: Invest in modular platform architectures and materials capability (aluminum/magnesium casting, composite housings). Consider selective vertical integration for critical interfaces (motor-reducer-inverter) to capture more value.
-
For investors and M&A teams: Target bolt-on engineering specialists that can close torque-density or weight gaps for platform providers, and production assets that enable regional localization near high-growth EV programs.
-
For policy and infrastructure planners: Coordinate charging rollout with industry roadmaps to ensure component suppliers can validate performance under realistic duty cycles, thereby aligning vehicle-level targets with real-world charging behavior.
Next steps and how to access the full intelligence
This preview highlights the strategic contours and decision levers that matter most in 2026. The full PW Consulting Electric Vehicle Speed Reducer Market report contains the granular segmentation breakdowns, region- and application-level forecasts, price curves, supplier scorecards, and proprietary datasets that underpin the recommendations summarized here. Those specific cells and scenario matrices are reserved for subscribers and clients because they represent the commercially sensitive, transaction-grade intelligence that drives negotiations and investment decisions.
If your 2026 strategy depends on precise margin modeling, supplier selection, or identifying the most attractive M&A targets in this high-growth market, the full report and data appendices will provide the necessary depth and forensic accuracy.
Contact PW Consulting to obtain the complete market study, bespoke briefings, or a tailored scenario workshop aligned to your strategic priorities for 2026.
For detailed analysis of this topic, please visit the official page: Electric Vehicle Speed Reducer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com