

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: KVM over IP Market to Hit USD 386.68M by 2032, 7.8% CAGR

KVM over IP Market: Strategic Imperatives for 2026
As enterprises accelerate remote operations, high-performance visualization and secure multi-site system management, KVM over IP has shifted from a niche infrastructure component to a strategic control plane. This briefing introduces PW Consulting’s latest market research on the KVM over IP market — a pragmatic, decision-ready toolkit for CXOs, heads of infrastructure, product strategists and investors preparing plans for 2026. It demonstrates the kinds of analysis and recommendations you will find in the full study while intentionally withholding the detailed sub-segment tables and proprietary scorecards that drive vendor- and region-level decisions.
KVM over IP Market
Macroeconomic snapshot and why it matters
-
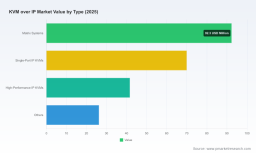
The global KVM over IP market has moved from the early recovery phase of the last half-decade to a steady commercial growth trajectory. Our base-year sizing for 2025 places the market at approximately USD 230 Million, and we model a compound annual growth rate (CAGR) of 7.8% into the forecast window. At this growth rate, the market is expected to approach the high hundreds of millions by the end of the forecast period, a trajectory that signals widening adoption beyond traditional broadcast and data center buyers.
KVM over IP Market -
Two structural shifts underpin this growth: (1) the migration of AV and control-plane traffic onto IP fabrics that reduce specialized cabling and support 4K+/low-latency workflows over commodity 1GbE links, and (2) an increasing regulatory and security premium on validated separation and NIAP-compliant solutions for government, defense and critical infrastructure. Those twin dynamics are reshaping procurement criteria and total cost of ownership (TCO) calculations for buyers.
KVM over IP Market
What the full report delivers (practical, operational content)
-
Actionable market sizing and forecast model — an interactive, transparent financial model built on our 2020–2025 historical base and extended through 2032. The workbook lets you run alternate scenarios for adoption, pricing pressure and component supply constraints.
-
Demand-driver mapping — ranked use cases (data centers, telecom, broadcast, healthcare, control rooms) with decision triggers and procurement lead times to inform fleet replacement and modernization cycles.
-
Vendor scorecards and strategic positioning — qualitative and quantitative assessments across product capabilities, security certifications, service footprint, integration maturity and go-to-market motion. (Note: individual vendor scores and segment-level revenue splits are reserved for the full report.)
-
TCO and deployment playbooks — turnkey checklists and a step-by-step migration path for replacing legacy extenders, implementing matrix switching over IP, and validating low-latency codecs in live operations.
-
Procurement tools — RFP templates, evaluation rubrics, and negotiation levers for licensing, maintenance and software-defined feature upgrades.
-
Risk scenarios and mitigation — supply-chain sensitivity analysis, security-certification timelines and interoperability testing regimens for multi-vendor architectures.
-
M&A and partner-opportunity map — strategic imperatives for vendors and investors on consolidation targets, white-label alliances and channel expansion strategies.
Competitive landscape — how established players and specialists are positioning
The market shows a moderate concentration profile: a handful of global vendors account for meaningful shares, while a long tail of specialized sellers serves niche verticals. This structure produces two practical consequences: buyers can choose well-established single-vendor solutions for operational simplicity, or assemble best-of-breed stacks when specialization (e.g., ultra-low-latency broadcast or NIAP-classified separation) is the priority.
-
IHSE GmbH (Oberteuringen, Germany) — IHSE is doubling down on high-resolution, low-latency platforms tailored to broadcast and critical infrastructure. Recent product introductions (Draco XStreme series and the vario XS DisplayPort 1.2 Extender family) and recognition for codec integration reinforce IHSE’s premium, performance-first positioning. For buyers designing mission-critical control rooms or media facilities, IHSE represents a performance anchor — but at a higher engineering and procurement threshold.
-
ATEN International (Taipei, Taiwan) — ATEN’s enterprise-focused KVM-over-IP switches and multi-view receiver products (including the KE8980MR) target large-scale IT operations and hybrid control environments. Their recent product and design awards underscore a focus on user experience and multi-task workflows that suit AI-accelerated operations centers.
-
StarTech.com (Groveport, Ohio, USA) — StarTech’s emphasis on secure KVM switches and recent NIAP compliance positions it squarely for government, defense and regulated industries. For procurement teams with classified separation requirements, StarTech simplifies certification risk and shortens validation cycles.
-
Raritan (Legrand, Wilmington, Massachusetts, USA) — Raritan’s Dominion series remains a go-to for data center operations seeking enterprise-grade management, integration with DCIM stacks and familiar enterprise service contracts. Their offering is optimized for scale and operations-friendly tooling.
-
Apantac (Taiwan) — Apantac’s openGear and MT HOOD extenders showcase how vendors are delivering 4K over standard 1GbE links for broadcast workflows. Their approach illustrates the market’s engineering trend: squeezing professional video performance into commodity network footprints.
-
Black Box Corporation (Pittsburgh, Pennsylvania, USA) — Black Box’s Emerald matrix systems demonstrate how IP-based KVM is merging with broader AV-over-IP ecosystems to deliver integrated video, USB and audio over common fabrics — appealing to organizations consolidating control-plane and AV stacks.
Recent product launches across these vendors throughout 2025–2026, and third-party validations — from Emmy recognition for codec work to JITC validation of certain KVM-over-IP solutions and NIAP certifications — are shifting procurement criteria from feature checklists to certified-compatibility and long-term support assurances. These endorsements matter because they shorten adoption cycles in risk-averse verticals and elevate the value of certified vendors.
Strategic recommendations for buyers and vendors entering 2026
-
Buyers: adopt a use-case-first architecture. Start with the strictest requirement (security, latency, resolution) and design scale-out patterns from that point. For mixed-use estates, favor software-defined switching layers that decouple management from physical topology.
-
Buyers: require certification roadmaps. Insist on vendor timelines for NIAP/JITC or equivalent validations where classified separation or regulated compliance is needed. Treat certifications as deliverables in the procurement contract.
-
Buyers: model TCO with network substitution assumptions. Include the savings from moving away from specialized fiber and proprietary cabling when calculating return on investment; model codec licensing and support as recurring costs.
-
Vendors: productize interoperability and managed services. Opportunities exist for vendors that combine certified hardware with subscription management, zero-touch provisioning and lifecycle services to convert CAPEX buyers into annuity relationships.
-
Vendors & investors: prioritize segment-led partnerships. Align with cloud-native orchestration vendors, AV-over-IP ecosystem suppliers and security certifiers to lower adoption friction for enterprise accounts.
-
All stakeholders: plan for phased pilots. Validate multi-vendor interoperability in a controlled pilot (4–12 week window) before enterprise rollout, using measurable KPIs for latency, availability, and security posture.
How to use this research in your 2026 planning
-
Executive teams can use the high-level market sizing and CAGR to validate strategic investment levels and to benchmark internal growth targets.
-
Procurement and architecture teams will find the TCO models, RFP templates and deployment playbooks practical for sourcing and onboarding new KVM over IP solutions.
-
Product and business unit leaders should use the vendor scorecards, certification timelines and competitive mapping to prioritize partnerships, product feature sets and go-to-market channels.
Closing: the value of the full intelligence package
This briefing highlights the strategic contours that will shape KVM over IP decisions in 2026: steady market growth at a ~7.8% CAGR, an expanding buyer base beyond traditional segments, and a competitive environment where certification and interoperability increasingly determine winners. The full PW Consulting report contains the granular inputs — downloadable forecasting models, vendor scoring matrices, and confidential sub-segment tables — that procurement teams and investors need to execute with confidence. If you are planning capital allocation, vendor consolidation, or a new product roadmap in this space, the full dataset and playbooks will materially shorten your decision cycle and reduce implementation risk.
To access the complete study, model files and RFP toolkits, consult PW Consulting’s report page or contact your PW Consulting account lead for an executive briefing and licensing options.
For detailed analysis of this topic, please visit the official page: KVM over IP Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com