

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Cored Wire Market to Hit USD 474M by 2032, Growing at 6.9% CAGR - PW Consulting

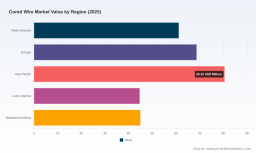
PW Consulting: Cored Wire Market — Strategic Outlook to Guide 2026 Decisions
As companies prepare budgets, capital plans and supply-chain strategies for 2026, the cored wire market deserves renewed executive attention. Our Cored Wire Market study (base year 2025, revenue in Million USD) synthesizes five years of historical dynamics (2020–2025) and a forward-looking forecast (2026–2032) to translate macro trajectory, competitive shifts and regulatory noise into concrete options for market leaders and fast followers. The market expanded meaningfully from the early-2020s and reached roughly USD 300 million in 2025; at a projected compound annual growth rate (CAGR) of 6.9% through 2032, the sector is expected to approach the mid‑400s by the end of the forecast window. These headline figures frame the strategic choices that follow.
Cored Wire Market
Why this research matters for 2026 corporate strategy
-
Timing and scale: With consistent growth built into the base-case outlook, 2026 becomes a tipping point for companies deciding between organic capacity expansion and market-consolidating moves. The market is neither fully commoditized nor tightly concentrated: the top three suppliers account for roughly a third of revenues while the top five remain below half—creating both opportunity and competitive pressure.
Cored Wire Market -
Supply-risk asymmetry: Inputs—chiefly ferroalloys such as calcium silicon and ferro-calcium—drive both cost and availability risk. Shifts in feedstock markets translate quickly into margin volatility for cored wire producers and downstream steelmakers.
Cored Wire Market -
Regulatory and demand inflection: Trade measures (including evolving tariffs and CBAM-style mechanisms) and a recovering North American steel market are changing trade flows and localization economics. Meanwhile, advanced applications (e.g., aerospace-grade alloys) are opening premium niches that value quality over price.
Key market dynamics to monitor in 2026
-
Raw-material cycles: Ferroalloy availability and silicon metal pricing remain the primary short-to-medium-term cost drivers. Public statements by leading producers indicate relative stability in metallurgical silicon recently, but concentrated supply and export-policy changes can introduce rapid variance.
-
Regulatory headwinds: Measures aimed at accounting for embedded carbon and changing tariff structures are altering the competitive calculus for exporters, most notably those with large upstream ferroalloy footprints. Companies reliant on export markets should stress-test sourcing and pricing models against trade-policy scenarios.
-
Product differentiation and premiumization: High-purity and specialty cored wires for demanding steel grades and niche end uses (e.g., aerospace) are gaining attention. New product launches by established steel and alloy players signal an inflection toward higher-value offerings.
-
Regional demand rebalancing: Recovery trajectories differ across end markets. North America shows signs of steady improvement, which supports investments in local processing and feeder technologies; other regions continue to drive volume growth but with differing regulatory and cost structures.
Competitive landscape — what the leading players are signaling
-
P.C. Campana (Lorain, Ohio, USA) — A supplier of alloy cored wire and cored wire feeders focused on wire injection processes. Recent strategic moves include a planned plant opening in the southern United States (announced June 2026), signaling a deliberate push to increase regional capacity and service proximity to North American steel consumers. This underlines a playbook centered on localized production and integrated feeder technology as a route to capture incremental market share.
-
Anyang Chunyang Metallurgy Co., Ltd. (Anyang, China) — A manufacturer producing a range of cored wires for steelmaking. Chinese producers continue to leverage scale and supplier proximity to ferroalloy feedstocks; however, their export competitiveness must be assessed against evolving trade measures.
-
Wanhua Metal (Anyang, China) — A major producer reporting stable metallurgical silicon prices and signaling steady domestic market conditions. Public updates from 2025 suggest expectations for continuity in raw-material markets, which can support production planning but do not eliminate export or policy risks.
-
Anyang Huatuo Metallurgy Co., Ltd. (Anyang, China) — A diversified cored-wire manufacturer emphasizing deoxidizers and desulfurizers for steelmaking. Firms with R&D depth and a diverse alloy portfolio are better positioned to move up the value chain as demand for higher-specification inputs grows.
-
Other notable signals — Product innovation by larger steelmakers (e.g., a 2025 launch of a high‑purity ferro‑titanium cored wire targeted at aerospace applications) indicates that the premium segment will become increasingly contested and technically demanding.
Practical, decision-focused content in the PW Consulting report
-
Proprietary forward model: An end-to-end supply-demand framework with scenario toggles for raw-material price shocks, tariff regimes and regional demand recovery paths. All forecasts reference base-year 2025 inputs and extend through 2032.
-
Supplier scorecards: Structured assessments of manufacturing footprint, feedstock linkages, quality certifications and commercial coverage to help buyers shortlist partners for strategic sourcing or JV conversations.
-
Commercial playbook: Tactical guides for procurement teams (negotiation levers, inventory strategies, hedging approaches) and for production leaders (capacity timing, feeder investment thresholds, quality-control checkpoints).
-
Regulatory risk matrix: Impact assessments and mitigation options for changing trade policies, carbon border adjustments and export controls—scored by likelihood and business impact to prioritize actions in 2026.
-
M&A and capex decision framework: Triggers, valuation overlays and integration checklists for players considering bolt-on acquisitions, greenfield projects or strategic partnerships to capture growth while managing concentration risk.
Strategic recommendations for executives preparing 2026 plans
-
Rebase supply security: Execute a two‑tier sourcing strategy that combines (a) long-term agreements with established ferroalloy-linked producers and (b) contingency contracts or inventory buffers for short-cycle disruptions. Prioritize suppliers that can demonstrate traceable inputs and certification continuity under tightening regulatory scrutiny.
-
Pursue selective localization: Where regional demand and regulatory environment justify higher service levels, favor local or near‑market capacity to reduce freight, tariff vulnerability and lead times. The competitive move by North American-focused producers underlines this opportunity.
-
Differentiate through product and quality: Invest in R&D or partnerships to develop higher-purity and specialized cored wire grades that command margin premiums in aerospace and other advanced steels. Technical differentiation is a durable hedge against pure price competition.
-
Stress-test scenarios: Use the report’s scenario tools to quantify P&L sensitivity to raw-material swings and CBAM-like measures. Convert model outputs into concrete trigger points for capex approval or contingency sourcing.
-
Scan consolidation opportunities: Given the market’s moderate concentration (with the top five firms holding under half of revenues), inorganic moves—particularly bolt-ons that add feedstock access or process technology—can accelerate capabilities at relatively attractive multiples in selected subsegments.
How to use this briefing as a “strategic trailer”
Consider this article a high-resolution map of the terrain and an invitation to use PW Consulting’s proprietary instruments to navigate it. We deliberately present market-level growth, concentration and directional dynamics while reserving the full segmentation matrices, pricing trajectories, supplier financials and interactive dashboards for the complete report. That granular intelligence is where tactical decisions—sourcing tenders, capacity timing and M&A bids—are formulated with confidence.
Next steps
-
For procurement and strategy teams: Request the report’s supplier scorecards and the raw-material sensitivity module to inform Q1 contracting and inventory policy.
-
For R&D and product leaders: Obtain the section on specialty alloys and high‑purity wire specifications to align product roadmaps and qualification programs with emerging aerospace and high-spec steel opportunities.
-
For corporate development teams: Ask for the M&A decision framework and valuation comparables to evaluate targeted bolt-ons before bid windows close in a tightening market.
PW Consulting’s Cored Wire Market study equips decision-makers with the macro view, tactical toolset and competitor intelligence necessary to make higher‑confidence choices in 2026. To access the full dataset, segment-level analysis and interactive modeling tools referenced here, please download the full report from our market research page or contact our industry team for a brief tailored walkthrough.
For detailed analysis of this topic, please visit the official page: Cored Wire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com