

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: FCC Catalyst & Additives Market Poised for 4.25% CAGR (2026–2032)

Catalyzing Strategy: FCC Catalyst & Additives Market Outlook to 2032
As energy transition pressures and refinery economics converge, the fluid catalytic cracking (FCC) catalyst and additives market has entered a phase where incremental technical gains translate directly into refinery margin recovery. PW Consulting’s new FCC Catalyst Additive; FCC Catalyst and Additives Market study (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes market sizing, technology trajectories, regulatory stress-tests, and competitive positioning into a single, decision-grade deliverable for strategists and operators planning actions in 2026.
FCC Catalyst Additive; FCC Catalyst and Additives Market
Why this 2026-ready research matters
-
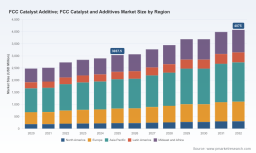
Actionable timing: The report uses 2025 as the strategic baseline and extends a modeled forecast to 2032. The market recorded steady expansion through 2020–2025 and reached a market scale of approximately USD 3,037.5 Million in 2025. Under our central-case layering of demand drivers and supply response, the market is projected to reach roughly USD 4,075 Million by 2032, representing a compound annual growth rate of 4.25% over the forecast window.
FCC Catalyst Additive; FCC Catalyst and Additives Market -
Decision alignment: For executives debating capital allocation, R&D pivots, or regional capacity moves in 2026, the report translates macro trends into scenario-specific implications—highlighting when to fast-follow, when to lead with differentiated additives, and when to secure feedstock or zeolite supply contracts to protect margin capture.
FCC Catalyst Additive; FCC Catalyst and Additives Market -
Risk-adjusted intelligence: Our work bundles regulatory sensitivities, price-cycle scenarios, and feedstock shocks into calibrated quantitative scenarios. This enables procurement, technology and M&A teams to stress-test plans against realistic upside and downside trajectories rather than relying on single-point forecasts.
Market dynamics shaping strategic options
-
Regulation as a demand lever: Stricter diesel sulfur limits and ultra-low sulfur diesel (ULSD) mandates, particularly where diesel remains critical for agriculture and power generation, continue to elevate the role of FCC units in meeting product specifications. These mandates are not just compliance items — they generate predictable aftermarket and catalyst demand cycles that incumbents and newcomers can monetize through bundled service models.
-
Co-processing and feedstock mix shifts: The advent and scaling of renewable diesel co-processing in conventional FCC streams is a nascent but material source of incremental catalyst demand. Industry modeling referenced in the study indicates that regulatory and mandate-driven co-processing initiatives in Europe and North America are expected to create measurable incremental catalyst throughput by the late 2020s. For refining groups, this translates into periodic re-specification windows where catalyst suppliers can capture requalification business.
-
Technology differentiation: Additive technologies—particularly those tuned to boost propylene and light-olefin yields under severe deactivation—continue to be the fastest route to near-term refinery margin improvements. Established formulations with strong field evidence (for example, third-party commercial trials that demonstrate sustained propylene yield improvements even after hydrothermal exposure) are high-value offerings during turnaround and feedstock transition campaigns.
-
Supply-side concentration: Market structure matters. The landscape remains moderately concentrated: the top-three suppliers control roughly 45.5% of market revenues while the top-five approach near 68.2% concentration, implying a competitive environment dominated by a small set of global players capable of deploying integrated commercial, technical and logistics solutions.
Competitive landscape—who matters and why
-
Johnson Matthey (London): A leading global provider of FCC additives and application systems, Johnson Matthey has built a differentiated value proposition around process optimization—helping refiners enhance LPG yields, curb SOx/NOx emissions, and stabilize FCC unit performance. Their integrated service approach—technical trialing, on-site support and packaged additive blends—continues to be a blueprint for value capture beyond simple product sales.
-
BASF (Ludwigshafen): With its ZEAL™ FCC additive family, BASF has focused on selective propylene enhancement in resid and gasoil FCC units. The product’s track record in commercial trials—demonstrating single-digit-to-teen propylene yield improvements even after hydrothermal deactivation—positions BASF as a go-to partner for refineries prioritizing olefin economics. Their playbook emphasizes targeted performance claims substantiated by rigorous field data.
-
Albemarle Corporation (Charlotte): Albemarle combines a broad catalyst portfolio with scale manufacturing and established customer relationships in gasoline and diesel-focused FCC operations. Its brands and formulation variants (across product families built for different feedstocks and product mixes) make Albemarle a practical choice where operational resilience and supply continuity are primary buying criteria.
-
Grace & Co.-Conn. and regional supply shifts: Recent industry activity underscores the strategic value of localized capacity. In March 2026, Grace completed phase one of an FCC catalyst plant in the Middle East in partnership with a regional agricultural partner; this development illustrates a broader movement toward regional production footprints that shorten lead times and reduce import exposure for resid-focused FCC operations.
What the PW Consulting report contains (practical, executable modules)
-
Concise market sizing and forecast model—base year 2025, historical 2020–2025, and 2026–2032 projections with transparent methodology and scenario toggles to test feedstock, regulation and technology adoption shocks.
-
Competitor benchmarking—product portfolios, go-to-market models, and technical scoring across performance dimensions (yield impact, deactivation resilience, environmental compliance contribution, bundled services).
-
Technology roadmaps—shortlists of additive innovations and catalyst architectures (including zeolite-rich solutions and hybrid formulations), mapped to refinery archetypes and requalification pathways.
-
Supply chain and manufacturing profile—capacity maps, lead-time risk assessments, and recommendations for localization vs. centralized sourcing under multiple trade and tariff scenarios.
-
Regulation and demand stress-tests—quantified impacts of ULSD rollouts and renewable diesel co-processing mandates on catalyst demand, including timing windows for commercial capture.
-
M&A and partnership playbook—scorecards for acquisition targets and partnership archetypes, including valuation levers tied to technical IP, customer contracts and manufacturing footprint.
-
Operational playbooks—practical steps for refinery and catalyst suppliers to accelerate trial uptake, shorten qualification cycles and convert performance data into commercial contracts.
Strategic implications for 2026 decisions
-
Prioritize requalification pipelines: For refiners planning feedstock shifts or renewable co-processing pilots in 2026, allocate a clear testing and requalification budget for FCC additive trials. Early movers who secure validated performance in the pilot phase will create negotiation leverage when full-scale conversion decisions arise.
-
Lock in material pathways: Given periodic feedstock-induced catalyst performance variability, securing committed supply of critical raw materials and key zeolite variants can be a low-cost insurance policy against price and delivery volatility. Assess whether strategic inventory buffers, dual-sourcing, or regional partnership models (e.g., joint ventures) better align to your risk tolerance.
-
Invest in service integration: The market premium tilts toward suppliers who bundle additives with analytics, on-site support and performance guarantees. Refiners should evaluate supplier proposals on total delivered value rather than unit price per kg—differential lift in product yields and product quality often dwarfs upfront material costs.
-
Use M&A selectively to capture capability gaps: For technology seekers, small-to-medium targets with proven formulation IP or regional manufacturing footprints can accelerate market entry more cost-effectively than greenfield builds—especially where local regulatory or logistics advantages exist.
Where this report leaves discretion—and why
In keeping with the “trailer” principle, this article demonstrates the analytical depth of PW Consulting’s study while intentionally withholding certain segment-level breakdowns and full tabulated regional splits that are central to commercial negotiation and competitive modeling. The study contains those detailed data tables, supplier scorecards, and downloadable scenario models behind a secure access portal; they are provided to clients and registered subscribers so that decision-makers can apply the numbers within their proprietary planning contexts.
Final note—how to use this intelligence in Q1–Q2 2026
Use the report as a bridge between strategy and execution. In the next 6–9 months, boards and executive teams should: (1) finalize feedstock transition roadmaps, (2) open competitive trials with two or more suppliers using standardized KPIs, (3) lock strategic supply agreements where lead times and regulatory timelines expose fragility, and (4) assess acquisition targets or regional partnerships to de-risk localized demand growth. The market’s steady expansion—from a multi-billion-dollar baseline in 2025 toward a materially larger horizon by 2032 at a 4.25% CAGR—creates windows for both defensive and offensive moves. The winners will be the organizations that combine technical rigor with commercial agility.
To access the full datasets, supplier scorecards, and scenario models behind these conclusions, consult the PW Consulting FCC Catalyst Additive; FCC Catalyst and Additives Market report and our interactive web portal. The report provides the granular segmentation tables, regional forecasts and application-level economics that operational teams will require to convert this strategic insight into measurable action.
For detailed analysis of this topic, please visit the official page: FCC Catalyst Additive; FCC Catalyst and Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com