

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Spherical Silica Market to Reach USD 335 Million by 2032 at 6.53% CAGR

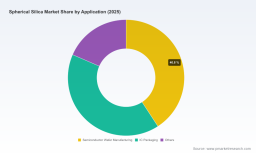
Spherical Silica Market — Strategic Preview for 2026 Decision-Making
Executive snapshot
The spherical silica market is transitioning from specialty niche to strategic input. Between 2020 and 2025 the global market expanded steadily, and our modelling places 2025 as the analytical base year. Compound annual growth of approximately 6.53% underpins a projection that the industry will continue its expansion through the 2026–2032 forecast window. This preview highlights the commercial inflection points, supply-side vulnerabilities, and competitive motifs that every executive in materials, semiconductor supply chains, advanced packaging, and high-performance coatings should factor into 2026 capital and commercial plans.
Spherical Silica Market
Why this matters in 2026
For 2026 corporate planning cycles, spherical silica is no longer a passive commodity line item. It is a performance enabler for semiconductor wafer processes, advanced electronics packaging, precision films, and a growing set of optical, sensor, and 5G-related applications. Procurement, product, and M&A teams must treat the material as a strategic lever: small shifts in purity, particle morphology, or supplier footprint can have outsized effects on yield, regulatory compliance, and time-to-market for next-generation devices.
Spherical Silica Market
Market trajectory — what the top-line tells us
Our top-line historical and forecast series provide an unambiguous macro frame: the market demonstrated steady recovery and growth through 2020–2025, and our base-year synthesis (2025) anchors the forward-looking outlook for 2026–2032. Total market value rose meaningfully through the historical period and continues upward in our central scenario, reaching a materially larger industry size by the end of the forecast window. The blended CAGR of 6.53% reflects a combination of demand expansion in electronics and packaging, premiumization toward ultra-high-purity grades, and incremental pricing driven by upstream cost pressure. Importantly, the market structure is moderately consolidated — the top three players do not dominate the full space, while the top five form a more substantial share — a concentration profile that shapes competitive dynamics and M&A opportunity sets for 2026.
Spherical Silica Market
Key dynamics shaping 2026 strategy
- Energy- and process-intensity is strategic: High-purity spherical silica production depends on flame fusion, plasma spheroidization, and precision drying. Those processes drive materially higher operating costs relative to conventional silica — on the order of magnitude cited by industry operatives — which creates an intrinsic floor under premium grade pricing and narrows the pool of financially viable producers.
- Feedstock and technical consistency risk: Multiple suppliers report constraints on ultra-fine quartz feedstock and the technical complexity of converting it into consistently dispersed, ultra-fine spherical particles. These upstream frictions increase variability risk for buyers that rely on repeatable process performance (for example, semiconductor epoxy molding compounds and high-performance films).
- Regulation and capex imperatives: Environmental and emissions regulations are triggering retrofits and new-capex requirements for a non-trivial share of production assets. Firms with older plants face accelerated investment cycles to remain compliant and to achieve the quality standards demanded by advanced electronics customers.
- Margin pressure and premiumization: While base-grade volumes remain important, value is migrating to high-purity, tightly controlled particle distributions and surface treatments. Producers that can combine process control with scale capture premium margins; those that cannot face margin compression as energy and feedstock costs rise.
- Supply concentration and sourcing resilience: The market’s concentration profile means that supplier disruptions — whether from technical faults, regulatory enforcement, or feedstock shortages — have rapid downstream implications. Buyers should re-evaluate single-source positions and develop multi-tier sourcing strategies in 2026.
Competitive landscape — how leading players are positioned
The competitive set comprises established chemical majors and specialized silica technology houses. Several features differentiate winners from laggards:
- Technology depth and product breadth: Japanese specialty players and certain European majors combine decades of R&D with production processes tuned for ultra-high purity and narrow particle distributions. Those capabilities are critical for semiconductor and advanced packaging customers demanding low-defect rates and consistent supply.
- Integrated upstream control: Firms that control or secure stable feedstock streams and that have invested in next-generation spheroidization technologies reduce quality variance and protect margins.
- Service and co-development orientation: Suppliers that offer formulation support, analytics, and joint development with OEMs tend to win into long-term contracts — an advantage as electronics makers seek materials partners rather than commodity vendors.
Representative players exemplify these archetypes. Some focus on fused and plasma-spheroidized offerings for semiconductor and packaging applications; others bring colloidal and composite spherical silica for coatings, toner, and industrial films; and several blend global scale with specialized grades aimed at automotive sensors and 5G electronics. In 2026, expect leaders to press on process control, geographic resilience, and high-touch customer integration. Meanwhile, mid-tier producers will look to either specialize in narrow high-value niches or pursue consolidation to achieve scale economics.
What our full study delivers (practical, actionable modules)
The PW Consulting Spherical Silica Market report is structured around executive decision needs for 2026 and beyond. Key operational and strategic modules include:
- Supply-chain stress tests: Quantitative scenarios that simulate feedstock shocks, plant-level downtime, and regulatory-driven capacity contraction to estimate downstream yield and delivery risk under alternative procurement strategies.
- Technology and process roadmaps: Comparative analysis of fusion, plasma, and spray-drying routes, including CAPEX/OPEX profiles, energy intensity benchmarks, and likely cost curves for scaling ultra-fine grades.
- Regulatory and environmental compliance playbook: A checklist and investment phasing plan for emissions controls, permitting, and traceability requirements that affect high-purity whitepapers and production continuity.
- Commercial playbooks: Pricing strategy templates, contract structures (e.g., blended-volume agreements, quality ladders, earnouts for co-development), and negotiation levers tailored to incumbent suppliers and new entrants.
- M&A and partnership screening: A prioritized target set and diligence scorecards based on technology fit, geographic footprint, and integration risk — optimized for acquirers seeking access to high-value grades or geographic resiliency.
- KPIs and integration blueprints: Recommended metrics to monitor supplier performance, particle-size stability, batch-to-batch variance, and environmental compliance — together with a 90/180/365-day integration checklist for rapid supplier on-boarding.
Strategic playbook for 2026
We recommend executives adopt a layered approach in their 2026 plans:
- Immediate (0–6 months): Complete supplier risk-mapping, institute secondary sourcing mandates for critical grades, and commence targeted audits of supplier process controls and emissions compliance.
- Near-term (6–18 months): Negotiate multi-year, quality-tiered contracts with embedded penalty/rebate mechanisms tied to particle distribution and delivery performance; invest in joint-development programs with one or two strategic suppliers to lock-in priority capacity for high-value applications.
- Medium-term (18–36 months): Consider strategic equity partnerships, minority investments, or bolt-on acquisitions to secure feedstock access and localized production in priority regions; evaluate on-shore vs. near-shore manufacturing models to mitigate logistics and regulatory risks.
- Cross-cutting: Invest in in-line analytics and incoming-material testing at critical process nodes to reduce defect-to-yield risk and to create negotiation leverage with suppliers.
Scenarios to stress-test strategy
Our modelling includes multiple scenarios that pivot on three axes: feedstock availability, regulation intensity, and end-market demand (particularly semiconductor and advanced packaging). In our central case the industry grows in line with the published CAGR, but both upside and downside pathways are credible depending on geopolitical trade dynamics, regulatory stringency, and semiconductor cycle amplitude. The study provides quantitative outputs for each scenario so that leaders can align CapEx and inventory decisions with their risk tolerance.
How to use this preview — and where the hidden value is
This article purposefully surfaces the strategic frames, operational levers, and competitive motifs that will determine winners in 2026. Per the “trailer” design, it does not disclose the granular segment and regional splits, nor the row-level datasets that underpin our scenario outputs — those detailed tables, supplier-by-supplier qualitative scores, and the downloadable stress-test models are available in the full report. If your organization is preparing procurement strategies, capital allocation, or M&A mandates for the 2026 planning cycle, the full dataset provides the necessary precision to convert the directional guidance presented here into executable decisions.
Closing — the decision moment
At the intersection of an expanding addressable market, process-intense production economics, and tightening regulatory expectations, spherical silica has become a strategic input that requires proactive management. The coming 12–24 months are a decision window: firms that invest in supply resilience, co-development partnerships, and emissions-compliant capacity will unlock premium returns; those that defer will face higher sourcing costs and operational risk. PW Consulting’s full Spherical Silica Market study supplies the analytical foundation — from scenario data and supplier scorecards to execution playbooks — to make confident, defensible choices in 2026.
For detailed analysis of this topic, please visit the official page: Spherical Silica Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com