

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
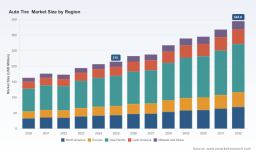
PW Consulting: Auto Tire Market to Reach USD 344.8 Million by 2032 at 5.6% CAGR

Auto Tire Market 2026: Strategic Preview for Decision-Makers
Executive snapshot
The global auto tire market is entering 2026 from a position of steady expansion and structural reconfiguration. Using 2025 as the analytical base year and a historical lens spanning 2020–2025, our forecast (2026–2032) embeds a compound annual growth rate of 5.6% and projects continued top-line growth through the forecast window. The trajectory from the pandemic recovery phase into a mid‑decade environment marked by regulatory evolution, raw material volatility and differentiated product innovation creates a strategic inflection point for OEMs, tire manufacturers, dealers and institutional buyers.
Auto Tire Market
Why this report matters for 2026 decisions
-
Timing: 2026 is a pivot year for both regulation and procurement cycles. Our analysis aligns market sizing and trend signals with the procurement and R&D timetables of automotive OEMs and large fleet operators so that resource allocation decisions made now unlock advantages across 2026–2028.
Auto Tire Market -
Signal-to-noise: Macro indicators (demand growth, input cost trajectories and regulatory shifts) are producing mixed signals. This report separates durable structural trends—such as mobility electrification impacts on load and rolling-resistance requirements—from temporary demand swings tied to economic cycles and inventory correction.
Auto Tire Market -
Actionability: Beyond descriptive forecasting, the study gives playbooks for five common strategic objectives—cost containment, product premiumization, aftermarket expansion, regional network optimization, and M&A—allowing senior leaders to translate market intelligence into 90–180 day action plans.
Market trajectory: what the numbers tell us (high-level)
From a recovery-stage volume in the early 2020s to sustained revenue expansion into the early 2030s, the industry is forecast to exhibit mid-single-digit CAGR through 2032. That growth is underpinned by a combination of replacement demand resilience, continued vehicle parc growth in selective geographies, and higher-value product adoption (including energy-efficient, EV‑optimised and premium performance tires). While we provide comprehensive time-series topology across 2020–2032 in the full report, deliberate withholding of granular split values in this preview is intended to focus executives on strategic interpretations rather than raw segment disclosure.
Key dynamics shaping 2026 strategy
-
Regulatory inflection: Multiple regulatory vectors are converging. Regional standards tightening around tire wear particle emissions are now material to product design and validation programs, even as other jurisdictions adjust vehicle-level greenhouse gas regulations. These divergent regulatory moves create both risk and arbitrage opportunities for manufacturers with flexible platforms and strong technical validation capabilities.
-
Input cost and supply chain pressure: Natural rubber remains a critical raw material and a strategic supply risk—its availability and price volatility materially influence product economics, especially for heavy-duty and specialty treads that rely on higher natural rubber content. Producer price indices for rubber and plastics indicate sustained inflationary pressure on input costs, requiring procurement innovation and hedging strategies.
-
Product differentiation and OEM leverage: OEMs are increasingly selective about tire specifications as vehicle electrification and range optimization place new demands on rolling resistance, vertical load and noise characteristics. Tier‑1 suppliers that can demonstrate validated performance gains across EV and ICE platforms are positioned to secure lucrative OEM fitments.
-
Aftermarket and channel transformation: The aftermarket remains the backbone of demand resilience. Yet channel economics are shifting as large retailers and digital platforms use private-label strategies and bundled service models. Competitors with integrated retail networks or strategic distributor partnerships can extract higher margin capture in replacement segments.
Competitive landscape: what to watch in 2026
The market exhibits meaningful concentration at the top, with leading manufacturers controlling a substantial share of capacity and OEM relationships. The competitive dynamic is marked by two parallel plays: (a) high-performance, premiumization and technology-led differentiation; and (b) scale, private-label and cost leadership for replacement and fleet channels.
-
Michelin — The company continues to anchor its strategy on premium passenger and SUV tires that emphasize energy efficiency, endurance and safety. Recent product recognition and OEM selections underscore Michelin’s success in translating R&D into platform fitments. For partners and competitors, Michelin’s trajectory signals the importance of validated performance metrics and brand premiumization in securing OEM mandates.
-
Bridgestone — Bridgestone is expanding into specialized heavy-duty domains alongside its all‑weather passenger and commercial portfolios. New product introductions for niche segments highlight a diversification play that balances high-margin technologies with industrial-scale volume businesses.
-
Goodyear — With offerings spanning light and heavy-duty applications and an expanding sustainable-product roster, Goodyear is reinforcing its dual focus on performance and durability, aiming to serve both OEM programs and the aftermarket with differentiated options.
-
Continental — Continental’s emphasis on high‑tech tires—targeting safety, rolling resistance and integrated sensor platforms—makes it a pivotal competitor where technological differentiation and vehicle systems integration matter most.
-
Pirelli — Pirelli’s premium and luxury vehicle focus demonstrates the commercial attractiveness of high-value OEM partnerships and specialty performance niches, where brand prestige and validated performance drive margin expansion.
-
Regional and value players — Companies focused on private-label, value replacement and fleet tires continue to capture aftermarket share by leveraging distribution partnerships and cost-competitive sourcing. These players are especially relevant for retail partners and fleet managers seeking lower TCO solutions.
-
Specialist producers — Firms with expertise in winter tires and severe-climate traction highlight the value of product specialization in defending regional leadership and commanding pricing power in weather-sensitive markets.
Notable recent developments (indicative)
-
Product accolades and OEM selections have amplified brand advantage for certain premium manufacturers during the first half of 2026, signaling continued OEM appetite for validated efficiency gains.
-
Manufacturers are launching new ranges into specialized applications—from underground mining to historic motorsport—indicating both diversification of engineering capability and opportunistic market capture in underserved niches.
-
Expansion of performance and heritage portfolios demonstrates a parallel strategy to reach high-margin enthusiast segments while supporting brand halo effects into mainstream OEM and replacement businesses.
What the full report contains (practical, operational deliverables)
-
Comprehensive time-series market sizing (2020–2032) with scenario-based forecasts and sensitivity analyses tailored to cost, regulation and electrification trajectories.
-
Actionable playbooks for five executive priorities: supplier diversification and procurement hedging; OEM engagement and product roadmaps for EVs; aftermarket and channel monetization; pricing and margin recovery strategies; M&A and joint-venture heuristics for capacity and technology access.
-
Competitive benchmarking matrices that map capability, R&D focus, channel reach and go-to-market models across incumbent leaders and regional challengers (note: core segment tables are available in the full report).
-
Regulatory impact heatmaps and compliance timelines that convert regulatory text into engineering, testing and labeling milestones for product development calendars.
-
Procurement and input-cost playbooks that translate rubber and polymer price scenarios into unit-cost outcomes and margin-preservation tactics (including supplier contracting templates and hedging alternatives).
-
Executive decision-support tools—scorecards and dashboards—designed to be embedded into quarterly business reviews and capital-allocation discussions.
Strategic recommendations for 2026
-
Prioritize dual-track product development: maintain a premium technology pipeline for OEM fitments while accelerating cost-optimized SKUs for the aftermarket and fleet segments.
-
Lock in procurement resilience: implement near-term hedging or long-term contracts for natural rubber and key polymers; diversify supplier geographies with contingency capacity agreements.
-
Invest selectively in certification and testing capabilities aligned with emerging wear‑particle and noise regulations—early movers will shorten lead times for OEM homologation.
-
Pursue channel partnerships and private-label strategies where margin recovery is likely; conversely, defend OEM relationships through demonstrable lifecycle value and integrated vehicle-system performance proof points.
-
Evaluate bolt-on M&A to access specialty capabilities (e.g., winter or heavy‑duty expertise) or to secure aftermarket distribution in priority markets rather than greenfield buildouts.
How to use this preview
This introduction is a strategic trailer: it reveals the signal architecture of our analysis—growth trajectory, structural drivers, competitive positioning and immediate strategic imperatives—while reserving granular segment-level data and tables for the full report. Senior teams should use this preview to align their 2026 planning sprints, identify which internal capabilities to stress‑test, and prioritize scenario runs with finance and procurement teams.
Closing: immediate next steps for executives
-
Schedule a 60‑minute strategy workshop with your product, procurement and BD leads to map the recommendations onto current 2026 roadmaps.
-
Request the full PW Consulting Auto Tire Market report to unlock the segment-level tables, regional matrices and competitor scorecards necessary for transaction diligence or detailed product-cost modelling.
-
Initiate a rapid supplier resilience assessment focused on natural rubber exposure and validate contingency capacity for critical SKUs within 30–60 days.
PW Consulting’s full Auto Tire Market study provides the granular evidence base to operationalize the strategic directions outlined here. For access to the complete datasets, segmentation tables and bespoke executive workshops, please request the full report through our corporate channels.
For detailed analysis of this topic, please visit the official page: Auto Tire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com