

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Mouthguard Market to Reach USD 588.28M by 2032 at 5.2% CAGR

Mouthguard Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
As PW Consulting’s lead industry analyst, I present this executive introduction to our comprehensive Mouthguard Market study. The analysis synthesizes historical performance (2020–2025), a detailed 2026 baseline, and forward-looking scenario modeling through 2032. At a high level, the market expanded from roughly USD 316 million in 2020 to about USD 416 million in 2025, and—at a compound annual growth rate (CAGR) of 5.2%—is projected to approach the high‑500s (USD Million) by 2032. This brief explains why those topline numbers matter for boardrooms and commercial teams planning resource allocation, product investments, and M&A strategies in 2026, while intentionally omitting the granular subsegment tables that are available in the full report.
Mouthguard Market
Why this market matters in 2026
-
Stable, investable growth. A mid-single‑digit CAGR signals an established market with steady demand drivers—sports participation, greater dental awareness, and therapeutic use cases—making it suitable for both organic expansion and bolt‑on consolidation.
Mouthguard Market -
Regulatory and reimbursement inflection points. Recent regulatory clearances and evolving payer policies are changing commercialization paths: some mouthguards are increasingly treated as medical devices with pathways to clinical reimbursement, while others remain squarely consumer/OTC products. This bifurcation creates differentiated go‑to‑market and pricing strategies.
Mouthguard Market -
Room for differentiation. Market concentration metrics indicate moderate fragmentation: the top three and top five participants command material but not dominant shares. This dynamic preserves scope for brand-building, niche technical differentiation, and regional scale plays.
Market dynamics: drivers, constraints, and the tactical calendar for 2026
Understanding the interplay between product, channel, and policy is essential to convert market growth into profitable share gains.
-
Material and manufacturing trends. EVA and PETG thermoplastics remain the production workhorses for boil‑and‑bite and custom devices, with common thicknesses designed for impact protection. Advances in remoldable medical‑grade polymers and vacuum‑forming efficiency are enabling faster turnaround and iterative consumer fit—an advantage for direct‑to‑consumer (DTC) models and team procurement.
-
Standards and clinical validation. ANSI/ADA standards remain the quality backbone; ADA acceptance and demonstrated impact‑absorption performance are converting into distribution benefits with dental channels and institutional purchasers. For many purchasers, an ADA endorsement materially lowers friction to adoption.
-
Regulation and coding. The device pathway and coding environment matter—as evidenced by recent 510(k) clearances and updated CMS guidance on device coding. These shifts create opportunities for manufacturers to pursue clinical claims and reimbursement where product design and documentation support it, but also increase compliance complexity for companies selling across consumer and medical channels.
-
Payer posture. Dental plans commonly cover clinically indicated custom night guards but generally exclude most over‑the‑counter athletic mouthguards. This creates a bifurcated value chain: clinically coded, higher‑margin medical channels versus volume‑driven retail and sports distribution.
Competitive landscape — positioning and strategic implications
The competitive set spans specialist manufacturers, dental‑channel incumbents, and consumer brands focused on sports protection. Key archetypes and tactical considerations include:
-
Premium performance specialists (e.g., brands with remoldable medical‑grade polymers): These players emphasize repeatability of fit, remoldability, and measurable impact attenuation. Their strengths are technical differentiation and premium pricing; risks are higher manufacturing cost and the need for clinical validation to unlock medical channels.
-
Dental‑channel and ADA‑aligned vendors: Brands that hold ADA acceptance or actively pursue dental partnerships capture clinical distribution advantages—dentists and payers are more likely to recommend and reimburse these products. For competitive strategy, prioritizing clinical evidence and dental professional engagement yields asymmetric channel access.
-
Mass‑market boil‑and‑bite players and retail brands: These participants scale via retail and team sales, leveraging price and convenience. Their playbook favors manufacturing efficiency, color/branding differentiation for sports teams, and partnerships with retailers and associations.
Representative companies from our coverage illustrate these archetypes. Some offer premium moldable/remoldable thermoplastics designed for ongoing fit adjustment; others emphasize dentist‑grade custom options or ADA‑accepted, higher‑impact absorption products. Several recent regulatory and commercial moves—FDA 510(k) clearances for novel night‑guard/mouthguard devices and expanded retail programs via insurer partnerships—underscore how product claims, clinical acceptance, and distribution collaborations are being used to capture demand.
Recent developments and what they signal for 2026 strategy
Three themes are especially actionable:
-
Regulatory momentum: Recent 510(k) clearances for night‑guard platforms being marketed also for mouthguard use demonstrate a path for clinical positioning in borderline device categories. Firms that can document equivalence and safety quickly can move into payor‑facing channels.
-
Payer and channel activation: Insurer programs and dental network retail launches show how partnerships—rather than pure product innovation—can materially expand access and price realization. Securing a program with a major dental payer or network can accelerate unit volumes and brand trust.
-
Standards and materials as competitive gatekeepers: Adherence to ANSI/ADA standards and intelligent material selection (balancing protection, comfort, and manufacturing cost) remain fundamental to unlocking both sports and medical buyers.
What the PW Consulting report delivers — practical contents for 2026 decision-making
The full PW Consulting Mouthguard Market report is structured to transform insight into action. Highlights include:
-
Top‑line market size series (2020–2025) with a 2026 baseline and detailed scenarios to 2032—incorporating sensitivity to participation rates, reimbursement changes, and manufacturing cost trends.
-
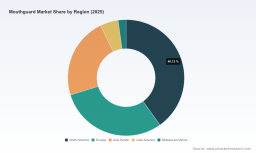
Segmentation by product type, application, and region with demand drivers and commercial playbooks for each segment. (Note: the full report contains the granular split tables and values that underpin our strategic recommendations.)
-
Competitive benchmarking: detailed profiles and strategic positioning analyses for the leading players, plus a mapped set of mid‑market potential acquisition targets and contract manufacturers.
-
Regulatory, coding, and reimbursement playbook: step‑by‑step guidance to pursue 510(k) pathways, achieve ADA recognition where beneficial, and structure payer engagement for medical channel revenue.
-
Commercial roadmaps: go‑to‑market templates for DTC, dental‑professional, retailer, and team procurement channels; pricing levers and margin models; and a prioritized investment list for R&D, clinical evidence generation, and channel partnerships.
-
Financial decision tools: integrated ROI calculators, scenario P&L models, and valuation proxies to support M&A screening and internal capital allocation decisions.
-
Primary research: interviews with clinical stakeholders, major distributors, and OEMs, supplemented by supplier cost benchmarks and manufacturing lead‑time matrices.
Actionable strategic recommendations for 2026
-
Prioritize clinical and standards investments. For companies targeting higher price realization and payer channels, allocate budget to clinical studies, ANSI/ADA alignment, and documentation that supports regulatory pathways.
-
Segment go‑to‑market by channel. Separate commercial playbooks for dental/professional vs retail/sports channels to avoid channel conflict and to optimize pricing and promotional spend.
-
Explore insurer and network partnerships. Pilot programs with dental insurers or associations can validate demand and create distribution hooks that competitors without payer relationships cannot easily replicate.
-
Optimize manufacturing footprint. Leverage material choices and supplier consolidation to preserve margin while maintaining product performance; consider OEM relationships for capital‑light scaling.
-
Evaluate targeted M&A. Given moderate concentration, selectively acquiring adjacent technical know‑how or regional distribution can accelerate share gains without paying for full market takeover premiums.
How to use this brief and where to get full details
This article is a strategic preview: it synthesizes the macro trends, competitive archetypes, and tactical imperatives you must weigh in 2026. For executives building detailed investment cases, commercialization budgets, or acquisition models, the full PW Consulting report contains the underlying segmentations, spreadsheets, and primary‑research appendices you will need to operationalize these recommendations. The complete dataset includes the full regional, type, and application splits, supplier cost tables, and executable go‑to‑market playbooks.
To convert the market’s steady growth into durable competitive advantage next year, leaders must move beyond product thinking to orchestrate evidence, standards, and channel partnerships. PW Consulting’s full Mouthguard Market study provides the calibrated market sizing, scenario tools, and regulatory roadmap to make those decisions with confidence.
Contact PW Consulting to access the full report and the accompanying data workbooks to support your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Mouthguard Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com