

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Insulated Metal Panels Market to Hit USD 1,420M by 2032, Growing at 6.7% CAGR — PW Consulting

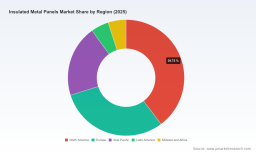
Insulated Metal Panels Market: Strategic Intelligence Briefing for 2026 Decision-Makers
As PW Consulting’s senior industry analysts, we present an executive preview of our latest Insulated Metal Panels (IMP) Market research — a focused intelligence briefing designed to inform capital allocation, procurement strategy, product-specification choices, and M&A considerations for 2026. This overview highlights the strategic value of the full study: its macro market sizing and trajectory, the competitive dynamics shaping supplier selection, near-term disruptive pressures, and the types of actionable analysis the full report delivers. In keeping with the “trailer” principle, we showcase the study’s analytical depth while intentionally withholding granular segment-level figures to drive stakeholders to the full report for transaction-ready data.
Insulated Metal Panels Market
Why this research matters for 2026
-
Market scale and trajectory: The IMP market has reached a robust scale in our 2025 base year and is projected to sustain mid-single-digit growth through the 2026–2032 forecast window at a compound annual growth rate of 6.7%. This trajectory reflects accelerating adoption driven by energy-code tightening, modular building trends, and heightened corporate ESG targets that prioritize building envelope performance.
Insulated Metal Panels Market -
Timing: 2026 is a pivotal year for buyers and suppliers. New energy-code requirements across multiple jurisdictions, resurfacing tariff pressures on steel and aluminum, and continued volatility in polymer feedstock pricing combine to create a high-stakes operating environment where specification choices and supplier contracting terms locked in now will materially affect total cost of ownership over the next 7+ years.
Insulated Metal Panels Market -
Strategy fit: Whether you are a developer, institutional owner, contractor, or IMP manufacturer, the study provides the scenario modeling and procurement playbooks necessary to translate market momentum into defensible long-term value — from bid evaluation frameworks to retrofit prioritization algorithms for existing portfolios.
Headline market context
From a demand perspective, the IMP market is being shaped by several converging forces. Tighter energy codes and growing specification requirements for continuous insulation are raising the baseline thermal-performance expectations for façades and roofing systems. This technical demand is complemented by ongoing interest in factory-controlled building systems — driven by labor constraints and speed-to-occupancy priorities in commercial and industrial construction.
On the supply side, manufacturers face a volatile cost environment. Steel and insulating-polymer feedstocks have demonstrated high price sensitivity, and policy instruments — notably Section 232 trade measures — remain a material cost variable for 2026 projects. The interplay of these factors means buyers should treat supplier price lists and lead times as negotiable levers rather than fixed inputs, and suppliers must be prepared with hedging, forward procurement, and contractual protections.
What the full PW Consulting report delivers
-
Market sizing and forward-looking scenarios — granular historical build-up and a base-year 2025 model with a transparent forecast engine for 2026–2032. We provide scenario pathways that stress-test demand under different tariff, raw-material, and code-enforcement assumptions.
-
Segment intelligence — product-type, application, and regional demand drivers, with practical implications for sales funnels, inventory allocation, and regional production footprint optimization (note: segment-level financial tables are reserved for the full report).
-
Competitive landscaping and supplier scorecards — side-by-side commercial and technical comparisons, capability heatmaps, and procurement negotiation playbooks tailored by buyer profile (owner vs contractor vs distributor).
-
Pricing and margin benchmarking — a practical toolkit for evaluating supplier quotes, incorporating raw-material pass-through models, and estimating end-customer TCO across common build-ups.
-
Regulatory and specification matrix — a jurisdictional view of evolving energy codes and inspection regimes, with recommended spec language that balances performance, cost, and constructability.
-
Risk & contingency planning — supply-chain stress tests, inventory and lead-time mitigation measures, and contracting templates to protect both buyers and manufacturers amid tariff and feedstock volatility.
-
M&A and partnership playbook — valuation sensitivities, bolt-on acquisition targets, and integration considerations for manufacturers seeking scale or channel expansion.
Competitive landscape — capabilities that matter in 2026
The IMP competitive set is a mix of large vertically integrated global producers and nimble regional specialists. The market concentration metrics indicate a mid-to-high range of concentration among the top players, creating an environment where national accounts seek global consistency while regional contractors value local service and lead-time reliability. Key supplier archetypes and strategic differentiators include:
-
Performance and sustainability leaders — Suppliers that pair high thermal-efficiency cores with sustainability credentials (e.g., product EPDs, Cradle to Cradle certifications) command a premium in projects where lifecycle carbon and operational energy are primary procurement criteria.
-
Cold-chain and mission-critical specialists — Providers that design blister-free polyurethane cores and tight joint systems for cold storage or controlled-environment spaces win on durability and long-term serviceability.
-
Architectural and façade integrators — Companies that offer a broad palette of factory-applied finishes, integrated fenestration and louvers, and aluminum skin options meet the needs of commercial and institutional markets focused on aesthetics and life-safety compliance.
-
Regional manufacturing partners — Firms leveraging local production and joint ventures to shorten lead times and reduce tariff exposure are increasingly attractive to national contractors managing tight schedules.
Representative manufacturers discussed in the full study include global innovators with hybrid-core platforms, major steel-origin manufacturers with cold-storage lines, and U.S.-based architects and logistics-focused suppliers offering integrated wall and roof systems. Each company profile in the report includes product technical differentiation (core chemistry, joint systems, factory finishes), manufacturing footprint, channel strategy, recent capital investments, and commercial positioning.
Recent developments and what they signal
-
Facility and product showcases from leading suppliers — recent headquarters and facility investments that double as live proof points for product performance demonstrate a marketing shift: manufacturers are using flagship builds to reduce buyer due diligence friction and accelerate specification adoption.
-
Trade-show participation and specification updates — active presence at industry expos and refreshed technical catalogs signals intensified competition for architectural accounts and increased emphasis on solar-integration and fire-rated solutions.
-
Policy and market noise — high raw-material price volatility and historic trade measures continue to influence short-term pricing behavior and contracting practices; prudent buyers will treat supplier quotations as subject to indexed adjustments tied to transparent commodity pass-through formulas.
Strategic implications and recommended moves for 2026
-
Lock in performance, not just price. Given tightening energy codes, buyers should specify thermal performance bands and verification testing procedures instead of relying solely on nominal R-values. This reduces downstream risk and allows bidders to propose alternative core chemistries that meet performance at lower life-cycle cost.
-
Hedge raw-material exposure. Manufacturers and large buyers should adopt hedging strategies or multi-year supply agreements for critical inputs. Contract clauses that balance cost pass-through with volume commitments are practical compromises in a high-volatility environment.
-
Prioritize supplier resiliency. Evaluate suppliers for regional production capability, inventory strategy, and contingency logistics. Lead time predictability has become as important as per-unit cost in projects where schedule delays trigger significant downstream penalties.
-
Leverage certification and EPDs as differentiators. For owners with ESG targets, selecting products with verified environmental credentials reduces reporting burdens and can improve access to green financing — an increasingly common lever in capex decisions.
-
Adopt scenario-based procurement. Use the report’s scenario matrices to run “what-if” procurement outcomes under different tariff and polymer-price trajectories; tender structures built on these scenarios produce more robust award decisions.
-
Plan for retrofit acceleration. The report outlines which building types and envelope approaches deliver the fastest ROI for IMP retrofits versus full envelope replacement — critical input for portfolio owners prioritizing energy-savings investments under limited budgets.
Conclusion — how to use this preview
The PW Consulting Insulated Metal Panels Market study is structured to be immediately actionable for 2026 decisions: it pairs market-scale context (base-year 2025 and the 2026–2032 forecast trajectory at a 6.7% CAGR) with practical tools for procurement, specification, and corporate planning. The analysis synthesizes company-level capabilities, recent supplier developments, and policy-driven risk factors into a decision-ready format that supports capital-allocation, sourcing negotiation, and M&A diligence.
To access the full dataset, provider scorecards, and downloadable procurement templates that translate these insights into executable initiatives, please consult the PW Consulting report landing page. The full report contains the granular segment tables, price models, and supplier financials that strategic and commercial teams will need to operationalize these recommendations.
For detailed analysis of this topic, please visit the official page: Insulated Metal Panels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com