

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Isophorone Market Poised for 5.2% CAGR — PW Consulting Insight

Isophorone (CAS 78-59-1) Market — Strategic Outlook for 2026
Executive summary
As companies plan capital allocation and commercial strategy for 2026, a clear, pragmatic understanding of the Isophorone market is essential. Our PW Consulting Isophorone Market study (base year 2025; historical coverage 2020–2025; forecast 2026–2032) shows a market that is recovering and re‑positioning itself around feedstock dynamics, regulatory pressure, and concentrated supplier power. The market reached approximately USD 1,420 Million in 2025 and, under our central-case assumptions, expands at a compound annual growth rate (CAGR) of about 5.2% through the forecast window — culminating in a projected market size north of USD 2,000 Million by 2032.
Isophorone (CAS 78-59-1) Market
This intelligence note synthesizes the research’s strategic value for 2026 decision‑makers. It highlights the dynamics that will determine margin trajectories, supply security and competitive moves, and it outlines the practical deliverables inside the full report that procurement, corporate strategy, and business unit leaders will find immediately usable.
Isophorone (CAS 78-59-1) Market
Market dynamics: cost, compliance and the new supply calculus
- Feedstock volatility governs margins. Isophorone producers remain sensitive to acetone availability and pricing. Recent market checks show acetone trading materially differently by geography — a factor that shapes regional cost curves and export flows. Crude oil volatility further propagates through acetone markets, creating intermittent cost dislocations that reward nimble procurement and integrated producers.
- Regulatory uplift is a structural margin pressure. Tighter EU environmental controls have increased capex and operating costs for producers in-region, while workplace exposure limits impose additional handling and engineering controls. For example, occupational exposure guidance sets a conservative 8‑hour TWA at 25 ppm, raising compliance costs for formulators and producers facing tightened monitoring and mitigation requirements.
- Supply concentration amplifies commercial risk and opportunity. The market exhibits a high degree of concentration, with leading suppliers commanding a substantial share of capacity. This oligopolistic structure translates into differentiated negotiating positions: integrated producers can leverage upstream integration to smooth cost swings, while smaller suppliers must compete on niche grades, service, and flexibility.
Demand drivers and structural shifts
- End‑use transition toward specialty formulations. Demand growth is being driven more by formulations that require higher‑purity, specialty‑grade isophorone and derivative intermediates than by commodity displacement. This benefits suppliers with quality control and specialty chemistries capabilities.
- Functional substitution and sustainability trends. Across coatings, adhesives and inks, buyers are increasingly weighing solvent selection against VOC regulation, lifecycle emissions and end‑product performance. The result is a bifurcation: premium pockets that favor specialty isophorone grades and cost‑sensitive segments that test alternatives.
- Geographic demand rebalancing. While historical demand footprints remain visible, incremental growth is concentrated in regions with strong construction, industrial paint and adhesive markets. Regional competitiveness will hinge on local feedstock costs, producer footprints and regulatory regimes.
Competitive landscape: practical takeaways
The competitive configuration is characterized by a handful of established integrated players and a broader set of regional suppliers and specialty producers. Key players profiled in the report include:
Isophorone (CAS 78-59-1) Market
- Arkema Group (France) — Positioned as a specialty oxygenated solvent and intermediate supplier; benefits from downstream integration into IPDA/IPDI and coatings chemistries. Strategic strength: technical service and product stewardship for high‑value formulations.
- Evonik Industries AG (Germany) — Operates integrated production at multiple sites and captures margin by linking isophorone with downstream diamines and epoxy systems. Strategic strength: scale, reliability and access to engineering polymers markets.
- Chemical Bull Pvt. Ltd. (India) — A regional manufacturer focused on high‑purity grades for paints, adhesives and chemical synthesis. Strategic strength: cost‑competitive supply to local formulators and flexibility on volumes.
- Somu Chemicals and Pharmaceuticals P Ltd (India) — Export‑oriented producer supplying isophorone as a fine‑chemical intermediate. Strategic strength: niche specialty grades for agrochem and pharmaceutical intermediates.
- SI Group Inc. (USA) — Supplies specialty isophorone to North American formulators; emphasizes formulation support and logistics. Strategic strength: customer intimacy and distribution reach.
- Jiangsu Huanxin High‑tech Materials Co., Ltd. (China) — Manufactures isophorone along with related intermediates, supporting local agrochemical and specialty chemical value chains. Strategic strength: local downstream integration and export orientation.
- Prasol Chemicals Pvt Ltd (India) — Targets industrial applications with an emphasis on coatings and adhesives. Strategic strength: tailored commercial terms and regional availability.
Across this set, differentiation rests on integration (upstream acetone access and downstream IPDA/IPDI derivatives), specialty grade capability, regulatory compliance expertise and global logistics. The report provides a supplier matrix that scores these attributes to support sourcing and M&A prioritization.
What the full report provides (practical, action‑oriented deliverables)
- Verified market sizing (USD Million), historical trends (2020–2025) and a scenario‑based forecast (2026–2032) with sensitivity bands around feedstock price, regulatory tightening and end‑market demand.
- Quarterly price modelling templates and a cost‑curve toolkit that allow procurement teams to simulate margin outcomes under alternative acetone price trajectories and crude oil scenarios.
- Supply‑demand maps at plant level, capacity utilizations, and a risk matrix identifying single‑point failures and logistics chokepoints — presented as decision tables for continuity planning.
- Regulatory impact assessment and compliance playbook (including exposure limits, emissions controls and likely near‑term policy changes in key markets) to inform capex and operating cost forecasts.
- Commercial playbooks: go‑to‑market strategies for producers (premiumization, tolling, contract models) and procurement negotiation scripts for buyers facing concentrated suppliers.
- M&A and JV opportunity shortlist derived from strategic fit, technological capability and regional footprint — with acquisition red flags and integration checklists.
- Competitive benchmarking and supplier scorecards that rank firms by integration, quality, regulatory posture and service reliability — designed for immediate use in supplier selection and tendering.
Strategic recommendations for 2026 decision‑makers
- Lock in feedstock exposure and build flexible sourcing. Given the sensitivity to acetone pricing and crude oil volatility, buyers and producers should pursue a layered strategy: hedging for core volumes while contracting shorter, flexible supplies for opportunistic arbitrage.
- Invest in regulatory resilience. Firms with EHS‑focused capex will enjoy both compliance and commercial benefits. For producers targeting EU customers, early investment in emission controls and monitoring provides a competitive edge and reduces the risk of sudden operating constraints.
- Pursue specialty‑grade differentiation. With demand favoring higher‑value formulations, producers should prioritize quality upgrades, technical service and co‑development partnerships with formulators to capture margin uplift.
- Assess strategic integration. Downstream integration into diamine derivatives and other value‑added chemistries can insulate margins and create higher switching costs for customers — an essential consideration for long‑term capex.
- Prepare for consolidation opportunities. High market concentration means attractive bolt‑on targets will appear as regional players seek scale or exit non‑core segments. Use the report’s M&A shortlist and integration checklists to accelerate diligence.
- Operationalize scenario planning. Embed the report’s scenario tools into budget cycles to stress test pricing, margins and working capital under plausible feedstock and regulatory outcomes.
Why this matters for 2026
Decisions made in 2026 will determine which companies capture the next wave of value in Isophorone: those that secure resilient feedstock links, invest in regulatory preparedness, and offer differentiated specialty grades will outperform peers. The market’s projected expansion — driven by formulation evolution and steady end‑market demand — offers clear upside, but it sits atop a cost and compliance environment that will disproportionately reward strategic foresight and execution capability.
Accessing the full intelligence
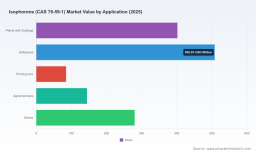
This briefing intentionally highlights the structural drivers, competitive dynamics and practical actions embedded in our Isophorone market study, while reserving the full regional and application breakdowns, plant‑level capacity tables, and proprietary price curves for the full report. If your 2026 strategy requires line‑by‑line demand tables, supplier scorecards, or the downloadable cost‑curve model, please refer to the complete PW Consulting publication for the underlying datasets and reproducible modelling assets.
For decision teams preparing budgets, supplier negotiations, or M&A screens in 2026, the full report functions as an immediate, operational tool — not just a forecast. It translates market intelligence into executable actions, reducing uncertainty where it matters most: procurement, capex, pricing and M&A timing.
For detailed analysis of this topic, please visit the official page: Isophorone (CAS 78-59-1) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com