

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Wine Cooler Refrigerator Market to Reach USD 210.38 Million by 2032

Wine Cooler Refrigerator Market — 2026 Strategic Preview
Introduction
As corporate leaders and investors plan for 2026, the Wine Cooler Refrigerator market presents a blend of steady demand, technological refresh, and regulatory urgency. This briefing — prepared by PW Consulting’s senior strategy team — distills the strategic implications of our full market study (base year 2025; historical window 2020–2025; forecast 2026–2032). Consider this a high-fidelity trailer: we surface the analytical spine and actionable conclusions that should drive boardroom priorities, while we intentionally withhold detailed segment-level tables and proprietary splits to encourage acquisition of the full report for execution-ready numbers and scenario models.
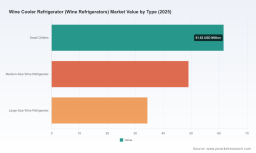
Wine Cooler Refrigerator (Wine Refrigerators) Market
Market snapshot and trajectory
The global market has moved from an estimated USD 120.0 Million in 2020 to approximately USD 145.0 Million in 2025, reflecting a resilient expansion through new-channel adoption and sustained premiumization in residential and hospitality applications. Under a base forecast, the market is projected to enter 2026 at roughly USD 153.0 Million and to grow at a compound annual growth rate (CAGR) of about 5.5% over the 2026–2032 horizon, reaching an expected USD 210.4 Million by 2032.
Wine Cooler Refrigerator (Wine Refrigerators) Market
That trajectory is neither a straight line nor evenly distributed across every product or geography. Growth is shaped by three convergent forces: (1) product innovation (dual/triple-zone control, panel-ready integration, smart connectivity), (2) regulatory change (refrigerant transitions and new distribution rules), and (3) channel evolution (online and specialty retail dynamics augmenting traditional OEM-dominated pathways). Our report quantifies these drivers and translates them into specific revenue and margin scenarios for manufacturers, channel partners, and investors.
Wine Cooler Refrigerator (Wine Refrigerators) Market
Why this matters for 2026 decision-makers
- Strategic timing: With the market on a steady mid-single-digit CAGR, 2026 is a year to convert R&D and compliance investments into commercial advantage rather than merely defend share. Early compliance with new refrigerant rules and differentiated premium features will capture higher-margin demand.
- Portfolio prioritization: The premium built-in and panel-ready segments are where feature-led differentiation (Ambra/Obsidian lighting, vibration control, UV protection) translates into pricing power. Yet volume play and entry-level innovation remain relevant for rapid category expansion in emerging channels.
- Regulatory risk as a strategic lens: Mandatory transitions to natural refrigerants and evolving distribution law provisions create winners (those with rapid retrofit or next-gen product roadmaps) and losers (those with long, inflexible manufacturing runs). Timing and capital allocation are key.
- Concentration and competition: Market concentration metrics indicate a moderately fragmented competitive structure — large brands anchor premium trust, while agile innovators capture niche segments. M&A and strategic partnerships will be a high-return lever to consolidate technology and channel access.
Competitive landscape — what the leaders are doing
Our competitive analysis benchmarks product, channel, and capability moves from established appliance groups and specialist brands. Key observations:
- JennAir and Whirlpool (brand umbrella) — Positioning: premium built-in columns and bespoke panel-ready systems with strong lighting and finish differentiation. Strategic move: leveraging brand-led kitchen integration to command showroom attention and higher ASPs (recent product launch at KBIS 2026 underscores premium push).
- Liebherr — Positioning: engineering-led preservation with multi-zone control, advanced UV and vibration protections, and smart integrations. Strategic move: design awards and product breadth support both commercial and collector-grade demand.
- Summit Appliance — Positioning: practical full-height and undercounter solutions optimized for shallow-depth installations and dual-use (residential/commercial). Strategic move: targeted product launches to capture retrofit and small-venue installs.
- SMEG and EuroCave — Positioning: design- and heritage-driven luxury offerings that appeal to premium residential and hospitality buyers. Strategic move: expanding capacities and Italian design cues to sustain aspirational pricing.
- U-Line, Danby, Allavino, NewAir — Positioning: channel-led propositions (under-counter, seamless integration, flexible shelving) focused on balancing price and function to serve mass and specialty channels.
- Miele and other appliance incumbents — Positioning: integrated kitchen ecosystems with app control and high-spec mechanical features. Strategic move: panel-ready products that align with smart-home narratives and premium kitchens.
Recent product activity confirms these strategic postures: JennAir’s new panel-ready column (KBIS 2026), Summit’s shallow-depth cellar (July 2025), SMEG’s next-gen under-counter launch (June 2026), Miele’s updated panel-ready under-counter model (October 2025), and recognition of Liebherr’s design excellence (Red Dot 2025). These moves are measurable signals that incumbents are accelerating product refresh cycles and positioning for regulatory transitions.
Regulatory and trade context shaping 2026 strategy
- F-gas regulation (EU 2024/573): The ban on synthetic F-gases in domestic refrigeration by 2026 compels a rapid move to natural refrigerants (R290, R600a). Manufacturers must validate safety (A2L flammability considerations), redesign compressors and charge sizes, and secure compliant supply chains. Companies that pre-validated systems will enjoy time-to-market advantage in EU and spillover global markets.
- Distribution law proposals (e.g., Wine Cooler Fair Dealing Act) and competition authority scrutiny: Proposed requirements for written territory agreements influence channel economics and aftermarket support. Brands must re-evaluate distributor contracts, territorial strategies, and direct-to-consumer ambitions.
- Trade and tax frictions: Country-specific VAT and alcohol excise rules (Mexico cited as an example) create import cost differentials that affect pricing strategy for cross-border retail and hospitality chains. Packaging and ad valorem levies further complicate landed cost assumptions.
- Input-cost volatility: Raw material and labor cost swings will disproportionately hit premium builds if global sourcing is rigid. Strategic nearshoring, modular designs, and flexible BOMs are risk mitigants.
What the full report delivers — an operator’s toolkit
Our published study is designed for immediate operational use. The package includes:
- Validated market sizing (2020–2025 historical, 2026–2032 forecast) with alternative scenarios (base, upside, downside) and sensitivity to refrigerant adoption timelines.
- Competitive scorecards for the leading suppliers, mapping product capabilities, channel footprint, margin proxies, and integration readiness.
- Go-to-market playbooks: route-to-market matrices for direct, distributor, retail, and omnichannel models, with prioritized actions per channel for 90/180/360-day horizons.
- Regulatory readiness checklist and refrigerant transition roadmap (technical, safety, certification, and capex timelines) that translate compliance into competitive differentiation.
- Unit economics and pricing ladders, including modeled impacts of taxes, tariffs, and packaging levies on landed cost and recommended MSRP strategies.
- Supply chain resilience and sourcing playbooks, including recommended nearshoring approaches, vendor scorecards, and inventory optimization levers to protect margins under material price volatility.
- M&A and partnership scanner: prioritized OEM, component, and distribution targets with rationale grounded in capability gaps and market concentration analysis.
Note: as a teaser, we do not publish granular region/application splits or proprietary segment tables in this preview. These are available only in the full report and are essential for execution-level planning (pricing, SKU rationalization, and channel mix optimization).
90/180/360-day action map for executive teams
- 0–90 days: Complete a refrigerant readiness audit (design, supplier, certification). Freeze SKU rationalization candidates and launch a premium-feature marketing pilot in top showroom channels. Re-negotiate critical distributor clauses with legal teams to anticipate territorial requirement changes.
- 90–180 days: Validate prototype natural-refrigerant units with third-party safety labs. Implement targeted channel pilots (specialty retail + DTC) using differentiated feature bundles. Initiate supplier dual-sourcing for compressors and control electronics to mitigate lead-time risk.
- 180–360 days: Scale compliant product lines into prioritized markets, roll out service and warranty adaptations for new refrigerant profiles, and deploy a pricing cadence informed by taxed-impacted landed-cost models. Evaluate tuck-in acquisitions to secure shelving technology, app capabilities, or local assembly.
How PW Consulting’s study de-risks execution
We translate market intelligence into decision-ready outputs. Clients who use our study gain:
- A short-list of prioritized product and channel bets aligned to 2026 regulatory pivots and consumer willingness-to-pay.
- Operational timelines and costed implementation plans to manage refrigerant transitions without sacrificing launch cadence.
- Evidence-based targets for M&A and partnership dialogues to rapidly augment engineering, distribution, or brand capability.
- Actionable price & margin models that incorporate local taxes, packaging levies, and trade frictions to support confident list price and rebate decisions.
Conclusion — the strategic choice for 2026
2026 will be a year where compliance, speed-to-market, and feature differentiation determine market leaders. The underlying demand trajectory (mid-single-digit CAGR to 2032) creates a stable growth backdrop, but the win will go to organizations that convert regulatory compliance into a commercial story — safe, efficient, and premium-preserving. PW Consulting’s full Wine Cooler Refrigerator report converts the market-wide trajectory and competitor dynamics summarized here into executable plays, risk-calibrated budgets, and M&A targets. For the detailed regional and application intelligence, proprietary segment splits, and the models you need to operationalize your 2026 plan, access the full report on our website or contact our specialist team.
For detailed analysis of this topic, please visit the official page: Wine Cooler Refrigerator (Wine Refrigerators) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com