

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Autoclave Market to Reach USD 499 Million by 2032 at 5.25% CAGR

Autoclave Market 2026 — Strategic Preview for Decision Makers
Executive teaser
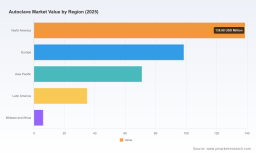
As healthcare, pharmaceutical manufacturing, and research infrastructures converge on resilient sterilization strategies, the autoclave market has quietly evolved from a commoditized supply line into a strategic investment class. PW Consulting’s latest Autoclave Market study (base year 2025; forecast 2026–2032) shows a steady multi-year expansion driven by capital refresh cycles, regulatory shifts, and technology adoption. The market — sized at roughly USD 349 million in 2025 — is projected to approach roughly USD 499 million by 2032, implying a compound annual growth trajectory in the mid-single digits (CAGR ~5.25%).
Autoclave Market
Why 2026 is a strategic inflection point
Fiscal 2026 presents a compressed decision window for procurement and strategy teams. On the supply side, manufacturers and service providers are introducing smarter controls, remote monitoring stacks, and purpose-built GMP platforms. On the demand side, regulatory activity and supply-chain resiliency conversations are forcing buyers to rethink sterilization mixes and capacity footprints. Our research identifies 2026 as the year when tactical replacement projects and medium-term capital programs must internalize both emerging standards and potential constraints around specific sterilization chemistries.
Autoclave Market
Core dynamics shaping near-term strategy
- Regulatory re‑pricing of risk: Recent regulatory developments have intensified scrutiny on certain low-temperature sterilants and facility emissions. Proposed amendments to national emissions standards for commercial sterilization facilities and recent policy-level relief measures both change timing and capital priorities for operators who rely on specific chemistries. Buyers planning installations in 2026 should factor regulatory tail-risk into equipment life-cycle models.
- Standards and technology substitution: Recognition of updated international standards for vaporized hydrogen peroxide processes signals an accelerating pathway for alternatives to legacy sterilants in defined use-cases. Where equivalence and validation are achievable, demand for validated low‑temperature autoclave platforms and integrated validation services is rising.
- Services as differentiation: Competition is shifting from hardware features to outcome-based offerings — faster validation support, digital predictive maintenance, spare-parts logistics, and on-site qualification. Vendors with field services and validation labs now influence procurement decisions as strongly as product spec sheets.
- Cost-pressure and supply diversification: Competitive pressure from lower-cost OEMs is accelerating in certain segments, pressuring legacy vendors to accentuate reliability, back-end services, and total cost of ownership analyses rather than competing on initial capex alone.
What this means for 2026 enterprise decisions
For capital planners, clinical operations leaders, and manufacturing heads, the immediate implications are tactical and strategic. Tactically, short-cycle replacement programs should prioritize equipment with robust digital telemetry and vendor‑assisted validation packages to reduce throughput downtime during commissioning. Strategically, organizations must adopt scenario-based procurement: value modularity (to permit chemistry changes), require vendor certification pathways for alternate sterilization methods, and quantify supply-chain concentration risk for sterilant-dependent SKUs.
Autoclave Market
Actionable recommendations (practical, prioritized)
- 12‑month actions: Conduct an EtO-reliance audit for products and suppliers; map which SKUs are single‑sourced for sterilization and simulate shorter and longer disruption scenarios. Immediately require any capital RFQ to include validation support, remote monitoring capability, and documented energy/water performance metrics.
- 18–36 month actions: Pursue modular autoclave platforms that enable cross-chemistry validation and minimize site civil works. Negotiate service-level agreements that align uptime targets with clinical throughput and include parts availability guarantees.
- M&A and partnership focus: Evaluate bolt-on acquisitions of niche validation consultancies, regional aftermarket service networks, and data‑analytics providers that can convert operational telemetry into warranty and maintenance revenue.
Competitive landscape — what to expect from vendors
The market remains contestable: established European and North American OEMs compete with specialized domestic manufacturers and cost-competitive suppliers from Asia. Differentiation increasingly rests on validated application focus, service coverage, and software-enabled workflows rather than raw chamber volume or nominal cycle time.
- Tuttnauer (Israel) — Continuing to push economical laboratory lines bundled with connected software for remote monitoring and workflow optimization. Expect emphasis on retrofit-friendly solutions and transparent remote diagnostics.
- Priorclave (UK) — Doubling down on programmable, durable platforms for research and education customers where lifecycle reliability and local support justify premium positioning.
- Fedegari Group (Italy) — Maintaining leadership in pharmaceutical-grade GMP sterilization with focused investments in process safety and sustainability projects, plus collaborations that accelerate qualification workflows for complex assemblies.
- Systec (Germany) — Strengthening laboratory and biotech user propositions with certified, tightly-engineered systems and an emphasis on compliance with quality standards.
- Regional and cost-competitive players — Providers from Asia, along with legacy North American manufacturers, are intensifying pressure on price-sensitive channels while expanding warranties and installation services to close capability gaps.
Recent vendor moves to watch
- Pharma-focused project commitments and validation partnerships are proliferating as suppliers invest in on‑site capability centers for pre‑commissioning support.
- Vendors are publishing direct comparisons to cheaper alternatives; procurement teams should take supplier benchmark claims as starting points for independent validation rather than final evidence.
- Product announcements emphasize software connectivity and remote fleet management as a central procurement criterion in 2026 RFPs.
Research scope and practical content included in the full report
PW Consulting’s full study is crafted to support executable decisions in 2026. Deliverables include: a robust market-sizing model (historical 2020–2025 and base year 2025 benchmarking), a 2026–2032 quantitative forecast scenario suite, vendor scorecards, technology and standards impact matrices, capital budgeting templates, total cost of ownership calculators, a regulatory impact playbook, and a prioritized roadmap for service expansion and M&A targets. The report also offers proprietary supplier negotiation scripts and checklist templates for validation and commissioning that materially reduce time-to‑compliance for new installations.
How to use the report in boardroom and procurement cycles
- Present the forecast scenarios as inputs to capital allocation debates and risk registers — don’t treat the mid‑case as immutable; stress‑test decisions against tighter regulatory scenarios.
- Leverage vendor scorecards during shortlisting to convert feature comparisons into operational KPIs (uptime targets, mean time to repair, parts availability, and validation turnaround time).
- Use the TCO calculators during vendor negotiations to shift conversations from headline price to lifecycle value, particularly where service differentiation is uneven across bids.
Final takeaways
The autoclave market in 2026 is simultaneously mature and dynamic. Market expansion is steady and investable, but the greatest value accrues to organizations that convert technology and regulatory insight into procurement and operational advantage. Vendors that pair dependable equipment with validation expertise, digital monitoring, and resilient aftermarket networks will capture disproportionate share of new spend. For buyers, the mandate is clear: treat sterilization platforms not as one-off capex items but as long-lived nodes in a regulated, safety-critical supply chain — then structure contracts, services, and contingency plans accordingly.
Next steps
PW Consulting’s full Autoclave Market report contains the detailed, proprietary datasets and vendor evaluations that underpin the conclusions summarized here. For teams preparing 2026 capital plans, supply-chain mitigations, or M&A plays, the full study delivers the granular inputs and templates required to move from strategy to execution. Contact our advisory desk to arrange a briefing or obtain access to the dataset and tailored scenario runs.
For detailed analysis of this topic, please visit the official page: Autoclave Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com