

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Montmorillonite (Bentonites) Market to Reach USD 2,958 Million by 2032 at 5.5% CAGR

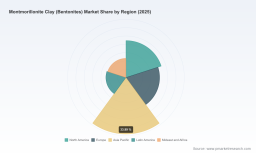
Montmorillonite Clay (Bentonites) Market — Strategic Outlook to 2032
This strategic brief introduces PW Consulting’s latest Montmorillonite Clay (Bentonites) Market study (base year 2025; historical window 2020–2025; forecast 2026–2032). The study maps the commercial terrain for executives who must make high-stakes sourcing, investment, and portfolio choices during 2026. Our market model shows a continuation of steady expansion: the global market increased from around USD 1.6 billion in 2020 to approximately USD 2.05 billion in 2025, and, under the central scenario, is expected to reach the low‑to‑mid USD 2.9 billion range by 2032 — a compound annual growth rate of 5.5% across the forecast horizon. This paper highlights the strategic implications of those dynamics and outlines the decision levers that will matter most in 2026, while intentionally withholding core segment-level figures to direct decision-makers to the full report for transactional use.
Montmorillonite Clay (Bentonites) Market
Why this study matters for 2026 decision-makers
- Supply security trumps short-term price plays. The industry remains resource- and logistics-sensitive: established deposits, permitting timelines, and export corridors determine operational continuity. Buyers and processors need multi-vector sourcing and longer-term contracts to avoid supply shocks.
- Product mix will drive margin separation. Commodity bentonites will continue to face pricing pressure; premium and engineered montmorillonite derivatives (organoclays, specialty adsorbents, remediation grades) are where value accrues. Strategic OEM and formulation partnerships are decisive.
- Regulation and national strategy reshape risk calculus. Newer public policies and critical-minerals designations demand proactive compliance and supply-chain mapping — not after-the-fact remediation.
- Mid-cap consolidation opportunity. Market concentration sits at a level that allows disciplined M&A to create scale without triggering dominant‑player scrutiny; selective acquisitions can be both defensible and value‑accretive.
Macro and market dynamics to watch in 2026
The fundamentals are straightforward: demand growth is steady — driven by a blend of industrial applications, construction and environmental sealing needs, and evolving demand from remediation and specialty markets. Supply-side features amplify the strategic importance of sourcing and near-term capital allocation.
Montmorillonite Clay (Bentonites) Market
- Export flows and trade dependencies. In 2025, U.S. exports of bentonite were estimated at roughly 640,000 tonnes, with a few established trading partners absorbing meaningful volumes. Companies exposed to North American supply should explicitly model export corridor disruptions and tariffs in 2026 scenarios.
- Tax and depletion policy as a supply lever. Bentonite continues to benefit from a depletion allowance in the U.S. tax code (recognized at a 14% rate), a powerful incentive that shapes domestic mine economics and investment timing.
- Strategic minerals and geopolitical framing. Bentonite’s inclusion on the 2025 U.S. Critical Minerals List elevates the mineral from an operational commodity to an element of national supply-chain strategy — increasing regulatory oversight, potential funding for domestic processing, and procurement preferences for secure suppliers.
- End-market transitions. Legacy demand from oil and gas (drilling muds) is now balanced by growth in environmental sealing, remediation technologies, construction waterproofing, and consumer uses. This shift reduces single-market cyclicality but raises product-specification complexity.
Competitive landscape — who shapes the market and how
The competitive field blends large, integrated miners with specialty chemical processors and regional producers. The market is moderately concentrated (top‑three players control a meaningful minority share while the top‑five widen that footprint), leaving room for both scale advantages and nimble specialty plays.
Montmorillonite Clay (Bentonites) Market
- Wyo-Ben Inc. (Billings, Montana, USA) — A legacy Wyoming producer with vertical capabilities in mining and basic processing. Their position in Big Horn Basin deposits and long-term customer relationships make them a natural counterparty for industrial buyers seeking continuity.
- Imerys S.A. (Paris, France) — A global supplier with broad materials science capability. Imerys competes on application engineering and multi-site logistics, offering customers access to formulation know‑how and a global footprint.
- Black Hills Bentonite LLC (Casper, Wyoming, USA) — Another Wyoming-origin supplier with a reputation for material consistency. Their model emphasizes reliable physical properties for industrial users.
- Minerals Technologies Inc. (New York, USA) — Operator of established brands in environmental and remediation segments. Their focus on montmorillonite-based remediation products (including PFAS-related solutions) showcases a profitable route to differentiated end markets.
- Clariant AG (Muttenz, Switzerland) — A specialty chemical processor that converts raw clays into higher-margin adsorbents and additives; their strength lies in process chemistry and multi-industry distribution channels.
- Ashapura Group (Mumbai, India) — A cost-competitive supplier and exporter with expanding capacity. Their presence underscores the interplay between low-cost production and regional demand growth.
- Bentonite Performance Minerals LLC (Belle Fourche, South Dakota, USA) — An integrated player producing a range of specialty bentonites and organoclays; integration across mining, processing, and compound production is a clear margin mobilizer.
For 2026 strategy, two competitive themes matter most: (1) the ability to tie raw-material security to downstream contractual demand, and (2) investing in capability to deliver engineered montmorillonite solutions rather than commodity sacks. Companies that combine reliable feedstock access with application engineering will realize superior returns.
What the full report delivers — practical, transaction-ready tools
Our research is designed to be immediately actionable for corporate strategy, procurement, and corporate development teams. The full study includes:
- Integrated market sizing and a validated model (historical 2020–2025; base year 2025; forecast 2026–2032), with scenario outputs and sensitivity testing calibrated to commodity-price and capacity-shock events.
- Segmented demand analysis by geography, grade/type, and application — with elasticities, seasonal cycles, and growth vectors mapped for prioritization.
- Trade-flow matrices and logistics-cost build-ups that expose real landed costs into major consumption hubs.
- Company profiles and benchmarking (including plant-level capacities, core competencies, and go-to-market models) for the major producers and specialty processors.
- Regulatory and policy impact assessments — including critical-minerals implications, tax/depletion policy, permitting timelines, and environmental/ESG constraints — with mitigation checklists.
- Investment and M&A playbooks: target screening criteria, valuation multiples observed, integration checklists, and post-deal synergies quantified.
- Commercial templates for procurement: sample long‑term off-take contract clauses, inventory-buffer guidelines, and commercial hedging strategies for price and FX exposure.
- Practical case studies and decision trees for moving from commodity to specialty product strategies, including CapEx and R&D roadmaps for upgrading clay into value-added montmorillonite derivatives.
Note: This preview intentionally omits the granular segment allocations and regional/application dollar breakdowns — those datasets are central to commercial execution and are provided exclusively in the full report.
Priority actions for executives in 2026
- Lock supply, in multiple forms. Secure tiered agreements (short‑term spot allowances, medium-term fixed-volume contracts, and strategic equity in mines or processing) to balance flexibility and security.
- Re‑profile portfolios. Move R&D and commercial focus toward engineered and remediation products that command higher margins and less cyclicality than pure drilling mud grades.
- De-risk geopolitically. Map single-source dependencies and create alternative sourcing lanes where feasible, particularly given export concentration and critical-minerals policy shifts.
- Invest in downstream capabilities. Vertical integration into compounding, modification, and adsorption technology can capture margin and reduce exposure to raw-material price swings.
- Make compliance a differentiator. Use regulatory and ESG compliance (traceability, low‑impact mining certifications, PFAS testing protocols) as commercial differentiators in contract negotiations.
- Prioritize capital projects with short payback. Brownfield processing upgrades, moderate-scale drying and milling assets, and modest R&D lines for specialty grades typically pay back faster than greenfield mining projects.
Risks and leading indicators
Key downside risks include abrupt trade disruptions, accelerated depletion or permitting delays at major deposits, and a sharper-than-expected contraction in legacy oil-and-gas demand in certain regions. Conversely, accelerated regulatory demand for engineered sealing and remediation materials, and faster adoption of montmorillonite-based PFAS remediation solutions, could materially lift the upside case.
Leading indicators to monitor weekly-to-quarterly in 2026: export tonnages from major producing jurisdictions, spot and term price spreads between standard and treated grades, freight-rate and container availability into core consuming hubs, and regulatory announcements tied to critical-minerals policy or environmental standards.
Conclusion — how to use this briefing
This preview is a strategic map, not a tactical playbook. It demonstrates the analytical framing and practical orientation of PW Consulting’s full Montmorillonite Clay (Bentonites) Market report while intentionally withholding the specific segment allocations and regional/application dollar breakdowns that commercial teams need to transact. For procurement teams, corp dev, and product leaders preparing binding commitments in 2026, the full dataset, scenario modules, and contract templates are indispensable.
Contact PW Consulting to obtain the full report and data package that includes the segmented market model, company benchmarking spreadsheets, supply-chain maps, and the transaction toolkits required to execute with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Montmorillonite Clay (Bentonites) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com