

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: XRD Market Set for 6.5% CAGR (2026-2032)

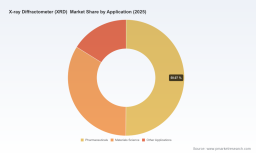
X-ray Diffractometer (XRD) Market 2026: Strategic Preview for Executive Decision‑Making
Executive snapshot
As PW Consulting’s lead industry analyst, I present a focused strategic preview of our new X-ray Diffractometer (XRD) Market study — a decision‑grade briefing targeted at corporate strategy teams, M&A desks, product leaders and R&D procurement planners preparing plans for 2026. This preview synthesizes the macro trajectory, competitive structure, and near‑term dynamics that will matter to buyers and sellers in the coming 12–24 months, while preserving the proprietary segment-level detail reserved for subscribers of the full report.
X-ray Diffractometer (XRD) Market
Why this research matters for 2026 decisions
-
Actionable timing. The XRD market is moving from steady recovery into a new phase of investment as firms reshape laboratory footprints and industrial metrology lines. Strategic moves made in 2026 — capital allocations, channel realignments, and portfolio pruning — will capture the compounding value created through the forecast window.
X-ray Diffractometer (XRD) Market -
Resource prioritization. Our analysis translates technology trends and regulatory pressures into prioritized investment levers: which product platforms deserve R&D scale, where service and consumables margins will expand, and how aftermarket services will offset capital‑goods cyclicality.
X-ray Diffractometer (XRD) Market -
Risk calibration. With supply chain volatility, tariff regimes and localized regulatory reporting requirements in play, 2026 will be a year of elevated operational risk. The study frames mitigation pathways — sourcing dualization, regional service hubs, and compliance playbooks — that materially reduce downside.
Market trajectory: what the headline numbers tell you
We track the global XRD market across a robust historical window (2020–2025, base year 2025) and extend the forecast to 2032. The market scaled from a lower base in 2020 through a period of steady recovery and investment, reaching a substantive footprint in our base year. Our modeling shows a compound annual growth rate (CAGR) of 6.5% across the forecast period (2026–2032), driven by renewals in academic capital spending, rising industrial metrology demand, and incremental adoption of compact benchtop systems in quality control environments.
To put the pace in perspective: the market shows a persistent upward trend from 2020 through the base year and continues to expand under our forecast assumptions toward the end of the decade. This pace supports mid‑cycle strategic plays such as selective capacity upgrades, targeted bolt‑on acquisitions for capability gaps, and staged rollouts of software‑enabled lifecycle services.
What the full study contains (practical, operational, non‑obvious)
-
Proprietary market model: a granular, bottoms‑up revenue model that reconciles equipment sales, service & spare parts, and software monetization across our historical window and forecast period. The model is built for scenario testing (sensitivity to supply constraints, tariff shifts, and academic funding shocks).
-
Segmentation playbooks: revenue and adoption profiles across product families, instrument classes and application verticals. (Note: detailed segment figures are withheld in this preview to preserve the report’s subscriber value; the full report provides downloadable model sheets and segmented growth drivers.)
-
Technology adoption matrices: practical maps that link instrument attributes (resolution, footprint, throughput) to buyer personas (university labs, pharma QC, semiconductor fabs, materials R&D) and procurement timetables.
-
Commercial strategy templates: go‑to‑market options for incumbents and challengers — from premium instrumentation and service bundles to low‑capex, subscription‑style access for industrial QC customers.
-
Regulatory & compliance playbooks: checklists and reporting pathways for regions where radiation‑safety incident reporting and export control considerations materially affect product design, deployment timelines and warranty offerings.
Competitive landscape — concentration, platforms and positioning
The XRD market remains moderately consolidated at the top; our concentration metrics indicate a modest share captured by the largest players, leaving room for specialist entrants and regional champions to exploit niche advantages. Leadership today is a mix of large analytical instrumentation incumbents and specialized equipment manufacturers that combine platform breadth with focused engineering depth.
-
Malvern Panalytical (France): recognized for a portfolio that spans compact benchtop instruments to multipurpose R&D platforms. Their Aeris and Empyrean lines exemplify a tiered approach — compact, modular and scalable offerings that appeal across QC and research workflows.
-
Bruker AXS SE (Germany): a historically strong player with modular families and industrialized powder systems. Their product strategy emphasizes configurability to serve both R&D and production environments, and their regulatory disclosures underline the operational requirements tied to radiation safety and related reporting.
-
Proto Manufacturing (Canada): a specialty supplier that competes on customization, residual stress measurement, and single‑crystal/metrology capability. Their engineering focus supports niche, high‑value applications and bespoke systems.
-
Rigaku (Japan): differentiated by offerings that bridge polycrystalline characterization and semiconductor metrology. Rigaku’s product set is positioned where crystallography and high‑throughput industrial measurement intersect.
-
Anton Paar (Austria): brings high‑precision measurement DNA into XRD, emphasizing crystal structure determination and phase analysis across research and industrial lab contexts.
-
LINEV Systems (Lithuania): a competitive benchtop player targeting analytical research and QC markets with compact footprint systems optimized for speed and ease of use.
For decision makers, the implication is clear: market entry or expansion should be driven by a defensible angle — either technical differentiation (resolution, throughput, or specialty measurement modes), service density (regional calibration, rapid spares), or cost‑to‑serve efficiency enabled by instrument modularization.
Recent developments and industry touchpoints
-
Industry education and community events remain important vectors for adoption: 2026 saw renewed educational programming from the International Centre for Diffraction Data (ICDD) and focused XRD sessions at the Denver X‑ray Conference. These forums accelerate best‑practice adoption and are fertile environments for product validation and lead generation.
-
Manufacturers continue to announce new compact and industrial systems; these product introductions, paired with upgrades to detector and software stacks, are shifting purchase criteria toward lifecycle value rather than upfront hardware capability alone.
Market dynamics that will shape 2026 strategies
-
Supply chain and labor cost pressures. Recent disclosures from major vendors underscore ongoing inventory and lead‑time challenges that add execution risk and margin pressure. Companies with diversified sourcing, localized assembly or stronger forecasting discipline will sustain delivery performance and protect margins.
-
Geopolitics and tariffs. Evolving tariff landscapes and export controls introduce execution friction across global sales and service operations. Strategic responses include regional service hubs, flexible pricing frameworks and legal‑compliance investments in product design and documentation.
-
Regulatory oversight and reporting. Radiation‑safety incident reporting obligations in certain jurisdictions create additional post‑market surveillance and documentation costs. Vendors should bake compliance into warranty, service level agreements and training offerings to reduce downstream liabilities and strengthen buyer confidence.
-
Funding variability in academic research. Given the sizeable role of academia in R&D purchases, volatility in research budgets can create cyclical demand. Diversifying into industrial QC, pharmaceutical quality systems and semiconductor metrology can smooth revenue streams.
Strategic plays for 2026
-
Prioritize service and software monetization. With hardware cycles long, aftermarket service contracts, software upgrades and data‑analysis subscriptions are the most reliable immediate lever to grow recurring revenue.
-
Design for modularity. Lowering the cost and complexity of field upgrades (detector swaps, software features) reduces total cost of ownership for buyers and shortens sales cycles for vendors.
-
Hedge supply risk. Establish dual suppliers for critical components, pre‑position key spares in target regions, and build transparent customer communications to maintain trust through disruptions.
-
Targeted M&A and partnerships. Look for bolt‑ons that extend service coverage, add specialty measurement capability, or provide software analytics that can be cross‑sold into installed bases.
-
Channel segmentation. Differentiate GTM strategies between high‑touch R&D customers (requiring demo instrumentation and training) and volume industrial QC accounts (requiring leaner procurement processes and faster onboarding).
How PW Consulting can help
Our full XRD Market study delivers the detailed segmentation, downloadable financial model, and playbooks referenced above. For teams planning 2026 capital and commercial moves, we offer tailored workshops: scenario stress‑testing of procurement plans, go‑to‑market blueprints for new instrument launches, and M&A diligence focused on manufacturing fit and service economics.
Next steps — where to access the full intelligence
This preview intentionally omits the granular regional and application splits and the full set of segment‑level forecasts to preserve the catalytic value of the complete report. For access to the full report, model files and a briefing with our XRD practice leads, please follow the PW Consulting subscription channel. We recommend booking an executive briefing in Q1–Q2 2026 to align capital plans with the market inflection windows we model.
Prepared by: PW Consulting — Senior Strategic Advisor & Chief Industry Analyst, XRD and Materials Metrology Practice. Base year and model horizons: historical 2020–2025 (base year 2025); forecast period 2026–2032. Headline CAGR (2026–2032): 6.5%. Currency unit: Million USD.
For detailed analysis of this topic, please visit the official page: X-ray Diffractometer (XRD) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com