

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Citral Market Poised for 6.8% CAGR in 2026–2032 Outlook

Citral Market 2026: Strategic Imperatives from PW Consulting
Executive snapshot
Citral occupies a pivotal position at the intersection of flavors, fragrances, and specialty chemistry. Our Citral Market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — shows the market expanding from roughly USD 800 million in 2020 to about USD 1,070 million in 2025, with a compound annual growth rate of 6.8% projected through the forecast period. By 2032 our base-case scenario anticipates the market approaching the mid‑to‑high‑thirteen‑hundred million USD range, driven by a mix of formulation demand, industrial ingredient substitution, and capacity investments across Asia, Europe and North America.
Citral Market
Why this matters for decision-makers in 2026
-
Supply-side tension is the defining short-term variable. Natural citral remains constrained by feedstock realities — low extraction yields from lemongrass and citrus peel under conventional methods, volatile citrus oil pricing, and concentrated natural production volumes. Technological improvements such as supercritical CO2 extraction are improving yields, but synthetic routes continue to dominate on scale and cost.
Citral Market -
Regulation is moving from background risk to active program management. IFRA’s incorporation of maximum citral concentrations into the EU cosmetic framework in late May 2026 widens the scope for compliance-related SKU reformulation, labelling changes, and potential product down‑trading where reformulation is not viable.
Citral Market -
Industry structure is moderately concentrated: the market is shaped by a small set of global specialty players and a broader cohort of regional producers and distributors. This topology creates differentiated negotiating leverage across procurement, particularly where preferred suppliers combine upstream feedstock access with downstream formulation capabilities.
-
Capacity trajectories are re‑shaping sourcing geographies. Recent world‑scale projects (notably major new plants commissioned in China and significant expansions by leading fragrance ingredient manufacturers) are altering trade flows and creating near-term oversupply risks in certain product grades while tightening supply for high-purity, natural‑label grades.
How market dynamics translate into strategic choices
Companies face a classic set of trade-offs in 2026: secure supply versus control cost; prioritize natural differentiation versus exploit synthetic scale; and accelerate compliance readiness versus defend existing formulations. These choices should be made against four interlinked dynamics:
-
Procurement and inventory strategy — adopt a blended sourcing portfolio that balances long‑term contracts with a network of regional spot suppliers to absorb feedstock volatility.
-
Product and R&D strategy — pursue dual tracks: refine reformulation toolkits for IFRA‑driven constraints, and invest in bio‑based or novel synthesis routes that reduce dependence on volatile citrus oil markets.
-
Capacity and operations strategy — re-evaluate capital allocation to consider tolling agreements, contract manufacturing, or strategic minority stakes in upstream natural producers where long-term feedstock security is material.
-
M&A and partnership strategy — target bolt-ons that fill capability gaps (e.g., high‑purity distillation, green extraction, or regional distribution) rather than broad horizontal consolidation that duplicates existing scale.
Competitive landscape — who matters and why
The Citral market is populated by a layered ecosystem: multinational specialty chemical groups, dedicated flavor & fragrance houses, regional natural producers, and niche high‑purity suppliers. Leading global players bring scale, formulation know‑how and integrated aroma platforms, while regional producers provide price flexibility and proximity to feedstock.
-
BASF SE: Positioned as a major synthetic producer with global manufacturing footprint and recent capacity moves that extend downstream menthol/linalool integration. BASF’s investments underscore a strategic bet on synthetic supply to meet large‑volume industrial demand while preserving margins through product adjacencies.
-
ADM: Strong in citrus‑derived ingredients, ADM’s deep linkages into agricultural supply chains make it a critical counterparty for buyers seeking natural credentials or integrated traceability solutions.
-
Symrise, Takasago, Kuraray: These specialty ingredient firms combine R&D, formulation libraries and customer intimacy. Their roles are less about commodity volume and more about enabling high‑value product differentiation.
-
Chinese and Indian producers (multiple regional manufacturers and exporters): These players drive price competition and flexible supply for global markets; recent large‑scale plants have further strengthened capacity on the Asian cost curve.
-
Distributors and high‑purity specialists: Firms that supply premium grades or act as channel partners remain essential for niche cosmetic and perfumery applications where traceability and consistency are non‑negotiable.
Recent developments — including a world‑scale plant start‑up in 2024 and a new BASF site announced in 2026 — have shifted supply balances and underscore the importance of tracking capex cycles at a granular level. For buyers and investors, these events are both a source of opportunity (arbitrage in grade/pricing) and of risk (spot‑price cascades and margin compression in commoditized grades).
What PW Consulting’s Citral Market report delivers (practical, client‑ready assets)
Our study is designed to move beyond descriptive analysis to actionable decisions. The report package includes:
-
Proprietary market model (2020–2032): scenario‑driven demand curves, supply balance outputs and sensitivity modules that let you test feedstock shocks, regulatory tightening and new capacity wave assumptions.
-
Supplier scorecards and heatmaps: differentiated supplier risk profiles incorporating capacity, geographic exposure, quality grades, and sustainability credentials.
-
Regulatory impact matrix: assessment of IFRA/EU cosmetic changes and downstream implications for labeling, allowable concentrations and required reformulation timelines.
-
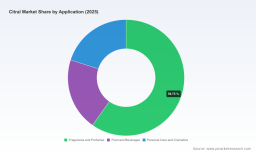
Go‑to‑market playbooks for key application clusters: tailored tactics for flavors, fine fragrances and personal care — including pricing levers, formulation workstreams and sales channel segmentation. (Note: the report provides full segmentation tables and application‑level sizing — sample highlights are withheld here to preserve the value of the full dataset.)
-
M&A and partnership screening: a prioritized list of targets and partnership structures by strategic objective — feedstock security, premium grade capability, or geographic access.
-
Procurement toolkit: contracting templates, hedging approaches for citrus oil exposure, and a recommended supplier diversification threshold calibrated to market concentration metrics.
Action checklist for executives in 2026
-
Short term (0–12 months): institute a rapid regulatory risk audit for SKUs containing citral, secure staggered supply contracts with key partners, and run scenario stress tests using 3–5% feedstock price shock inputs.
-
Medium term (12–36 months): invest in formulation R&D to prepare compliant alternatives for at‑risk SKUs, evaluate strategic equity or offtake arrangements with natural citral producers, and consider modular capacity that can switch between natural‑grade and synthetic grade production to capture margin arbitrage.
-
Portfolio strategy: differentiate your market approach by application cluster — prioritize high‑margin fragrance work with specialty suppliers while managing food & beverage exposure through cost‑efficient synthetic routes and traceable natural sourcing where premium positioning justifies it.
Why this is a must‑read for 2026 planning cycles
The Citral market is at an inflection: regulatory shifts, feedstock volatility, and a fresh wave of capacity are realigning economics and supply chains. For C‑suite leaders and strategy teams, the choices you make now — from contracting cadence to R&D priorities and M&A posture — will materially affect margin resilience and market access over the coming seven years. Our research provides the calibrated data, scenario tools and playbooks you need to convert ambiguity into a competitive plan.
Next steps
PW Consulting’s full Citral Market report contains the complete segmentation tables, regional and application splits, and the interactive models necessary to implement the strategies outlined above. To unlock the detailed datasets and customized advisory options, please visit our Citral Market research page or contact our industry team for a briefing tailored to your organization’s exposure and objectives.
For detailed analysis of this topic, please visit the official page: Citral Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com