

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Flow Battery Market to Expand at 21.78% CAGR Through 2032

Flow Battery Market 2026: Strategic Briefing for C-Suite Decision Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a high‑level briefing designed to orient executive teams, corporate development functions, and project investors as they finalize strategic plans for 2026. This is a preview of our full Flow Battery Market study (base year 2025, historical 2020–2025, forecast 2026–2032) — engineered to demonstrate the analytical depth and practical orientation of the report while intentionally omitting the granular segment tables and financial models that are reserved for subscribers.
Flow Battery Market
Market Snapshot: Why 2026 is a Strategic Inflection Point
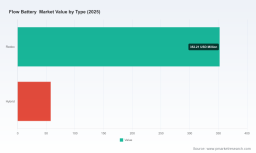
The flow battery market has transitioned from early demonstration to commercial scale within a remarkably short window. Our topline market sizing shows growth from approximately USD 121 million in 2020 to USD 410 million in 2025. With a compound annual growth rate (CAGR) of roughly 21.8% projected across 2026–2032, revenue is forecast to exceed USD 1.6 billion by 2032 under our base-case scenario. That pace of expansion creates decisive windows for first‑mover industrial partners and disciplined investors to lock in supply agreements, secure project sites, and shape market architecture in their favor.
Flow Battery Market
What This Means for 2026 Decisions
- Investment timing: Rapid growth implies an early premium on capacity and supplier commitments. Projects planned for 2026 should prioritize deployable technology stacks and contract terms that protect against short‑term price volatility.
- Procurement and risk transfer: With both established incumbents and emerging technology vendors competing for large utility and C&I opportunities, procurement teams must use multi‑stage RFx processes, performance‑based milestones, and electrolyte supply guarantees to control lifecycle costs.
- Policy and market access: Regulatory frameworks in several jurisdictions are explicitly prioritizing long‑duration storage (including flow technology). Teams entering markets in 2026 need a policy engagement plan to capture incentives and avoid permitting bottlenecks.
Key Growth Drivers and Headwinds
- Drivers: The push for longer‑duration storage to firm renewables, supportive market mechanisms for long‑duration assets, and recent utility/DoD award activity that demonstrates government and institutional appetite.
- Headwinds: Raw material and electrolyte pricing volatility, manufacturing scale‑up challenges, and the need for clear total cost of ownership (TCO) comparisons versus lithium and other long‑duration solutions.
- Implication: Commercial viability in 2026 will depend on project teams’ ability to model multi‑decade operating profiles and to secure both electrolyte and cell component supply under predictable terms.
Competitive and Technology Landscape — Strategic Insights
Our competitive analysis covers a cross‑section of specialist manufacturers and vertically integrated players. Vendors fall into several strategic archetypes: incumbents scaling utility installations, engineering‑led specialists focused on electrolyte chemistry and cycle life, and integrators offering leasing or supply assurances. Understanding which archetype a vendor occupies is critical to structuring procurement and risk allocation.
Flow Battery Market
Notable Vendor Profiles and Strategic Postures
- Invinity Energy Systems — positioning around utility‑scale vanadium systems with modular “power/energy” scalability. Their recent project deliveries demonstrate operational readiness for grid integration and a focus on enterprise‑grade performance guarantees.
- ESS Tech, Inc. — differentiates with long‑duration iron flow chemistry, emphasizing safety and multi‑hour grid use-cases. Their technology roadmap targets lowered lifecycle costs via electrolyte and system optimization.
- Rongke Power — a high‑volume vanadium supplier with deep experience in large deployments and cycle durability claims that appeal to utility procurement teams seeking proven reliability.
- Sumitomo Electric Industries — leveraging industrial scale and legacy engineering to deliver long‑life vanadium systems; recent consecutive orders underline a pipeline of repeat customers.
- Jena Flow Batteries GmbH — focused on metal‑free, organic electrolytes, positioning on sustainability and non‑toxic chemistries as a differentiator for sensitive applications.
- Prudent Energy, CellCube, VRB Energy, Largo, EnSync — each of these firms brings a distinct capability: from VRB modular architectures and leasing/supply models to zinc‑bromine and DoD‑focused resilience deployments. The variety means buyers must match vendor capabilities tightly to their operational priorities.
Recent industry events validate this diversity: Sumitomo’s follow‑on orders and construction starts; Invinity’s phase deliveries to an energy hub; and secured funding for CellCube’s defense‑oriented megawatt deployment. These developments indicate that public and institutional customers are moving from pilots to contracted rollouts — a signal for corporate planners to accelerate decision cycles in 2026.
Supply Chain, Materials and Concentration Risks
Flow battery supply chains are distinct from lithium battery networks. Electrolyte chemistry, availability of critical vanadium feedstock (and alternatives like iron or organic electrolytes), and manufacturers’ ability to recycle or recondition electrolyte are pivotal to lifecycle economics. Our analysis highlights three practical mitigation levers:
- Secure upstream supply or partnerships: Where possible, negotiate multi‑year electrolyte supply agreements, tolling arrangements, or joint ventures that smooth price exposure.
- Design for interchangeability: Favor architectures that permit mid‑life electrolyte reconditioning or chemistry substitution to extend asset life and reduce stranded component risk.
- Localize critical activities: Establish regional electrolyte management and service hubs to reduce logistical, regulatory and customs friction for large deployments.
From a competitive concentration perspective, the market demonstrates moderate concentration among a handful of capable suppliers; however, new entrants and alternative chemistries will continue to reshape supplier dynamics through 2026–2032. Our full report maps vendor market share dynamics, but here we emphasize that concentration implies counterpart diligence is non‑negotiable for large energy‑offtake contracts.
Policy, Market Design and Revenue Stacking
Market design is rapidly evolving to value long‑duration flexibility. Select policy mechanisms now explicitly encourage long‑duration assets through revenue support schemes and procurement set‑asides. There are also high‑visibility public projects (including state energy commission backed installations) that are creating referenceable commercial contracts and operating data sets. For 2026 strategy, teams must do three things:
- Map incentives and grid service revenue streams in target jurisdictions and stress‑test project IRR under conservative market assumptions.
- Build an advocacy and permitting timeline into project plans to capitalize on short windows of supportive policy frameworks.
- Design contracting strategies that allow for revenue stacking (capacity, arbitrage, ancillary services) while preserving lifecycle guarantees and warranty coverage from vendors.
What PW Consulting’s Full Report Delivers
The full PW Consulting Flow Battery Market study is a practical playbook for 2026 strategic choices. Highlights include:
- Proprietary market model: granular topline and demand projections (2020–2032) with downloadable Excel scenarios (base, accelerated, stress) that allow users to model TCO and IRR across deployment scales.
- Vendor benchmarking toolkit: a multi‑criteria framework covering technology maturity, scalability, warranty structure, supply assurances, and third‑party validation scores.
- Supply chain playbook: procurement templates, electrolyte sourcing strategies, and a supplier due diligence checklist designed for rapid deployment timelines.
- Project development and O&M playbooks: recommended EPC vs. integrated procurement routes, performance test protocols, and lifecycle maintenance schedules tied to warranty triggers.
- Regulatory and market engagement matrix: jurisdictional incentive mapping and a staged advocacy plan to accelerate permitting and market access.
- Investment diligence pack: a red‑flag checklist, sensitivity analyses for key inputs (CAPEX, electrolyte replacement, efficiency degradation), and a model for structuring lease versus purchase economics.
- Case studies and implementation roadmaps: anonymized transaction case work, learnings from utility and defense deployments, and a phased go‑to‑market blueprint for 2026 rollouts.
Each deliverable is oriented toward executives and transaction teams who need to translate market signals into executable 12–24 month plans. The report is intentionally structured to help readers move from strategy to procurement to field execution without the need for piecemeal consulting engagements.
How to Use This Preview in 2026 Planning
- Use the topline growth trajectory and CAGR as a sizing benchmark for portfolio allocation to long‑duration storage.
- Prioritize vendor engagements that offer both proven field installations and contractual structures that align vendor incentives with long‑term asset performance.
- Adopt PW Consulting’s procurement and supply‑chain templates to compress procurement timelines while retaining protective commercial terms.
For readers preparing capital allocation, project pipelines, or M&A activity in 2026: the full PW Consulting report contains the underlying models, vendor scorecards, and contract‑level templates you will need to move from intention to execution. This preview is a strategic map; the detailed coordinates and financial models that enable transaction execution are available through our subscription portal and research distribution channels.
Closing
Flow batteries are entering a scale phase where commercial clarity and execution discipline will determine winners and losers. The market’s rapid CAGR and rising project activity mean 2026 will be a pivotal year to lock in supply, define IP and service models, and capture preferential positions in emerging market frameworks. PW Consulting’s full report is built to convert that urgency into precise actions — from vendor selection and contract architecture to capital deployment and operational readiness.
To access the complete datasets, model templates, and vendor benchmarking matrices referenced in this briefing, please consult the PW Consulting report release page. Our team stands ready to support bespoke diligence, transaction advisory, or implementation planning tailored to your 2026 objectives.
For detailed analysis of this topic, please visit the official page: Flow Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com