

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Roller Compactor Market to Reach USD 270.6M by 2032 at 6.5% CAGR

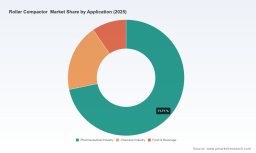
Roller Compactor Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As companies prepare capital allocation, product roadmaps, and go-to-market strategies for 2026, the roller compactor market presents a clear, data-backed growth trajectory and a set of structural shifts that demand proactive responses. PW Consulting’s latest study (base year 2025; historical window 2020–2025; forecast 2026–2032) frames the market in both numbers and actionable insight. At a compound annual growth rate (CAGR) of 6.5% through 2032, the market expands noticeably from a mid‑2020s base to meaningful scale by the end of the forecast period (from ~USD 175.2 Million in 2025 to ~USD 270.6 Million in 2032). This expansion is being driven by sustained demand for dry granulation technologies across regulated industries, incremental technology upgrades, and increasing emphasis on energy and process efficiency.
Roller Compactor Market
Why this matters for 2026 strategy
-
Capital allocation timing: With a predictable growth curve and rising capital intensity in certain product classes, 2026 is a focal year to decide on phased investments versus opportunistic tuck‑ins. The market’s mid‑single-digit CAGR gives room for cautious, staged deployments that preserve optionality.
Roller Compactor Market -
Portfolio prioritization: Vendors and OEMs need to balance R&D and production investments between higher‑throughput industrial systems and smaller, high‑containment units used in pharmaceuticals and specialty chemicals. The report identifies where premium pricing for containment, compliance, and quality control can be defended.
Roller Compactor Market -
Service & aftermarket economics: As installed bases grow, recurring revenue from spare parts, retrofits, and tolling services becomes a major lever for margin improvement. 2026 strategies should include concrete plans to build or acquire service capabilities and to monetize lifecycle upgrades.
-
Regulatory and safety risk mitigation: Evolving standards and documented safety incidents elevate compliance and operator protection to board‑level issues. Decisions made in 2026 around product design, warranty terms, and training programs will materially affect risk profiles over the next business cycle.
What PW Consulting’s report delivers (practical content you can act on)
-
Robust market sizing and trend models: Historical series (2020–2025) and scenario‑based forecasts (2026–2032) in USD Million, with sensitivity runs around macro drivers and adoption curves.
-
Demand driver decomposition: Industry‑level growth levers (pharma formulation shifts, chemical processing needs, food & beverage applications), including elasticity estimates and penetration ceilings.
-
Commercial playbooks: Go‑to‑market blueprints tailored to OEMs, contract manufacturers, and tolling service providers — including pricing archetypes, bundling strategies, and channel incentive structures.
-
Technology & product roadmaps: Comparative assessment of machine architectures (high‑containment, cantilevered, high‑pressure, production‑scale lines), upgrade vectors (automation, sensors), and retrofit economics.
-
Regulatory and safety matrix: A concise compendium of relevant standards and compliance checkpoints, with actionable design and documentation requirements mapped to product classes.
-
Competitive benchmarking: Vendor scorecards, capability matrices, M&A appetites and white‑space maps used to identify acquisition targets or alliance partners.
-
Operational tools: CapEx/Opex templates, payback calculators, and an implementation roadmap to move from pilot to full production deployment in 6–18 months.
Competitive landscape — what leading players are doing
The competitive field combines long‑standing OEMs that serve regulated sectors with regional specialists that contest specific segments. Key incumbent and specialist vendors profiled in our study include companies focused on high‑containment pharmaceutical workflows, enterprise‑grade production press lines, and turnkey tolling services. These firms differentiate on containment, material handling integrations, granule quality, and throughput flexibility.
-
Fitzpatrick (Waterloo, Ontario) — recognized for lab‑to‑production roller compactors and high‑containment systems suitable for pharmaceuticals and specialty chemicals. Their value proposition centers on safe scale‑up and validated process continuity.
-
Hosokawa Alpine (Leingarten, Germany) — known for Kompaktors and a longstanding heritage in powder compaction; their engineering focus is on precision and reliability for multi‑industry use.
-
Alexanderwerk (Remscheid, Germany) — emphasizes cantilevered systems and high‑quality granule outputs, appealing to operators prioritizing narrow particle size distributions and low fines.
-
Bepex (Minneapolis, USA) — competes with high‑pressure roll compactors for briquetting and dense granule formation, often selected where densification is a critical process parameter.
-
L.B. Bohle (Ennigerloh, Germany) — offers continuous and batch dry granulators with strong acceptance in pharmaceutical manufacturing lines requiring cGMP compliance.
-
WelchDry (Holland, Michigan, USA) — positions itself as both a service provider and equipment partner, offering toll roller compaction aligned to nutraceutical and food customers seeking compliance and speed‑to‑market.
-
Cadmach and Prism Pharma Machinery (Ahmedabad, India) — significant regional players supplying production roll compactors, offering competitive cost structures and scalable platforms for non‑regulated and regulated markets.
Across the ecosystem, the market exhibits moderate concentration: several established global vendors anchor buyer decisions, while a broader set of regional and niche suppliers competes on price, lead time and service. For readers seeking the exact distribution of market shares and competitive positioning, the full report provides the detailed vendor matrix and referenced primary research.
Recent market movements and their strategic implications
-
Electrification & emissions reduction (Nov 2024 product launches): Leading industrial contractors and OEMs are introducing electric drive roller compaction technologies aimed at lowering operational emissions and total cost of ownership. For manufacturers of compaction equipment, this accelerates the need to validate electric powertrains and offer retrofit pathways.
-
Digital platforms & fleet management (2025 launches): Digitalization of fleet and asset management is moving from retrospective monitoring to prescriptive maintenance. Vendors that embed digital interfaces and API‑first architectures gain advantage in multi‑machine installations and service contracts.
-
AI partnerships for process control (2025 strategy deals): Strategic tie‑ups between OEMs and software houses to develop AI‑driven compaction process control are reshaping the value proposition — moving from hardware supply to outcome guarantees (e.g., consistent granule density, reduced rework).
Regulatory and safety landscape — what to build into 2026 plans
Operators and equipment makers face a tightening set of standards and documented safety incidents that should be core inputs to product development and service strategies. Relevant items include standards for preparation and compaction energy control, local DOT and construction specifications for compaction equipment, and accident reports that spotlight human‑machine interface and guarding requirements. Integrating these mandates into product design, training curricula, and warranty frameworks will materially reduce liability and market friction.
Key risks and mitigation pathways
-
Supply chain volatility — mitigate through dual sourcing, inventory smoothing, and strategic supplier partnerships for critical components (rolls, bearings, control electronics).
-
Regulatory shocks — embed regulatory intelligence into product roadmaps and maintain prioritized compliance milestones; build modular designs that allow low‑cost compliance retrofits.
-
Competitive margin pressure — offset through services, consumables and software subscriptions that create annuity revenue and higher lifetime customer value.
-
Technology disruption — monitor AI process control and electrification developments and plan 12–18 month pilots to validate returns before full roll‑out.
Recommended 2026 playbook (practical steps for leadership teams)
-
Define a two‑track product plan: a near‑term upgrade path for existing customers (retrofits, digital add‑ons) and a medium‑term next‑generation platform (electrified drives, modular safety shells).
-
Launch service‑led growth initiatives: create bundled maintenance, spare parts subscriptions and process‑assurance contracts to convert CapEx buyers into recurring revenue relationships.
-
Invest in compliance‑by‑design: map standards and incident learnings to product specifications; make compliance a sales differentiator in regulated verticals.
-
Pursue selective partnerships: prioritize alliances that accelerate AI process control, digital fleet management, or provide established footprints in underpenetrated markets.
-
Use scenario planning: run three demand cases (base, upside, downside) with the provided PW Consulting templates to stress‑test capacity and working capital needs for the next 18–36 months.
Closing — where to go from here
This preview surfaces the strategic imperatives and operational levers relevant to 2026 planning cycles — from capital investment cadence to product differentiation and after‑sales economics. We intentionally hold back granular regional and application split figures from this summary to preserve the actionable uniqueness of the full study; those segmented datasets, supplier scorecards, and downloadable financial models are available in the complete PW Consulting Roller Compactor Market Report.
For teams preparing board papers, investment memos, or R&D roadmaps this year, the report supplies the empirical foundations and tactical tools to translate market momentum into defensible, profitable actions. To access the full dataset, vendor benchmarking, and ready‑to‑use financial templates, please refer to PW Consulting’s report portal.
For detailed analysis of this topic, please visit the official page: Roller Compactor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com