

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Non-GO Electrical Steel Market to Grow at 5% CAGR to 2032

Non-Grain-Oriented Electrical Steel: Strategic Imperatives for 2026 Decision-Makers
As global electrification accelerates and manufacturers race to improve motor efficiency, Non-Grain-Oriented (NGO) electrical steel has emerged as a strategic raw material — one that sits at the intersection of cost, performance and supply-chain risk. PW Consulting’s latest market study (base year 2025) provides a calibrated view of the NGO market through 2032, delivering the diagnostic instruments and strategic scenarios that corporate leaders will need to navigate 2026 with confidence. This article highlights the study’s strategic value, summarizes the most consequential market dynamics, and previews the competitive map — deliberately withholding granular segmentation tables and company-level volumes to preserve the full analytical value of the report and invite direct engagement.
Non Grain-oriented Electrical Steel (Non-Grain Oriented Electrical Steel) Market
Market snapshot (what to know now)
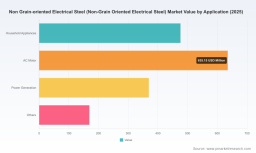
After steady growth through the early 2020s, the NGO electrical steel market reached an estimated USD 1,650 Million in 2025 (base year). Our modelling shows the market expanding at a compound annual growth rate (CAGR) of approximately 5.0% over the 2026–2032 forecast window, reaching roughly USD 2,322 Million by 2032. This trajectory reflects persistent demand from electric motor applications, household appliances, and power equipment, combined with structural shifts in product mix and material sourcing practices.
Non Grain-oriented Electrical Steel (Non-Grain Oriented Electrical Steel) Market
Two structural features shape near-term strategic choices. First, a moderate-to-high industry concentration: the top three suppliers control nearly half of the market, while the top five firms account for roughly two-thirds of market capacity. Second, supply-side investment is materializing — with major producers commissioning new lines and eco-focused capacity that will reconfigure regional balance and lead-time dynamics over the next 18–24 months.
Non Grain-oriented Electrical Steel (Non-Grain Oriented Electrical Steel) Market
Why this study matters for 2026 planning
- Procurement strategy: Understand when and where to lock supply agreements. With raw-material price volatility and trade measures reshaping landed costs, procurement leaders must time contracts and select counterparties using forward-looking scenarios rather than backward-looking averages.
- Manufacturing footprint decisions: Facility location and sourcing strategies should be stress-tested against tariff regimes, regional investment commitments by producers, and projected lead times — all of which the report quantifies and models.
- R&D and product roadmap prioritization: NGO steel grades influence motor efficiency and thermal performance. Our analysis links material characteristics to incremental product value so R&D and product teams can prioritize alloy and process choices that maximize total cost of ownership for customers.
- M&A and JV diligence: The market’s concentration and ongoing capacity investments create specific windows of value for buyers. Buy-side and sell-side teams can use our valuation-sensitive scenarios to identify attractive targets and negotiate from a position of fact-based leverage.
- Regulatory and trade risk management: Trade measures and raw-material cost spikes can rapidly shift competitiveness. The study provides bespoke impact matrices that translate tariff and feedstock changes into margin and cash-flow sensitivities.
Key industry dynamics shaping 2026
- Raw-material pressure: Silicon metal — a key feedstock — has experienced month-on-month price variation into 2026 (notably reaching US$1.74/kg in May 2026 in sector monitoring). Even small unit-cost movements can compress margins or force price pass-through in finished NGO products; we quantify those elasticities in the study.
- Trade policy and tariffs: From 2025, a raft of tariff adjustments and caps have altered trade economics. For example, higher duties on certain imports were imposed in early 2025, followed by caps and differentiated rates for specific source regions later that year. These interventions materially affect supplier selection and near-shoring calculations.
- Industrial capacity evolution: Leading producers are moving from incremental upgrades to greenfield and high-efficiency lines. Notable examples include recent capacity expansions and new-line launches by major steel players — developments that will change lead times and product availability across regions.
- Consolidation and specialization: With the top players holding a substantial share of market capacity, we expect continued vertical integration, selective M&A and more pronounced specialization between semi-processed and fully-processed product streams.
Competitive landscape — what the major players signal
The NGO market is served by a mix of long-established steelmakers and specialists that combine metallurgical depth with scale production. Our competitive analysis disaggregates firms by technological differentiation, integrated supply-chain reach, and go-to-market focus. Below we summarize what each core incumbent brings to the table for NGO customers and corporate strategists.
- thyssenkrupp Steel (Düsseldorf, Germany) — A technology-forward European supplier with a focus on tailored NGO offerings for industrial motors and appliance OEMs. Their strategic posture emphasizes product customization and downstream partnerships that reduce integration cost for European manufacturers.
- Nippon Steel Corporation (Tokyo, Japan) — Known for metallurgical R&D and high-quality gauge control, Nippon’s portfolio centers on premium NGO grades that target high-efficiency motors. They remain a reference point for customers valuing consistent electrical performance.
- POSCO (Seoul, South Korea) — POSCO’s recent investments underscore a push into eco-efficient, high-throughput production. The company completed the initial phase of its "Hyper No" plant at Gwangyang in January 2025, signaling capacity and technology upgrades that will affect regional supply dynamics.
- JFE Steel Corporation (Tokyo, Japan) — A resilient supplier with strengths in process control and downstream finishing. JFE occupies a balanced position between premium performance and competitive cost structures, servicing both appliance manufacturers and industrial motor producers.
- ArcelorMittal (Luxembourg) — With a substantial European footprint, ArcelorMittal is expanding electrical steel production — notably preparing a large new unit in Mardyck, France, with initial lines due online in late 2025. This investment is the largest European electrical steels commitment by the firm in a decade and will shift European capacity dynamics.
- Tata Steel (Rotterdam, Netherlands) — Leveraging integration across European sites, Tata focuses on supply stability and application engineering for automotive and appliance segments, acting as a dependable partner for customers seeking continuity and technical support.
- Nucor Corporation (Charlotte, NC, USA) — A US-focused competitor that emphasizes domestic supply and rapid response times. Nucor’s strengths are in local lead-time management and integration with North American OEMs, an advantage under tightened regional trade regimes.
- Cleveland-Cliffs Inc. (Cleveland, OH, USA) — Combining raw-material integration with downstream processing, Cleveland-Cliffs plays to customers prioritizing scale and security of supply in North America.
- NLMK Group (Moscow, Russia) — A significant Eurasian supplier with competitive cost positions in select grades. NLMK’s regional reach provides an alternative sourcing base for particular geographies and product specifications.
- Baosteel Group (Shanghai, China) — A major Asian producer with broad product breadth and cost-competitive offerings. Baosteel remains central to global supply balances and competitive pricing dynamics across many applications.
What our report contains — practical, decision-ready assets
The full PW Consulting study is structured to be operationally useful for procurement, product and corporate strategy teams. Key deliverables include:
- Market sizing and validated time-series (2020–2025 historical; 2026–2032 forecast) with scenario-based sensitivity testing around price, tariff and demand shocks.
- Supplier matrix and capability heatmaps that rank producers on quality, scale, ESG performance and time-to-serve — enabling shortlisting for strategic RFPs.
- Scenario-playbook for procurement: contract timing, hedging recommendations, tactical spot vs. capacity-reservation guidelines calibrated to different supplier archetypes.
- Regulatory impact toolkits: quantified margin and landed-cost implications for principal tariff and feedstock scenarios, including recommended mitigation actions.
- Technology and product roadmap alignment: a framework connecting NGO steel grades to motor efficiency gains and total cost of ownership for OEM customers.
- M&A and partnership dossier: valuation-relevant metrics, target screening filters and integration checklists for buyers and investors.
How to use the study in 90–180 day initiatives
- Procurement: Use our price-elasticity and supplier risk matrices to prioritize contract renewals slated for Q3–Q4 2026. The study identifies tactical opportunities to stagger commitments and reduce price exposure.
- CapEx and footprint strategy: Run the report’s localization and tariff scenarios against your product mix to determine whether incremental near-shore capacity or long-term supplier contracts deliver better NPV under plausible trade regimes.
- Product teams: Map your motor and appliance SKUs to the report’s grade-performance matrix to identify low-hanging efficiency improvements that can be delivered via material substitution rather than full redesign.
- Corporate development: Use our competitive gap analysis to size acquisition targets and to define commercial synergies that justify premium offers.
Why this is a trailer, not the whole film
This article intentionally highlights the study’s strategic value and major directional insights while withholding granular segment-by-segment volumes, regional and application breakdown tables, and detailed supplier production figures — the analytical backbone that clients use to make contract, capex and M&A decisions. Those detailed datasets and the interactive scenario tools are made available in the full PW Consulting report and accompanying client dashboard.
For boards, procurement leads, R&D heads and corporate development teams preparing for 2026, the question is not whether the NGO electrical steel market matters — it does — but how you will translate macro growth and shifting supply-side structure into concrete actions that protect margins and accelerate product value. PW Consulting’s study converts market signals into executable options. To access the full dataset, supplier-level analysis and the scenario workbooks that power robust decision‑making, please visit our report page or contact your PW engagement lead.
For detailed analysis of this topic, please visit the official page: Non Grain-oriented Electrical Steel (Non-Grain Oriented Electrical Steel) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com