

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Charcoal Market Poised for 5.79% CAGR Through 2032

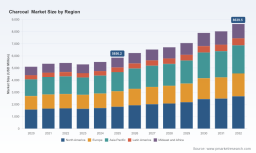
Charcoal Market — 2026 Strategic Preview
Executive snapshot
The charcoal market is moving from a stable, regionalized commodity into a strategic industry where feedstock sourcing, regulatory calculus, and product positioning determine winners and losers. Our PW Consulting Charcoal Market study uses 2025 as the base year and traces historical dynamics from 2020–2025 while projecting to 2032. At the macro level, the market expanded from roughly USD 5.1 billion in 2020 to about USD 5.86 billion in 2025 and is forecast to reach approximately USD 8.64 billion by 2032, reflecting a compound annual growth rate (CAGR) of 5.79% across the forecast horizon. Market concentration is material (top-three firms account for roughly two-thirds of market share, with the top-five approaching three quarters), which shapes competitive moves and margins across regions and product types.
Charcoal Market
Why this preview matters for 2026 decision cycles
-
Investment prioritization: The projected mid-single-digit CAGR and mid-term market size trajectory provide the revenue envelope executives need to evaluate capex and capacity commitments for 2026–2028.
Charcoal Market -
Sourcing and cost strategy: Raw material price volatility and geographic feedstock availability are already altering unit economics. The report synthesizes price movements and delivered-cost patterns that materially change breakeven calculations for new plants or expansions.
Charcoal Market -
Regulatory timing: Emerging tax credits and public funding have the potential to reframe the carbon and fuel-cost calculus. Understanding the timing and scope of these measures is critical when deciding whether to pursue retrofits, green-product labeling, or vertical integration strategies in 2026.
-
M&A and partnership scouting: A moderately concentrated market with several strong regional players means attractive bolt-on targets and partnership opportunities for firms seeking scale or channel access.
What the PW Consulting report delivers — an actionable toolkit
This research was designed as a practitioner’s playbook for 2026 strategic decisions. The core deliverables include:
-
Top-down market sizing and forward-looking scenarios: A clear base-year (2025) view, historical trend decomposition (2020–2025), and three structured forecast scenarios for 2026–2032 tied to feedstock, demand, and regulatory assumptions.
-
Segmentation frameworks: A layered segmentation by geography, product type and application, each accompanied by qualitative demand drivers and supply-side constraints. (Note: detailed segment-level tables and exact share splits are reserved for the full report.)
-
Supply-chain and cost model: Delivered-cost build-ups, sensitivity to stumpage and delivered wood prices, and plant-level operating economics to test greenfield and expansion investments.
-
Regulatory and incentives tracker: A jurisdiction-by-jurisdiction assessment of relevant policy levers, including recent federal funding and proposed tax-credit frameworks that could affect feedstock eligibility and project IRRs.
-
Competitive benchmarking and M&A pipeline: A ranked view of incumbent capabilities, capacity, product portfolios, and a screened list of M&A candidates aligned to common buyer archetypes.
-
Go-to-market playbooks: Tailored strategies for branded consumer products, industrial fuel supply, and premium/medical-grade activated charcoal segments — including channel economics, pricing levers, and a sustainability messaging framework.
-
Risk matrix and early-warning indicators: A short list of leading indicators (price, policy, logistics disruptions) that should trigger tactical contingency actions.
Competitive landscape — who matters and why
The industry is characterized by a mix of long-established consumer brands, regional producers with export reach, and niche specialists serving industrial and medical-grade needs. Key players profiled in the study include:
-
Kingsford Products Company (United States) — a century-old brand with deep consumer channel penetration and a recent focus on natural-charcoal formulations; their consumer marketing and distribution footprint make them a bellwether for retail demand shifts.
-
Royal Oak Enterprises, LLC (United States) — one of the largest U.S. producers of both lump charcoal and briquettes; recent capacity expansion plans underline an aggressive growth posture in North American supply.
-
Duraflame, Inc. (United States) — a major wood-fuel and briquette producer whose operations demonstrate how single-point supply-chain disruptions can ripple through regional capacity; recent plant-fire impacts have highlighted substitution and logistics risks.
-
Gryfskand Sp. z o.o. (Poland) — a European specialist producing high-purity activated charcoal for pharmaceutical and medical applications, representing the high-margin, quality-driven end of the value chain.
-
Vina Charcoal (Vietnam), Namchar Pty Ltd (South Africa), Bricapar S.A. (Spain) and Profagus (Germany) — regional producers with either export-oriented models or artisanal/premium positioning that capture differentiated margins and feed into global supply networks.
Two recent developments in our coverage highlight strategic fault lines: Royal Oak's announced new facility in Texas (Jan 2025) signals domestic capacity build-out aimed at capturing increased retail and industrial demand; and the supply-chain disruption caused by a major supplier's plant fire (reported mid‑2025) illustrates the fragility of localized wood-supply chains and the need for multi-source strategies.
Market dynamics and policy tailwinds — what to watch in 2026
-
Feedstock cost deflation and divergence: Recent data show stumpage prices for certain pine pulpwood classes moved down significantly over a multiyear span, while delivered prices to pulp mills exhibited more muted declines. The result is sharper margin pressure for processors that rely on delivered wood rather than vertically integrated sourcing. Timber-price cycles in major supplier regions also shifted in late 2025, creating opportunities for procurement teams that act quickly.
-
Public funding and energy policy: Large-scale commitments to retrofit coal-fired facilities and to incentivize cleaner fuels — including a notable federal program announced in late 2025 — create second-order market opportunities for firms able to position wood-derived carbon products within clean-fuel or substitute-fuel schemes.
-
Tax-credit developments: Proposed regulations under a new Clean Fuel Production Credit framework (section 45Z) in early 2026 could extend eligibility to certain wood-product pathways. This would change project economics for qualifying facilities and elevate policy risk/reward calculations for new investments.
-
Concentration and channel power: With the top three and top five players holding a commanding share of the market, national distributors and large retail chains exert meaningful commercial leverage. New entrants must therefore pair capacity with a clear channel strategy or niche differentiation.
Strategic imperatives for 2026
-
Secure diversified feedstock contracts and consider vertical integration where it materially de-risks delivered costs. Short-term price anomalies mean opportunistic procurement can boost margins in 2026–2027.
-
Model policy scenarios into every capital decision. Even nascent tax-credit proposals can swing IRRs enough to justify or cancel projects when coupled with modest operating improvements.
-
Invest in product differentiation: premium activated charcoal and medically compliant powders carry structural price premiums compared with bulk fuel pools. Certification and traceability investments pay back when paired with export and industrial routes.
-
Design resilience into logistics: single-source supplier disruptions materially impact utilization. Dual-sourcing and strategic inventory buffering should be part of near-term operating playbooks.
-
Prioritize M&A targets that add either scale in concentrated retail channels or access to high‑quality feedstock chains; the right bolt-on can be a faster path to national distribution than organic scale-up.
How to use the full PW Consulting study in 2026 planning
-
Board-level capital allocation: Use our scenario outputs and plant-level economics to stress-test proposed capex under both benign and restrictive policy outcomes.
-
Procurement optimization: Apply our delivered-cost model to renegotiate long-term supply agreements or to validate spot-market purchase decisions.
-
Regulatory engagement: Leverage the report’s jurisdictional policy assessments to prioritize advocacy and to design pilot projects that qualify for incentives.
-
Commercial strategy: Align channel, pricing and product-development plans with the competitive benchmarking and go-to-market playbooks in the report.
Closing — an invitation to continue
Our Charcoal Market study is deliberately structured as a strategic “trail” — it highlights the critical drivers, paints the competitive terrain, and equips decision-makers with the frameworks needed for decisive action in 2026. To preserve commercial value and to support cleareyed tactical planning, certain segment-level tables, exact regional and application share splits, and detailed company financial proxies have been reserved for the full research package. If your agenda for 2026 includes capital projects, M&A, or a pivot toward higher-value charcoal applications, the full report contains the granular models and playbooks to convert intent into measurable outcomes.
For access to the full dataset, company profiles with capacity and cost estimates, and our interactive scenario tool, please consult the PW Consulting publication page.
For detailed analysis of this topic, please visit the official page: Charcoal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com