

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Allulose Market USD 201.03 Million in 2025, 10.2% CAGR to 2032

Allulose Market 2026: Strategic Preview for Corporate Decision-Makers
As PW Consulting’s senior industry analyst, I present a forward-looking primer designed to orient executives, investors, and product strategists on why the allulose market should be a 2026 priority. This piece synthesizes our market modelling (base year 2025, historical 2020–2025, forecast 2026–2032) to surface the strategic inflection points that will determine winners and laggards. We intentionally demonstrate analytic depth here while withholding proprietary segment-level detail — the full report contains the operational granularity and transactional intelligence required to act decisively.
Allulose (CAS 551-68-8) Market
Market snapshot (what the numbers mean for strategy)
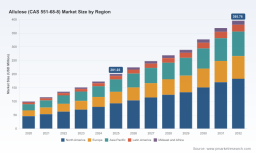
Allulose has moved from niche curiosity to an investable ingredient class. Our market model values the global allulose market at roughly USD 201.0 Million in 2025 and projects a sustained compound annual growth rate (CAGR) of 10.2% over the 2026–2032 forecast window. Under that trajectory, the market is expected to approach roughly USD 396 Million by 2032. The post-2025 acceleration reflects a confluence of regulatory openings in major markets, industrial-scale capacity additions, and faster formulation adoption across food and beverage categories.
Allulose (CAS 551-68-8) Market
These headline figures imply three simple strategic realities for 2026:
Allulose (CAS 551-68-8) Market
- Timing matters: there is a short window to secure advantaged supply and commercial terms before capacity expansions materially increase availability and re-price the market.
- Regulatory differentiation will create asymmetric opportunities by region — regulatory approval and public guidance shape where scaled commercialization can profitably take place in 2026.
- Market depth does not equal concentration: current top-three/top-five concentration metrics remain low, leaving room for mid-sized specialists and agile new entrants to capture share if they pair production scale with channel access and regulatory know-how.
Why this matters for 2026 corporate decision-making
Allulose is no longer an experimental sweetener; it is a programmable ingredient in product roadmaps for reduced-sugar claims, calorie management, and clean-label reformulation. For commercial leaders, the question is not merely whether to adopt allulose, but how to sequence investments across sourcing, R&D, regulatory, and go-to-market to maximize returns while managing short-term supply risk and long-term competitive pressure.
- R&D and product teams must decide which SKUs to reformulate now versus later. Early launches capture novelty premium but face higher raw-material spot risk.
- Supply-chain teams must determine whether to secure long-term offtake/contracts with incumbent producers, invest in co-manufacturing, or pursue alternative sweetener blends to mitigate feedstock and price volatility.
- Corporate development should evaluate M&A and JV targets that provide enzyme/IP, localized manufacturing footprint, or unique distribution routes — all strategic levers to accelerate scale economics.
What the full report delivers (practically usable content)
Our market study is designed to be executable for commercial strategy teams. Key practical deliverables include:
- Validated market-size model (USD Million, base-year 2025) with sensitivity scenarios reflecting regulatory permutations and feedstock shocks;
- Supply-demand matrix and capacity map that identifies near-term bottlenecks by production pathway (enzyme/IP, crystalline vs. syrup supply, and licensing structures);
- Commercial playbooks tailored to three buyer archetypes — multinational F&B manufacturers, regional co-packers, and ingredient distributors — with negotiation levers and sample contracting terms;
- Regulatory impact tracker and decision tree to quantify market access timelines by jurisdiction and outline data-generation milestones for novel-food dossiers;
- Risk register and hedging playbook addressing fructose feedstock constraints, spot-price volatility, and counterparty concentration;
- Investment thesis templates for M&A, minority stake investments, and greenfield capex, complete with trigger points tied to the market model’s milestones.
We deliberately withhold segment-level numeric splits in this preview to preserve the tactical value of the detailed matrices and scenario outputs included in the subscription report.
Competitive landscape — players, positions, and tactical posture
The allulose value chain today is characterized by a mix of enzyme/IP owners, dedicated specialty producers, and broad-based ingredient giants. Leading players occupy complementary roles:
- Enzyme/IP custodians and licensors maintain strategic leverage via technology transfer and production know-how; their licensing choices influence regional entry costs and speed.
- Large ingredient firms and integrated starch processors are deploying dedicated capacity and established distribution channels to capture bulk B2B demand.
- Specialty producers and agile start-ups focus on niche advantages — proprietary grades, co-manufacturing partnerships, or targeted service levels for premium F&B customers.
Representative company dynamics to watch in 2026:
- Several manufacturers have announced and executed capacity expansions through 2024–2025. These moves materially change the supply-side outlook and will compress spot premiums once ramped to steady-state output.
- Regional champions — firms with localized scale and regulatory foothold — are positioned to capture early commercialization in newly opened markets.
- Ingredient incumbents that control upstream feedstocks and licensing relationships have a distinct advantage in negotiating margin-sharing arrangements with large food manufacturers.
Notably, market concentration is low: the combined share of the top three and top five suppliers remains modest, indicating an open competitive field where execution on supply, regulatory strategy, and channel development will determine competitive success rather than simple scale today.
Regulatory and supply dynamics — the primary strategic levers
The regulatory landscape is the single most consequential externality shaping 2026 outcomes. Recent events illustrate the divergence of market access:
- China’s approval of D-allulose powder as a new food ingredient in mid-2025 immediately expanded industrial demand pathways and legitimized scaled production for domestic and export markets. This shifts the calculus for manufacturers and buyers targeting Asia-focused launches.
- Conversely, European regulatory authorities have advised that additional data are required to establish safety for novel-food approval as of mid-2025, creating a gating mechanism that constrains commercial scale-up in that geography until dossiers are strengthened.
- As of early 2026, key Western jurisdictions such as the EU and Canada have not granted full novel-food approvals, which continues to limit large-scale launches in those markets despite growing formulaic interest.
On feedstock and logistics, allulose production relies on fructose derived from starch streams. Intermittent constraints in fructose availability and logistics bottlenecks have driven spot offer volatility. For procurement leaders, the imperative is clear: lock in secured feedstock access and institute multi-source contracts or strategic inventory buffers through 2026 to smooth production and pricing for product launches.
Strategic playbook for corporate leaders in 2026
Based on our integrated modelling and market interviews, we recommend that leaders adopt a tiered approach tied to corporate posture — incumbent manufacturer, challenger brand, or ingredient supplier:
- Incumbent manufacturers: Prioritize supply lockups with tier-one producers, accelerate pilot launches in regions with regulatory clarity, and hedge feedstock exposure through supplier equity stakes or long-term offtake contracts.
- Challenger brands: Focus on a narrow portfolio of SKUs where allulose’s sensory and labeling benefits create clear differentiation; partner with co-manufacturers that offer secured supply and formulation IP.
- Ingredient suppliers and investors: Target enzyme/IP owners and regional capacity platforms for minority investments or joint ventures to capture upside as adoption scales — but base valuations on scenario outcomes that factor in regulatory gating and potential feedstock dislocations.
Across all players, three operational actions should be executed immediately:
- Initiate a regulatory readiness program aligned to target-market timelines (data generation, toxicology bridging studies, consumer messaging for jurisdictions with novel-food scrutiny).
- Secure multi-year supply agreements with staggered delivery and pricing collars to manage upside and downside exposure while preserving flexibility.
- Invest in formulation pipelines that combine allulose with complementary sweeteners or bulking agents to balance cost, taste, and label claims during the scaling phase.
Risks to monitor and contingency planning
Key risks that could materially impact the 2026–2028 revenue path include:
- Regulatory reversals or additional data requirements in major markets that delay commercialization;
- Sustained fructose shortages or logistics disruptions that elevate spot pricing beyond modeled scenarios;
- Rapid commoditization leading to margin compression if capacity additions overshoot demand growth or if technology becomes widely licensed without structural demand expansion.
Each risk is addressed in our full report with quantitative scenario outputs, contingency triggers, and recommended mitigations mapped to board-level decision points.
Conclusion — actionable insight without the granular reveal
The allulose market presents a compelling growth runway through the early 2030s, driven by regulatory unlocks in some jurisdictions, ongoing capacity builds, and continued product innovation in reduced-sugar formulations. Our modelling (base year 2025) shows a clear growth path at a mid-double-digit pace across the forecast window, but value accrual will be uneven and concentrated among organizations that preemptively secure supply, invest in regulatory dossiers, and align product roadmaps to jurisdictional access.
This preview outlines the strategic contours. The complete PW Consulting Allulose Market report delivers the operational data, segmented market matrices, supplier scorecards, scenario-based valuation models, and executable playbooks required to translate insight into 2026 action. For teams building plans this year, the report converts market signals into transaction-ready recommendations and procurement-sourcing templates necessary to capture the next wave of growth.
For detailed analysis of this topic, please visit the official page: Allulose (CAS 551-68-8) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com