

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: HIL market to hit $1.78B by 2032, growing at 9.74% CAGR

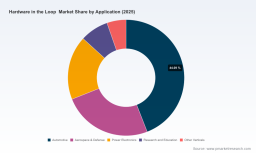
Hardware-in-the-Loop (HIL) Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive summary
The Hardware-in-the-Loop (HIL) testing market is entering a phase of strategic consolidation and capability intensification. Between 2020 and 2025 the global HIL market expanded markedly, and our base-year analysis (2025) shows continued momentum into the forecast horizon. With a compound annual growth rate (CAGR) of 9.74% for the forecast period and market value growth from the low hundreds of millions (USD, revenue unit: Million) in 2020 to a near-billion-dollar market by 2025, HIL has transitioned from a specialized validation tool to an operationally critical platform for product development across automotive, aerospace, power electronics and industrial automation. By 2032, PW Consulting projects a material enlargement of market scale, underscoring HIL’s role as a foundational test paradigm for increasingly software-defined, electrified, and safety-critical systems.
Hardware in the Loop Market
Why this research matters for 2026 decision-makers
For executives and program leads planning investments and roadmaps in 2026, three strategic dimensions make HIL market intelligence essential:
Hardware in the Loop Market
- Timing of capability deployment: HIL sits at the intersection of model fidelity, real-time execution, and hardware integration. Knowing when to shift from bench testing to HIL-enabled validation materially alters development timelines, certification risk and defect costs.
- Partnering and procurement choices: Platform modularity, software ecosystems (notably Simulink/Simulink Real-Time integrations), and vendor roadmaps determine long-term total cost of ownership (TCO) more than first-cost comparisons. Choosing the right supplier mix impacts scalability and reusability across programs.
- Compliance and safety exposure: As standards and recommended practices evolve, documented HIL outcomes increasingly serve as regulatory evidence (for example, in functional safety and grid apparatus testing). Early alignment reduces late-stage rework and certification delays.
Market trajectory and what the headline numbers conceal
Between 2020 and 2025 the global HIL market more than doubled in perceived strategic importance, reflected in a compound expansion that translated into robust revenue growth year-on-year. PW Consulting’s dataset shows growth from 2020 through the base year and projects sustained expansion through 2032 underpinned by electrification, autonomy, and industrial digitalization trends. The headline CAGR of 9.74% masks structural heterogeneity: different sub-segments scale at different speeds, platform architectures (FPGA-centric vs. modular CPU-based) command distinct adoption curves, and software toolchain interoperability is a primary enabler of cross-domain reuse. Our full report unpacks these asymmetries and presents scenario paths for conservative, base, and accelerated adoption cases.
Hardware in the Loop Market
Core dynamics shaping HIL adoption
- Technology convergence and fidelity: Advances in FPGA performance, deterministic communication fabrics, and digital twin integration are elevating HIL fidelity into domains previously reserved for field testing. High-fidelity simulators are increasingly used for power-electronic switching behavior and real-time sensor emulation at scales that were infeasible five years ago.
- Standards and regulatory pressure: Regulatory bodies and professional institutions have tightened guidance for simulation-based validation. Regional and cross-industry guidance—coupled with updated recommended practices for HIL testing—creates both an opportunity (standardized acceptance criteria) and an obligation (documented, auditable test artifacts).
- Labor and skill constraints: HIL programs require a blend of controls engineering, model-based design expertise, FPGA/RTOS competence, and systems integration skill. Skilled personnel scarcity increases program ramp costs and creates differentiation opportunities for vendors offering turnkey services or low-code deployment paths.
- Cost of entry vs. TCO: High initial capex for real-time simulators and custom I/O remains a barrier in some use cases. However, when amortized across multiple vehicle programs or power-system projects, HIL can become the least risky and most predictable validation route—if organizations account for lifecycle costs and reuse strategies.
Competitive landscape — what matters beyond brand names
The competitive topology of the HIL market is a mix of specialist platform vendors, simulation-tool integrators, and broader automation and engineering-software incumbents. Market concentration is meaningful—our CR3 and CR5 metrics indicate that the top-tier vendors control a notable share of revenue and influence (CR3 ~49.3%, CR5 ~61.4%). For buyers and investors, the relevant variables are not only market share but capability depth, ecosystem openness, and strategic partnerships.
- dSPACE (Paderborn, Germany): Leaders in integrated real-time HIL platforms and toolchains for ECU testing across automotive and aerospace. Strategic moves into AI-augmented workflows point to a push beyond classical simulation toward hybrid virtual-physical development environments.
- National Instruments / Emerson Electric (Austin, TX): Modular test architectures and a software-centric approach to HIL have made them a standard in industrial and transportation validation. Recent software suite launches signal an emphasis on embedded software lifecycle support.
- OPAL-RT Technologies (Montreal, Canada): Known for high-performance real-time platforms optimized for power-electronics and grid-scale testing; product introductions targeted at bench applications expand their addressable market in academia and industry.
- Speedgoat (Därligen, Switzerland): Offers highly integrated simulators aligned with MathWorks workflows. Their modular approach is attractive for organizations seeking tight Simulink-to-target toolchains.
- Typhoon HIL (Switzerland): FPGA-based ultra-high-fidelity simulators with strong traction in power electronics and e-mobility; recent partnerships with semiconductor suppliers accelerate joint solutions for EV powertrain validation.
- Vector Informatik, IPG Automotive, Elektrikbit, MathWorks, Ansys, and Siemens: Each occupies a strategic niche—ranging from bus-system emulation and ADAS sensor validation to multiphysics model integration and enterprise-grade automation validation. Collectively they form an interoperable—and sometimes competitive—ecosystem.
Recent industry developments to watch (selected)
- dSPACE’s partnership with a major cloud/AI provider to apply generative AI for virtual ECU development, signaling vendor moves to compress integration cycles and automate test-script generation.
- Typhoon HIL’s collaboration with a leading semiconductor manufacturer to accelerate EV power-electronic development, highlighting verticalized go-to-market strategies.
- OPAL-RT introducing bench-focused Power-HIL systems to broaden addressable users in academic and industrial labs.
- Emerson launching a LabVIEW-based HIL software suite to deepen embedded-software testing capabilities within established test ecosystems.
What the PW Consulting report delivers (practical, actionable content)
Our full HIL market study is structured to support decision-making across procurement, R&D, and M&A. It provides:
- Forward-looking market sizing and scenario modeling (2026–2032) with sensitivity analyses keyed to technology inflection points.
- Vendor benchmarking across capability dimensions: real-time determinism, I/O breadth, toolchain integrations, service delivery, and roadmap alignment.
- Technology deep dives: FPGA vs. CPU trade-offs, digital-twin coupling, sensor-stimulus fidelity, and software-in-loop/hardware-in-loop co-validation strategies.
- Operational playbooks: detailed checklists for pilot design, validation templates aligned to safety standards, and procurement evaluation matrices to minimize integration risk.
- Financial tools: TCO templates, amortization scenarios, and build-vs-buy decision frameworks for program managers.
- Risk registers and mitigation strategies centered on skills, supply chain bottlenecks, and compliance readiness.
Practical recommendations for 2026 planning
Based on our market analysis and vendor landscape, PW Consulting recommends a portfolio of near-term actions for companies that will accelerate time-to-value while managing risk:
- Adopt a phased HIL deployment strategy: pilot with high-impact systems (e.g., EV powertrain in automotive or converter controls in utilities) and scale platform investments only after proving fidelity and reuse across programs.
- Prioritize ecosystem interoperability: select platforms that expose open APIs and certified integrations with mainstream model environments to protect software IP and enable cross-vendor orchestration.
- Invest in targeted capability-building: create a small, cross-disciplinary HIL center-of-excellence (controls, FPGA, systems) to centralize expertise, shorten time-to-competence and reduce external service dependency.
- Leverage standards as enablers: align test plans with emerging recommended practices and functional-safety criteria to convert compliance effort into defensible design decisions.
- Pursue strategic partnerships: where vendor roadmaps align with product timelines, consider co-development, long-term support agreements, or minority investments to secure priority access to enhancements.
- Factor lifecycle economics into procurement: evaluate upgradability, module reusability, and software licensing models rather than choosing solely on upfront cost.
Conclusion — positioning for advantage in 2026
The HIL market’s trajectory to 2032 reflects both accelerating demand and increasing sophistication in how organizations validate complex electro-mechanical and cyber-physical systems. For leaders planning budgets and capability roadmaps in 2026, HIL is no longer an experimental add-on; it is a strategic infrastructure decision with implications across product assurance, time-to-market and regulatory exposure. PW Consulting’s comprehensive study provides the tactical blueprints and commercial intelligence required to convert the HIL opportunity into durable competitive advantage.
Next steps — where to find the full intelligence
This preview outlines the strategic contours and operational implications that executives must weigh in 2026. The full PW Consulting report contains granular vendor scorecards, validated scenario spreadsheets, and program-level procurement templates designed for immediate operational use. To access the detailed segmentation, proprietary modeling, and downloadable toolkits that support rapid decision-making, please consult the PW Consulting HIL Market report page for subscription and executive briefing options.
For detailed analysis of this topic, please visit the official page: Hardware in the Loop Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com