

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Body-Worn Camera Market to Reach USD 3,353 Million by 2032 (12.5% CAGR)

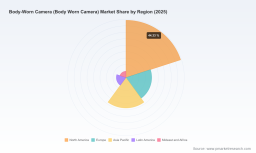
Body-Worn Camera Market 2026: A Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head of Industry Intelligence, I present a focused introduction to our newest Body-Worn Camera (BWC) market study — a concise, actionable briefing meant to orient procurement leaders, CISOs, public-safety chiefs, and corporate security heads preparing for decisive investments in 2026. This preview demonstrates the analytical depth underlying our report while deliberately withholding select granular segmentation metrics to encourage direct access to the full intelligence package.
Body-Worn Camera (Body Worn Camera) Market
Market Snapshot — Scale, Momentum, and What It Means for 2026
The BWC market has matured from early adopters to large-scale, budgeted programs. By our base year (2025) the global market exceeded a substantial mid‑three‑figure million USD threshold and, under the forecast horizon 2026–2032, the sector is projected to expand at a compound annual growth rate (CAGR) of approximately 12.5%. That growth trajectory implies meaningful expansion in device shipments, cloud-storage consumption, and recurring services revenue through 2032.
Body-Worn Camera (Body Worn Camera) Market
For decision-makers, the headline implication is straightforward: buying cycles and procurement windows that begin in 2026 should be designed with multi-year operational costs and platform lock-in risk in mind. The hardware upgrade cadence has shortened as vendors embed higher resolution sensors, edge AI, and continuous connectivity. Meanwhile, the bulk of long-term spend shifts to software, evidence management, and storage — a structural change that must inform budgeting and contract negotiation strategies.
Body-Worn Camera (Body Worn Camera) Market
Why 2026 Is a Pivotal Year
-
Regulatory and funding dynamics have accelerated deployments. In 2024–2026 multiple federal and state programs catalyzed agency rollouts and upgrades. These programs both expand market demand and raise buyer expectations for compliance, privacy-preserving architectures, and auditable retention policies.
-
Technology convergence is redefining supplier roles. Vendors are transitioning from single-point hardware suppliers to integrated platform providers that combine cameras, cloud evidence management, analytics, and device lifecycle services. This is compressing margins on standalone hardware and increasing the strategic value of recurring cloud and analytics contracts.
-
Operational total cost of ownership (TCO) is emerging as the dominant procurement criterion. Our sector analysis confirms that storage and retention compliance often eclipse the initial hardware cost across typical program lifecycles. Organizations that optimize retention policies, invest in efficient ingestion pipelines, and negotiate storage and egress terms will realize disproportionate savings.
What the PW Consulting Report Delivers
Our full study is built for action. It combines quantitative modeling, vendor benchmarking, and practical playbooks tailored for the 2026 decision window. Key deliverables include:
-
Market sizing and forecast model (2020–2032) with scenario sensitivity for resolution trends, live-streaming uptake, and storage-price elasticity.
-
Vendor scorecards that evaluate product performance, platform openness, evidence management maturity, and enterprise support capabilities.
-
Procurement templates optimized for multi-year purchases and Opex‑heavy programs — including RFP language, SLA guardrails, and templates for storage, redaction, and data-request handling.
-
TCO and scenario calculators that quantify the interplay of device refresh cycles, retention policies, analytics adoption, and cloud egress — enabling apples‑to‑apples vendor comparisons.
-
Compliance and privacy playbooks that map major jurisdictions’ data protection requirements to technical controls, redaction strategies, and audit trails.
-
Implementation and change-management guidance: sample training curricula, phased deployment blueprints, and metrics to monitor program adoption and community outcomes.
To preserve competitive value for our subscribers, the report preview intentionally omits line-item segmentation tables and certain granular splits. The full report provides those figures, downloadable models, and interactive dashboards on our portal.
Competitive Landscape — Who Matters and Why
The supplier ecosystem for BWCs is broad, ranging from specialist manufacturers to diversified defense and electronics firms. Market concentration is meaningful but not prohibitive: the top three suppliers together account for a majority share of the market, while the top five increase that share further — a structure that delivers both scale benefits and opportunities for niche challengers.
-
Axon Enterprise, Inc.: Axon remains a market leader, leveraging integrated evidence management, mature training ecosystems, and AI-enabled device features. Its product suite emphasizes full-shift battery life, automated evidence flows, and a tight ecosystem that increases switching costs for large agencies.
-
Motorola Solutions, Inc.: Motorola competes through ruggedized devices and deep integration with command-and-control systems, appealing to agencies prioritizing interoperability with legacy dispatch and in-vehicle video systems.
-
Sony and Panasonic: These legacy electronics manufacturers bring sensor quality and industrial durability to the market. Their strengths lie in high-resolution imaging and enterprise-grade build quality, attracting buyers for evidentiary and forensic use cases.
-
Regional and specialist players (e.g., Axis Communications, Reveal Media, VIEVU): These vendors differentiate on connectivity features, data-sovereignty compliance, and localized support models. They are often selected by buyers with strict jurisdictional privacy requirements or niche operational needs.
-
Accessory and ecosystem vendors (e.g., Transcend, LensLock): Suppliers that address storage security, chain-of-custody, and durable mounting solutions are increasingly integral to procurement decisions, because accessory failure or insecure storage can negate the value of premium imaging hardware.
New entrants, including action-camera OEMs and communications vendors, intensify competition at the hardware layer. However, successful disrupters have coupled compelling device economics with strong evidence management integration and compliance assurances.
Strategic Implications for 2026 Decision-Makers
-
Procure for the program, not just the device. Treat BWC procurement as a multi-year services purchase: devices are catalysts, but the bulk of value and cost lies in ingestion, retention, analytics, and legal compliance.
-
Design procurement to avoid platform lock-in. Insist on interoperable APIs, transparent data export paths, and acceptable metrics for evidence portability. Include contractual exit mechanisms and clear ownership of raw footage.
-
Prioritize storage governance and retention optimization. Model retention strategies against use cases (e.g., flagged incidents vs. routine patrol) to reduce unnecessary long‑term storage costs while meeting evidentiary requirements.
-
Factor grants and external funding timing into procurement cadence. Several jurisdictions accelerated purchases through grant programs in 2024–2026. Agencies and enterprises can increase procurement flexibility by aligning RFP timing with anticipated funding cycles.
-
Build an analytics adoption roadmap. AI-driven redaction, automated incident detection, and transcription are rapidly moving from pilot projects to operational tools. Early investments in annotated datasets and integration pipelines reduce time-to-value and can be decisive in vendor selection.
-
Elevate privacy and data‑sovereignty in vendor scoring. Jurisdictional requirements for lawful processing and minimization are non-negotiable; vendors with demonstrable capabilities to meet GDPR-like regimes or bespoke local rules will be advantaged.
Implementation Playbook — Practical Steps for 2026
-
Run a staged pilot tied to procurement levers: define success metrics (e.g., evidence ingestion latency, percentage of video redacted automatically, officer compliance rates) and convert pilot outcomes into contract milestones.
-
Require vendor-provided TCO scenarios covering conservative, base, and aggressive retention settings; include storage inflation assumptions and egress pricing in evaluation matrices.
-
Mandate security posture evidence: third-party penetration test reports, SOC-type attestations, and documentation of chain-of-custody features.
-
Negotiate training and change-management as contract line items, not optional extras. Adoption risk is social and operational as much as technical.
-
Plan for lifecycle support and spare‑parts logistics, especially for ruggedized deployments and harsh-environment units; downtime metrics must be contractual.
-
Institute an ongoing governance forum that includes legal, IT, operations, and community/stakeholder representatives to review retention policy, redaction rules, and public disclosure practices on a regular cadence.
Closing — Why Our Report Matters for Your 2026 Decisions
The BWC market is at a strategic inflection point: rapid technology enhancement, shifting cost structures, and regulatory attention are all converging to make 2026 a consequential year for buyers. Our market study provides the evidence-based frameworks and procurement-ready artifacts that help organizations minimize risk, control lifecycle cost, and maximize the operational value of camera deployments.
This preview demonstrates the rigor of our analysis — market sizing, concentration metrics, vendor benchmarking, and policy-context mapping — while preserving the competitive utility of our proprietary segmentation and models. To access the full dataset, interactive models, and downloadable procurement templates, please visit the PW Consulting report page. Our team is available to brief executive committees and support bespoke scenario modeling for procurement decisions scheduled in 2026.
For detailed analysis of this topic, please visit the official page: Body-Worn Camera (Body Worn Camera) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com