

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 1,3-Butanediol Market to Reach USD 673.4M by 2032 (4.8% CAGR)

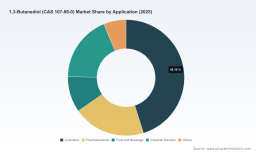
1,3-Butanediol Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As companies finalize strategic plans for 2026, 1,3-butanediol (CAS 107-88-0) has emerged from a niche industrial chemical into a market requiring purposeful positioning. PW Consulting’s latest market study—anchored on a 2025 base year—shows a market that expanded from the high hundreds of millions of USD in 2020 to approximately USD 485.4 million in 2025, and our forecast model projects continued expansion at a compound annual growth rate (CAGR) of roughly 4.8% through 2032. By 2032 the market is modeled to reach the low to mid hundreds of millions of additional USD over 2025 levels, driven by a mix of product premiumization, regulatory shifts, and feedstock dynamics. This preview explains why the report matters for boardroom decisions in 2026, what strategic questions it helps answer, and how executives should prioritize actions before accessing the full dataset.
1,3-Butanediol (CAS 107-88-0) Market
Why PW Consulting’s analysis is mission-critical for 2026
- Transition timing: Regulatory and sustainability forces are converging in 2025–2026 — notably new chemical notifications and regional green policy drivers — that materially affect demand patterns for both petrochemical and bio-based 1,3-butanediol. Strategic timing on commercialization or capacity moves will determine which players capture premium segments.
- Margin and mix management: Our model highlights a nuanced growth story: overall market value is growing steadily, but profit pools are migrating toward high-purity, regulated, and bio-attributed grades. Capturing these requires precise go-to-market and quality assurances rather than simply chasing volume.
- Consolidation and concentration dynamics: The market is oligopolistic in nature — PW’s concentration metrics indicate that a small set of suppliers control the majority of the market — which influences pricing, offtake negotiations, and the pace at which new entrants can scale.
Key structural dynamics shaping 2026 decisions
- Regulatory inflection points. Recent regulatory developments — including new chemical approvals under major jurisdictions and stronger favoring of low-toxicity, bio-attributed chemistries by regional policy frameworks — create windows for product registration, premium positioning, and first-mover reputational gains. Companies must align regulatory filings and compliance roadmaps with commercialization timing.
- Feedstock and cost pressure. Feedstock economics remain critical. Industry reference points used in our techno-economic analyses indicate meaningful sensitivity to butadiene and related feedstock prices, which directly affect the competitive boundary between petrochemical and bio-based production routes. Bio-based production currently carries a significant cost premium — our synthesis of public TEAs places this in the multiple-tens-of-percent range — implying that strategy for bio-based adoption must pair sustainability claims with credible route to cost parity or targeted premium markets.
- Demand heterogeneity. End-markets value different attributes. Cosmetics and pharmaceutical applications prioritize purity and regulatory approvals; industrial applications prioritize cost and scale. The optimal product, pricing, and distribution choices therefore vary across demand pockets and require tailored commercial playbooks.
- Supply-side moves. Recent capacity investments by established producers signal both confidence in demand and potential for temporary oversupply in spot markets. Strategic entrants must evaluate timing, partner with incumbent players, or pursue niche differentiation to avoid price squeezes.
Competitive landscape — what the leading players reveal about strategy
Our competitive analysis profiles global incumbents that set the market tone. Key producers include vertically integrated petrochemical majors with longstanding process know-how, specialty chemical players focusing on high-purity grades for regulated applications, and biorefineries pursuing bio-based routes. Collectively, the top three and top five suppliers capture a very large share of the market, creating high barriers to new mass-market entrants but opening tactical spaces for focused challengers.
1,3-Butanediol (CAS 107-88-0) Market
- Integrated petrochemical leaders: Established incumbents leverage scale, route optimization (for example, acetaldehyde condensation and similar petro routes), and global manufacturing footprints to serve both industrial and regulated segments. Their strategic playbook emphasizes process reliability, supply continuity, and premium grade quality for cosmetics and pharmaceuticals.
- Specialty producers: Dedicated specialty producers concentrate on high-purity grades and customer service for formulations in cosmetics, pharma, and food-contact applications. They are less price-sensitive and able to secure higher margins where regulatory approval and traceability matter.
- Bio-based challengers: Biorefineries and biotech players are advancing bio-based 1,3-butanediol offerings. While production costs are currently higher, their value proposition centers on sustainability credentials and access to policy-driven procurement channels. Strategic partnerships between bio-based developers and experienced formulators are an accelerating theme.
- Notable recent moves: Supply-side expansion by major producers, including documented capacity increases at European sites, underscores that incumbents are both defending and shaping the market. These moves affect short-term availability, contract negotiations, and global trade flows.
From insight to action: Strategic options for 2026
Pivots and investments made in 2026 will determine competitive positioning for the next investment cycle. PW Consulting’s scenario work highlights four pragmatic strategic options, each with a clear set of execution implications:
1,3-Butanediol (CAS 107-88-0) Market
- Defend through integration and offtake security. For incumbents with feedstock access, locking long-term contracts and optimizing upstream integration reduces margin volatility and allows competitive pricing in industrial segments. Execution requires supply-chain renegotiation and contract structuring expertise.
- Differentiate into premium, regulated markets. Target cosmetics, pharmaceutical, and food-contact niches through investment in high-purity grades, registration dossiers, and quality management systems. This path increases margin but needs capital and regulatory lead time.
- Invest selectively in bio-based routes. Given current cost differentials, bio-based strategies should be pursued with staged investments: pilot commercialization focused on high-value end-markets, joint ventures to share capex risk, and parallel efforts to lower production costs (e.g., feedstock sourcing innovations, process intensification).
- Pursue M&A or partnerships for scale and capability. Acquisitions of specialty producers or minority stakes in biorefineries can accelerate market access and capability building while avoiding the full capex burden of grassroots capacity.
What our full report delivers — practical, transaction-ready intelligence
PW Consulting’s full market study is structured to support board-level and commercial decisions with executable deliverables. Key inclusions are:
- Validated market sizing and historical time series (2020–2025) plus scenario-based forecasts for 2026–2032 with sensitivity to feedstock, pricing, and regulatory outcomes.
- Supply-demand balance models and an interactive pricing driver matrix to test scenarios for feedstock shocks and capacity additions.
- Regulatory tracker and compliance roadmap for major jurisdictions — enabling timely TSCA/REACH filings and procurement qualification checklists.
- Company profiles and capability maps for incumbent producers, including plant footprints, grade portfolios, and recent capacity moves.
- Techno-economic analyses (TEA) comparing petrochemical and bio-based routes with explicit levers to close the cost gap.
- Commercial playbooks: contract templates, offtake negotiation strategies, and channel strategies for premium vs. commodity segments.
- M&A and partnership pipeline: target screening, valuation ranges, and integration considerations tailored to strategic objectives.
To respect the “preview” nature of this brief, we intentionally omit segment-level tables, regional and application-specific breakouts, and confidential supplier-level pricing data — these are included in the full report and the accompanying data appendices available through PW Consulting.
Immediate priorities for executives in 2026
- Initiate a rapid TEA refresh: calibrate your cost base to current feedstock prices and test sensitivity to projected raw material scenarios.
- Fast-track regulatory readiness where premium markets are targeted—align TSCA/REACH timelines with launch plans to avoid market access delays.
- Secure strategic feedstock and logistics arrangements—consider multi-year contracts or collaboration with feedstock suppliers to protect margins.
- Assess partnership opportunities with bio-based developers to gain sustainability credentials while managing capex exposure.
- Monitor competitor capacity announcements and adjust commercial strategy to guard against short-term pricing cycles driven by major expansions.
Closing: The strategic value of timely, granular insight
For executives planning capital allocation, market entry, or portfolio repositioning in 2026, the window to act is narrow. PW Consulting’s study translates macro trends, regulatory inflections, supply-side moves, and techno-economic realities into a decision-grade framework. This preview has highlighted the high-level contours of the market, the supplier landscape, and pragmatic strategic options while withholding granular segment-level datasets to preserve the analytical premium of the full report. For teams that require actionable tables, contract playbooks, and scenario models to finalize 2026 decisions, access to the full report and supporting workpapers is the next indispensable step.
Contact PW Consulting to arrange a briefing and obtain the full dataset, model files, and a tailored executive workshop designed to convert these insights into a prioritized 90-day action plan.
For detailed analysis of this topic, please visit the official page: 1,3-Butanediol (CAS 107-88-0) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com