

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Smoke Alarms Market to Reach USD 5.66B by 2032 at 8.4% CAGR

Smoke Alarms Market 2026 Strategic Brief: What Decision-Makers Need to Prioritize
As senior industry analysts at PW Consulting, we present a concise strategic briefing to orient leadership teams, corporate strategists, and investors preparing decisions in 2026. This briefing synthesizes the market trajectory, key competitive moves, regulatory inflection points, and practical playbook actions grounded in our full Smoke Alarms (Smoke Detector) Market study (base year 2025). It is designed as a high-value “trailer”: rigorous enough to validate our methodology and conclusions, but deliberately high-level to protect the granular subsegment modeling and proprietary scenarios available in the full report.
Smoke Alarms (Smoke Detector) Market
High-level market trajectory (data-driven foundation)
-
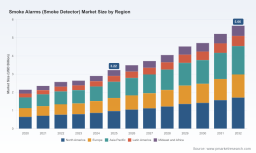
Market momentum: The global smoke alarms market has demonstrated steady expansion over the 2020–2025 historical window and enters the forecast phase with robust momentum. Our modelling shows an overall market value rising from the low single-digit billions in 2020 to approximately USD 3.22 Billion in 2025, and projecting toward the mid-single-digit billions by 2032.
Smoke Alarms (Smoke Detector) Market -
CAGR and implications: A compound annual growth rate of 8.4% across the 2026–2032 forecast underpins our scenarios. That pace implies meaningful demand growth for hardware, integrated systems, and recurring services — enough to justify capacity investments, new-channel experiments, and expanded product roadmaps for many incumbents and selected challengers.
Smoke Alarms (Smoke Detector) Market -
Market structure: The market remains moderately fragmented: leading global players hold meaningful presence but do not monopolize demand. This structure favors both strategic consolidation plays and differentiated organic growth strategies focused on software-enabled value-adds and local execution.
Why this matters for 2026 corporate decisions
-
Product roadmaps and R&D prioritization: With standards and testing protocols evolving, especially around performance and multi-criteria detection, firms must accelerate investment in sensor fusion, false-alarm immunity, and interoperable communications. Product decisions made in 2026 will determine competitiveness through the next certification cycles.
-
Go-to-market and service economics: Growth is not only in unit volumes but in installations tied to building automation and ongoing monitoring/subscription services. Organizations should recalibrate channel mixes — balancing professional installers, national distributors, and direct-to-consumer smart-home strategies — and price to capture lifecycle revenues.
-
Supply chain and localization: Recent production expansions by major suppliers and the globalization of demand demonstrate the value of localized production and shortened lead times. Decisions to invest in regional manufacturing or contract manufacturing in 2026 will mitigate logistics risk and can be a source of competitive differentiation.
-
Compliance and procurement planning: New editions of product standards and codes mean procurement lead times for certified solutions can lengthen. Procurement teams should move from reactive sourcing to a certification-aware procurement calendar to avoid retrofit cycles and project delays.
What our full report delivers (practical, executable insights)
-
Validated market sizing and forward-looking forecasts by product family and channel, backed by bottom-up modelling and scenario stress tests.
-
Structured growth-driver analysis with quantified sensitivity testing (socioeconomic drivers, building stock renewal, code adoption timelines, and smart-home penetration pathways).
-
Competitive playbook: profiles and capability maps for major OEMs, challenger brands, and channel integrators — including technology positioning, service models, and partnership archetypes.
-
Regulatory and standards impact matrix: step-by-step implications of recent and upcoming changes to UL standards, NFPA code updates, HUD requirements, and healthcare accreditation rules, with recommended compliance timelines.
-
Commercial strategy tools: go-to-market candidate prioritization frameworks, pricing levers, B2B vs B2C channel ROI models, and retention-focused service monetization templates.
-
Supply-chain playbook and cost-to-serve benchmarking: supplier maps, localization decision frameworks, and uncertainty buffers for procurement planners.
-
M&A and partnership screeners: target characteristics and a prioritized list of strategic bolt-ons and technology acquisitions to accelerate IoT, multi-criteria sensing, and software/analytics capabilities.
Competitive landscape — themes and strategic implications
-
Convergence of hardware and software: Incumbents such as Honeywell, Johnson Controls, Siemens, and Schneider Electric are leveraging building automation platforms to bundle detection with broader safety and energy services. This trend raises the bar for standalone hardware vendors: to compete, they must offer software or seamless integrability into third-party ecosystems.
-
Wireless and smart-home extension: Consumer-focused players and partners (e.g., collaborations between established fire-safety brands and smart-home platforms) are expanding subscription monitoring and app-based control. New product launches emphasize room-level intelligence and app control, creating differentiation beyond sensor specifications alone.
-
Regional manufacturing and supply resilience: Selected groups have already localized production to reduce supply-chain risk and address regional code variances; such moves materially reduce time-to-deploy for large commercial projects and public-sector procurement.
-
Product innovation frontiers: Multi-criteria detection, false-alarm reduction, and improved sensitivity across environmental conditions are the primary innovation vectors. Vendors that pair these sensor advances with robust certification pathways gain procurement advantages in regulated markets.
Regulatory and standards shifts to factor into 2026 plans
-
Standards evolution: Recent editions of international and national standards introduced enhanced performance and testing requirements. Product teams must embed these changes in development roadmaps and certification plans to avoid market exclusion or costly redesigns.
-
Healthcare and institutional requirements: Accreditation bodies require systematic testing and maintenance regimes; solutions that simplify compliance (e.g., self-testing, audit trails) win specification-led contracts.
-
Public-housing and rental regulation: New rules affecting rental properties create procurement windows for compliant retrofit programs. Market entrants with turnkey retrofit offerings can capture these programs if they mobilize quickly.
-
Operational costs tied to compliance: Routine inspection and certification fees, and the labor component of installations and maintenance, should be built into total-cost-of-ownership analyses when bidding on institutional contracts.
Strategic playbook for 2026 (practical moves for each corporate profile)
-
Large incumbents: Double down on systems integration and lifecycle services. Prioritize platform-level interoperability, bundled service contracts, and local manufacturing/assembly to protect margins and shorten sales cycles for large tenders.
-
Mid-market manufacturers: Pursue product differentiation through multi-criteria sensors and ease-of-installation features. Consider licensing or white-label partnerships with building-automation vendors to access new sales channels quickly.
-
Startups and technology specialists: Focus on niche wins — e.g., false-alarm mitigation, room-specific intelligence, or analytics-as-a-service — and structure pilot programs with national installers to prove ROI and scale fast.
-
Investors and acquirers: Target entities that fill capability gaps for platform owners (software, connectivity, or certification know-how) or that offer rapid route-to-market through existing channel agreements.
Operational risks and mitigation
-
Certification bottlenecks: Anticipate extended timelines around new standard roll-outs; pre-certification partnerships with accredited labs can shorten go-to-market time.
-
Installation labor constraints: Skilled-install labor availability and cost variability affect project economics. Invest in installer training programs and modular, low-labor-intensity designs.
-
Component supply pressures: Sensor and connectivity module shortages remain potential choke points; diversify supplier bases and secure multi-year contracts for critical components.
-
Channel conflicts: As manufacturers pursue direct channels, carefully manage distributor and installer relationships to avoid value-chain erosion.
How PW Consulting’s dataset and modules support your 2026 decisions
-
Scenario-based forecasting calibrated to policy adoption timelines and building-stock refresh rates, enabling executives to stress-test investment choices under alternative regulation and macro assumptions.
-
Actionable procurement timelines and compliance checklists framed by the latest code and standard changes, reducing retrofit risk and bid-won delivery surprises.
-
M&A screening matrices and financial overlays that align strategic fit with achievable synergies, informed by our bottom-up market model and concentration analysis.
Next steps and how to access the full intelligence
This briefing is an executive preview: it demonstrates the depth of our modelling and the strategic insight available, while preserving the full granularity of segment-by-segment forecasts, subregional analyses, and vendor scorecards for subscribers. If your 2026 planning requires precise product-level forecasts, channel-specific demand curves, or a prioritized list of acquisition targets and testable go-to-market pilots, access to the full report and accompanying data packs is required.
Contact PW Consulting to obtain the complete Smoke Alarms (Smoke Detector) Market report, the raw model files, and a tailored briefing workshop to translate the insights above into an executable 90-day plan aligned with your organization’s risk tolerance and strategic objectives.
For detailed analysis of this topic, please visit the official page: Smoke Alarms (Smoke Detector) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com