

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Magnesium Oxide Market to Reach USD 560.78 Million by 2032 at 6.12% CAGR

Magnesium Oxide Market 2026: Strategic Imperatives for Corporates — A PW Consulting Preview
Executive snapshot
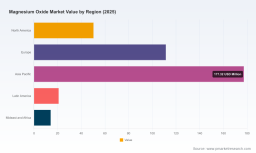
As the magnesium oxide (MgO) market moves from recovery to structurally differentiated growth, corporate leaders must recalibrate strategy across procurement, operations, and portfolio planning. PW Consulting’s latest market study — anchored on a 2025 base year and projecting through 2032 — shows the global MgO market expanding from an estimated USD 374.0 Million in 2025 toward a materially larger market by 2032, driven by an expected 6.12% CAGR across the 2026–2032 forecast window. This preview explains why that growth matters for 2026 decision cycles, what levers matter most, and how to prioritize near-term actions that protect margin and optionality while positioning for upside.
Magnesium Oxide Market
Why 2026 is a pivot year
-
Supply-side shock consolidation: Structural constraints in magnesite feedstock and targeted environmental enforcement within major producing jurisdictions have compressed available supply and triggered step-change price volatility. These dynamics are not transient; they reset cost baselines and create durable incentives for onshoring, vertical integration, and feedstock diversification.
Magnesium Oxide Market -
Policy and trade inflection points: Recent policy moves — including removal of select export incentives in major exporting countries and new regional processing targets in the EU — are altering competitive advantage across regions. Buyers and producers that assumed stable cross-border flows will need new sourcing playbooks.
Magnesium Oxide Market -
Customer mix and technical demand: End-markets such as refractories, industrial chemicals, and specialty high-purity applications are exhibiting distinct growth rates and margin profiles. The portfolio-level implications for producers and materials buyers mean different product and channel strategies are required simultaneously.
What the macro numbers mean for corporate strategy
Historical momentum shows a steady expansion from roughly USD 278 Million in 2020 to USD 374.0 Million in 2025. Under PW Consulting’s central forecast, the market scales further across the 2026–2032 horizon, reflecting a compound annual growth rate of 6.12% during that period and culminating in a significantly larger market by 2032. For executives, three practical implications follow:
-
Price-setting regimes have shifted: A higher baseline and amplified volatility compress gross margins for unhedged processors and OEMs. Early adoption of dynamic procurement and indexed pricing contracts is no longer optional for margin preservation.
-
Capex and brownfield expansions must be re-underwritten: With demand expected to grow steadily, selective capacity investments can still earn attractive returns — provided they are aligned to differentiated product grades and resilient feedstock strategies.
-
Strategic M&A windows are opening: Market concentration metrics indicate meaningful scale advantages among top incumbents; however, fragmentation across specialty niches creates attractive bolt-on targets for international players seeking rapid capability lift.
Industry dynamics: drivers and disruptors
-
Feedstock geography and concentration: A majority share of global magnesite reserves is concentrated in a single country. That endowment advantage, combined with episodic domestic regulatory enforcement (including localized shutdowns), has tightened the physical market and catalyzed rapid price appreciation in recent quarters.
-
Regulatory and fiscal policy shocks: Changes in export fiscal treatment for value-added MgO products have increased export costs for producers in affected jurisdictions, influencing international trade flows and creating short-term arbitrage opportunities for alternative suppliers.
-
Cost inflation and input pass-through: Notable manufacturers have reported material input-driven cost increases, which are being partially passed through to downstream markets. Buyers and processors must evaluate contractual mechanisms to share or hedge this inflation.
-
Regional industrial policy: European policy targets for domestic mining and processing are catalyzing investment incentives to onshore portions of the value chain — a strategic tailwind for suppliers able to meet local content and environmental thresholds.
Competitive landscape — who matters and why
The industry features a mix of global refractory leaders, specialty high-purity chemical suppliers, and sizable regional commodity producers. Market concentration is meaningful: the three largest players account for a substantial share of the market, and the top five represent an even larger portion — a structure that favors scale in commodity segments while leaving white space in high-margin specialty niches.
-
Global refractory and large-integrated players: Established names with global refractory portfolios and integrated magnesia capabilities benefit from scale, customer relationships with steel and cement producers, and stronger logistics networks. These players are best positioned to capture large project volumes and to invest in process upgrades that reduce per-unit costs.
-
Specialty high-purity suppliers: A subset of manufacturers focus on ultra-high-purity MgO for electronics, pharmaceuticals, and specialty chemical uses. Their technical differentiation supports higher margins and creates defensible niches that are less exposed to commodity cycles.
-
Domestic champions and regional producers: In markets where trade barriers, local content policies, or feedstock proximity matter, domestic producers retain preferential access. These companies are attractive partners for off-take agreements and joint ventures to secure local supply.
Recent market signals you cannot ignore
-
Capacity moves: Select U.S.-based producers announced meaningful capacity upgrades in 2025 to meet refractory demand, signaling confidence in sustained near-term demand and prompting competitors to reassess their own asset plans.
-
Commercial performance: Leading specialty business lines reported record revenues and margin improvements in 1Q 2025, underscoring the benefits of disciplined pricing and cost control in a tighter market.
-
Price volatility events: Localized production shutdowns tied to environmental enforcement caused price spikes in the supply belt; downstream manufacturers are facing margin pressure unless they adopt new sourcing or pass-through strategies.
Report practicalities — what PW Consulting provides (operationally oriented)
Our full market research is designed as a decision-support toolkit for 2026 planning cycles. Key deliverables include:
- Comprehensive supply-demand balance and historical series (2020–2025) with base-year normalization (2025).
- Scenario-driven forecasts (2026–2032) reflecting alternative policy, price, and feedstock outcomes, with sensitivity bands tied to input-cost and capacity-availability shocks.
- Plant-level capacity maps, cost-curves, and unit-cost benchmarking to identify lowest-cost-to-serve production footprints.
- Supplier scorecards and M&A heatmaps to prioritize targets by strategic fit, capability gaps, and integration risk.
- Procurement playbook: contract structures, hedging approaches, and short- to mid-term sourcing strategies to stabilize input costs and secure throughput.
- Regulatory risk matrix and trade-flow analysis to quantify exposure to policy shifts and to model near-term rerouting needs.
- Buyer and producer checklists for ESG-aligned investments in processing upgrades and decarbonization pathways.
Strategic recommendations for 2026 decision-makers
-
Prioritize feedstock security: Lock-in diversified off-take agreements and explore captive sourcing or joint ventures in low-risk jurisdictions to mitigate single-country exposure.
-
Reprice smart: Shift toward flexible pricing contracts (index-linked, cost-plus collars) that protect margins while remaining competitive with spot market swings.
-
Target value-over-volume investments: Allocate capital to upgrades that enable higher-grade or niche products rather than chasing commodity tonnage that faces margin compression.
-
Accelerate supplier consolidation where scale matters: Use targeted acquisitions to secure market share in commodity segments while preserving separate strategies for high-purity niches.
-
Embed regulatory scenario planning into capex approvals: Stress-test business cases against trade-policy shifts and local environmental constraints to avoid stranded assets.
-
Invest in circularity and alternative chemistries: Explore opportunities in recycling, by-product valorization, and substitution to reduce feedstock dependency and meet customer ESG requirements.
How to use our full study
This preview highlights the strategic inflection points that should shape 2026 commitments. The full PW Consulting Magnesium Oxide Market report delivers the granular intelligence you need to act: detailed forecasts by grade and application, supplier-level capacities, actionable M&A candidates, and downloadable decision tools. To maintain competitive advantage, procurement, operations, and corporate development teams should integrate these outputs into their Q3 2026 planning cycles.
Conclusion — the window of strategic opportunity
Market expansion, tighter feedstock dynamics, and policy-driven rebalancing create a narrow window in 2026 for companies to lock in advantaged positions. Whether your objective is to secure feedstock, protect margins, or selectively expand, the choices made this year will compound through the forecast horizon. PW Consulting’s full report supplies the analytical foundation and operational playbooks to make those choices with confidence.
Next steps
Contact PW Consulting to arrange a briefing, access the full dataset, and obtain tailored advisory support. Our team will demonstrate how the forecast scenarios and supplier scorecards map to your P&L, balance-sheet constraints, and strategic ambitions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Magnesium Oxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com