

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Hydrogen & Fuel Cells Market Poised for 27.56% CAGR to USD 244.85M by 2032

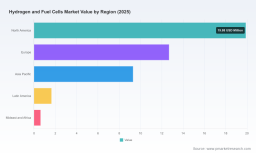
Hydrogen and Fuel Cells Market — Strategic Imperatives for 2026
As organizations plan capital allocation and strategic moves for 2026, the hydrogen and fuel cells sector presents both an outsized growth opportunity and a set of execution risks that will determine winners and losers over the next decade. PW Consulting’s new Hydrogen and Fuel Cells Market study frames that opportunity with a data-driven market model: the global market expands from USD 23.02 Million in 2020 to USD 44.12 Million in our 2025 base year and is forecast to reach USD 244.85 Million by 2032, reflecting a compound annual growth rate (CAGR) of 27.56% across the 2026–2032 forecast period. This trajectory is not linear — it is driven by discrete inflection points in manufacturing scale-up, regulatory alignment, and hydrogen value-chain maturation — and these are the levers our clients must master in 2026.
Hydrogen and Fuel Cells Market
Why this study matters for 2026 decision-makers
-
Investment timing: High growth does not mean low risk. Rapid market growth amplifies both upside and downside; a 27.56% CAGR implies large near-term upside if technology and supply chain risks are managed, but also magnifies the consequences of mis-timed capacity or incorrect product bets.
Hydrogen and Fuel Cells Market -
Operational priorities: The window for cost leadership is narrow. Companies that secure manufacturing scale, qualified suppliers, and repeatable quality processes in 2026 will create a durable margin advantage as volume ramps.
Hydrogen and Fuel Cells Market -
Policy and commercial readiness: Incentive programs, safety certifications, and procurement frameworks are transitioning rapidly. Firms that are proactive in regulatory engagement and that design products for current and emerging certification regimes capture procurement pull-through.
-
Competitive dynamics: The market displays moderate concentration — the top three players account for a meaningful portion of revenue and the top five for a majority share — creating both collaboration and competitive displacement opportunities.
What the PW Consulting report delivers — practical content for action
- Proprietary market-sizing model and scenario engine (base, accelerated, downside) calibrated to 2020–2025 historicals and 2026–2032 forecasts.
- Cost and manufacturing scale playbook: stepwise unit-cost curves, break-even volumes, and a manufacturing ramp template for OEMs and suppliers.
- Go-to-market decision framework for product-market fit across mobility, stationary, and portable segments (with buyer economics and procurement triggers).
- Regulatory and incentives matrix covering major jurisdictions and certification pathways, plus a tactical compliance checklist for product launches.
- Competitive landscaping: granular profiles of incumbent and emerging players, capability maps, and likely strategic moves (JV, licensing, M&A scenarios).
- Supply-chain risk register, including critical raw-material exposure, single-source vendor mapping, and hedging strategies.
- M&A and partnership playbook with a shortlist of target archetypes and valuation heuristics tailored for 2026 market conditions.
- Executive decision trees and 90/180/365-day operational roadmaps to convert strategic intent into measurable milestones.
Competitive landscape — five players shaping 2026 competitive choices
-
Ballard Power Systems (Vancouver) — Strong in PEM fuel cell stacks and systems for heavy-duty transportation and stationary use. Ballard’s engineering depth and proven field deployments make it a go-to partner for OEMs seeking integration support. Strategic focus for 2026: convert engineering leadership into reliable high-volume production partnerships; risk: capital intensity of scaling manufacturing lines.
-
Bloom Energy (San Jose) — A leader in solid oxide fuel cell (SOFC) onsite power with notable commercial footprints in data centers and industrial power. Bloom’s pack-level experience positions it for scale in high-value stationary applications; strategic priority: optimize uptime economics and service models to expand into utility-scale and microgrid markets.
-
Plug Power (Latham) — Focused on hydrogen fuel cell systems for material handling, stationary backup and industrial applications. Plug’s integrated approach across stack, fuelling and service creates a vertical value proposition. For 2026, execution of manufacturing efficiencies and channel expansion into new industrial customers will be decisive.
-
FuelCell Energy (Danbury) — Specialist in carbonate fuel cell systems for combined heat & power and industrial use cases, with a growing role in hydrogen production pathways. Strengths include project execution for microgrids; corporate risk centers on financing long-duration projects and optimizing lifetime service economics.
-
Nuvera Fuel Cells (Billerica) — Developer of hydrogen fuel cell engines and portable power for off-road and material handling. Nuvera’s positioning in industrial mobility and recent public-sector funding support its path to higher-volume production; in 2026 the priority is converting funding into repeatable manufacturing processes and broader product certification.
These players illustrate the diversity of technology pathways — PEM, SOFC, carbonate — and business models — stack suppliers, systems integrators, and project developers. The market’s CR3 and CR5 concentration metrics indicate meaningful leader presence but also ample space for specialization, regional champions, and vertical integrators.
Recent industry signals and why they matter for 2026
-
Large-scale commercial orders and battlefield-proven deployments signal strengthening demand in high-value, mission-critical use cases. Such awards accelerate supplier validation cycles and unlock follow-on contracts.
-
Certification progress for commercial fuel cell units in North America is lowering market-entry barriers for stationary applications. Expect procurement volumes to rise where certification aligns with incentives and utility interconnection standards.
-
Public funding and incentive programs are actively being used to de-risk manufacturing scale and accelerate commercialization. Companies that align product specifications to incentive eligibility will win earlier procurement commitments.
-
Independent technical assessments point to rapidly improving unit economics as manufacturing volumes rise; OEMs that lock in supplier agreements and scaleable production capacity will capture the lion’s share of margin improvements.
Key strategic actions for 2026
-
Prioritize near-term pilots that de-risk the three levers of commercialization: product reliability, supply-chain continuity, and route-to-market economics. Use pilots to validate TCO versus incumbent technologies in real procurement settings.
-
Secure strategic supply agreements for critical components early. The lead times and qualification cycles for membrane electrode assemblies, catalysts and power electronics will determine the effective ramp rate of manufacturing.
-
Design products to current and anticipated certification standards. Certification-ready product architectures shorten sales cycles with institutional buyers and unlock incentive programs.
-
Adopt a triple-pathway R&D portfolio: incremental cost-reduction, integration and serviceability improvements, and a blue-sky program for next-generation chemistries. Allocate resources across these paths proportionally to risk appetite and time horizon.
-
Execute a disciplined capital and partnership strategy: use joint ventures, toll-manufacturing, and strategic OEM partnerships to share scale-up costs while retaining core IP where it creates durable differentiation.
Immediate 90/180/365 day roadmap
-
0–90 days: Complete a rapid internal assessment using our scenario model, identify one pilot program, and begin supplier qualification for critical subassemblies.
-
90–180 days: Secure at least one strategic supply or manufacturing partner; begin certification alignment and file for applicable incentive programs; initiate procurement dialogues with anchor customers.
-
180–365 days: Ramp pilot to commercial scale, finalize manufacturing footprint decisions informed by real-world unit costs, and pursue targeted M&A or JV to fill capability gaps.
Conclusion — the strategic vantage point for 2026
By 2026, the hydrogen and fuel cells market will be defined as much by execution capability as by technology choice. Our forecasted scale — a multi-fold increase from 2025 to 2032 at a 27.56% CAGR — underlines the urgency for executives to translate strategy into manufacturing commitments, policy engagement and commercial proof points. PW Consulting’s Hydrogen and Fuel Cells Market study provides the empirical models, tactical playbooks, and competitor insights needed to make those moves with confidence — while preserving the proprietary segmentation, pricing curves and granular case models that will inform concrete investment decisions.
For the detailed segmentation data, unit-cost curves, and the full competitive dossier that inform the 2026-ready playbooks, review the full report on our website and schedule a strategy briefing with PW Consulting’s hydrogen practice.
For detailed analysis of this topic, please visit the official page: Hydrogen and Fuel Cells Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com