

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sputtering Target Market to Reach USD 5,740M by 2032 at 5.63% CAGR

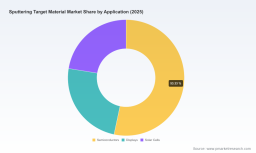
Sputtering Target Material Market — Strategic Outlook for 2026 Decision-Making
As PW Consulting’s lead industry analyst, this briefing frames the strategic value of our new Sputtering Target Material Market study for executives making critical resource-allocation and supply-chain decisions in 2026. The market we model spans high-purity metal, alloy and compound targets used across semiconductors, displays and thin-film energy applications. Using 2025 as the base year, our top-line sizing shows a market of USD 3,950 Million with a compound annual growth rate of 5.63% through the forecast horizon (2026–2032). By 2032, the addressable market is projected to approach USD 5,740 Million under the central scenario. The historical series (2020–2025) illustrates steady expansion with episodic volatility tied to raw-material swings and end-market cyclicalities — context that shapes the pragmatic, actionable intelligence embedded in the full study.
Sputtering Target Material Market
Why this study matters for decisions in 2026
- Timing: 2026 is a pivot year for capital allocation across the sputtering target value chain. Several tier‑1 suppliers are commissioning capacity upgrades or new production lines; wafer fab buildouts and display investments in upstream markets are also influencing near-term demand profiles.
- Margin management: Volatility in key feedstocks and the compression of yield tolerances at advanced semiconductor nodes make procurement strategy and product mix optimization top priorities for both target manufacturers and their OEM customers.
- Strategic optionality: The combination of material innovation (compound targets, refractory metals), manufacturing automation and evolving environmental regulations creates windows for consolidation, vertical integration and targeted green investments that can secure durable competitive advantage.
How to use the report: practical, decision-focused deliverables
The PW Consulting report was designed as an operator’s manual for 2026 strategic planning, not an academic paper. Key actionable elements include:
Sputtering Target Material Market
- Market sizing and demand flows with a validated top‑down and bottom‑up methodology (base year 2025; forecast 2026–2032) and scenario outputs for upside, central and stress cases.
- Supply‑side mapping across the full value chain: refining, alloying, machining/bonding, finishing and distribution, including lead times and bottleneck nodes.
- Vendor scorecards and capability matrices covering purity grades, format (planar/rotary/rotatable), finishing services, and in‑house vs. outsourced competencies.
- Pricing benchmarks and margin waterfall templates that translate feedstock moves into finished‑product margin outcomes.
- Decision tools: a downloadable financial model (editable), an M&A target shortlist with strategic rationale, a three‑year capex planning template, and a regulation & compliance checklist for e‑waste and secondary recovery.
- Scenario playbooks: ready-to-deploy strategies for supply shocks (material price spike), demand slippage, and regulatory tightening — each with recommended actions by function (procurement, operations, R&D, legal).
We intentionally present high-level conclusions here; detailed subsegment datapoints, supplier market shares by specific product family and regional application splits are reserved for the full report and the interactive model on our site.
Sputtering Target Material Market
Market dynamics shaping 2026 decisions
- Advanced-node semiconductor scaling and heterogeneous integration are increasing demand for specialty and ultra‑high‑purity targets. This technical demand raises barriers for new entrants while rewarding suppliers that can guarantee traceability and ultra‑low impurity footprints.
- Display and solar cell thin-film trends continue to provide steady incremental demand; however, maturity of those markets means growth is more dependent on material substitution and process optimization than volumetric expansion alone.
- Raw material volatility is now a first‑order risk. Tantalum and other strategic feedstocks experienced meaningful price jumps recently, directly pressuring margins at manufacturers that lack hedging or vertical integration strategies.
- Regulatory pressures are increasing the cost and complexity of secondary recovery. Stricter e‑waste treatment rules reduce the practical recovery rates of some critical materials and reinforce the advantage of firms with internal recycling or long-term offtake arrangements.
- Geopolitical concentration of certain critical inputs creates intermittently acute cost and supply risks. Firms that proactively diversify supply sources or invest in local refining capacity will reduce exposure in 2026–2028 cycles.
Competitive landscape — capability and risk mapping
The supplier landscape is a mix of highly specialized material houses, large integrated metallurgical firms and equipment-integrated providers. Our report includes qualitative and quantitative profiles; below are distilled strategic observations on the core players that shape market dynamics.
- Materion Corporation — Strengths: ultra‑high purity tantalum capabilities and recent expansion of finished-target production capacity in South Korea position Materion for growth in advanced-node memory and logic. Implication: strong leverage to premium pricing where purity certs are non‑negotiable.
- JX Advanced Metals Corporation — Strengths: vertical integration from base refining to finished targets, and aggressive recent capacity expansions. Implication: timing and scale of their new lines are likely to shift competitive pricing dynamics and compress lead times for some materials.
- Plansee SE — Strengths: deep expertise in refractory metals and compound targets relevant to optical and high‑temperature applications. Implication: defensible margins in specialty niches, but dependent on cyclical capital markets in some end applications.
- Tosoh Corporation — Strengths: integrated refining and alloying capabilities; breadth across pure metal and alloy products. Implication: resilience to feedstock swings if refinery throughput is optimized.
- Umicore Thin Film Products — Strengths: experience in both precious and non‑precious thin‑film materials and strong process control. Implication: positioned to capture higher‑value thin‑film segments that require precise stoichiometry.
- Kurt J. Lesker Company — Strengths: responsiveness to R&D and low-volume specialty needs. Implication: attractive partner for innovation programs and qualification runs where speed and flexibility matter.
- American Elements — Strengths: ultra‑high purity, large-area rotatable targets. Implication: suitable partner for volume producers and large-area display applications requiring uniformity.
- ULVAC, Inc. — Strengths: integration of sputtering targets with vacuum deposition equipment. Implication: potential to capture downstream value by bundling consumables with capital equipment.
- Hitachi Metals, Ltd. — Strengths: R&D in new copper variants and thermal/electrical performance optimization. Implication: potential first-mover advantage for next‑generation copper-based applications.
- Vital Materials — Strengths: end‑to‑end control from refining to machining; strong logistics presence in Asia. Implication: reliable supplier for OEMs favoring single‑source contracts with traceable supply chains.
Market concentration indicators in our study point to a moderated level of consolidation at the top tier, making partnerships, co‑investment and targeted M&A attractive levers for both incumbents and private capital in 2026.
Key risks and leading indicators to monitor
- Raw material price movements (tantalum, indium, ruthenium): sudden price spikes are an immediate margin risk. Indicator: futures/spot price divergence and inventory drawdown at exchanges/suppliers.
- Policy and regulatory announcements on e‑waste and export controls: these can curb secondary recovery and constrain supply. Indicator: regulatory filings and enforcement actions in major recycling hubs.
- Capacity commissioning timelines among major suppliers: earlier-than-expected ramp‑ups compress pricing; delayed ramps tighten supply. Indicator: supplier CAPEX disclosures and site commissioning notices.
- Wafer fab utilization and new fab announcements: these drive underlying wafer demand and hence sputtering target consumption. Indicator: public wafer fab capex, equipment order backlogs, and major OEM demand signals.
- Technological substitution: new deposition approaches or material chemistries could alter demand mixes. Indicator: patent filings, consortium research outputs, and qualification cycles at leading fabs.
Recommended strategic plays for 2026
- Manufacturers: prioritize automation and flexible lines that can handle mixed-product runs; invest selectively in vertical integration for critical feedstocks or lock long-term offtake to stabilize margins.
- Chipmakers and OEMs: implement multi-supplier qualification frameworks and consider co-investing in target production capacity to secure supply and negotiate price stability mechanisms.
- Investors: favor targets with proven high‑purity process control, secured feedstock pathways, and diversified end‑market exposure; run downside stress tests against material price spikes and regulatory shocks.
- Policy makers and recyclers: support scaled secondary recovery through clear regulation and incentives, which will reduce supply concentration risks and long‑term price volatility.
Next steps and access to the full intelligence suite
This briefing surfaces the strategic contours executives need to act in 2026 while deliberately withholding the granular subsegment tables, regional and application-level shares, and the interactive financial model that are part of the full PW Consulting release. Those detailed datapacks — including our supplier market-share matrices, product‑family growth curves and downloadable scenario models — are available on the report page and are essential for transaction diligence, procurement renegotiations, and capex prioritization.
To translate these insights into a tailored 90‑day action plan for your organization, our advisory team offers targeted workshops that integrate your internal cost models with the PW Consulting market model. Contact us through the PW Consulting report page to schedule a briefing and obtain the complete dataset and model access.
For detailed analysis of this topic, please visit the official page: Sputtering Target Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com