

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Wine market set to hit USD 610B by 2032 at 5.6% CAGR

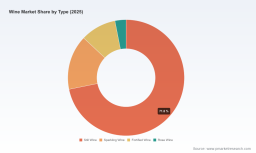
Wine Market 2026 Strategic Brief — A PW Consulting Preview
As PW Consulting’s lead industry analyst, I present this strategic preview of our new Wine Market report — a decision-grade briefing designed to shape bold, actionable corporate strategies in 2026. The global wine market is reasserting growth momentum after a period of structural shifts. Our analysis integrates a refreshed baseline (base year 2025), a five-year historical window (2020–2025), and a detailed forecast horizon to 2032. Key topline metrics: the market is growing at a compound annual growth rate (CAGR) of 5.6% in our forecast, with a clear pathway to materially larger aggregate demand by 2032.
Wine Market
Why this report matters for 2026 decision cycles
-
Timing: 2026 is a pivot year. The industry is responding to simultaneous supply-side relief (softening grape prices in some origins), trade-policy friction, and renewed consumer appetite for premium experiences. These combined forces create a narrow set of windows for pricing resets, channel reallocation, and portfolio reshaping.
Wine Market -
Scale: Our market topology demonstrates steady expansion from the 2020 base through 2025 and beyond. That expansion is not uniform — it is driven by differentiated channel dynamics and value-per-bottle migration that require nuanced playbooks rather than one-size-fits-all responses.
Wine Market -
Concentration and competitive pressure: The category exhibits moderate consolidation at the top of the value chain. Leading players control a sizable share of the market (our concentration metrics show meaningful CR3 and CR5 footprints), which shapes supplier bargaining power, distribution economics, and M&A calculus.
What the PW Consulting Wine Market report delivers (practical, implementable content)
-
Actionable market-sizing and scenarios — We provide a defensible baseline (2025) and three operational scenarios through 2032 driven by macro shocks, tariff regimes, and consumption shifts. These scenarios map to concrete revenue, margin, and channel outcomes to inform budgeting and capital allocation across a 3–7 year horizon.
-
Go-to-market playbooks — Tailored GTM options for premium, value, and innovation-led portfolios across retail, on-premise, and direct-to-consumer (DTC) channels. Each playbook includes expected ROI profiles, typical investment timelines, and risks to watch.
-
Supply-chain stress tests — Simulations that stress-test sourcing, crush-season variability, and packaging lead times under alternate grape-price and logistics-cost trajectories. These identify specific hedging and partnership levers that can preserve gross margin under price volatility.
-
Portfolio and pricing toolkit — A structured approach to price architecture, brand-tiering, and SKU rationalization informed by consumer segmentation and elasticity insights. This is paired with a decision matrix for SKU proliferation versus SKU optimization.
-
M&A and partnership guidance — A prioritized shortlist of archetypal targets (by capability, geography, and channel access), integration playbooks, and expected synergies — designed to accelerate inorganic growth while mitigating integration risk.
-
Regulatory and trade-impact playbook — Scenario-based assessments of tariff pathways and compliance frameworks, with mitigation options that include local sourcing, re-routing, and pricing compensation strategies.
Strategic implications from the headline data
-
Growth trajectory supports investment but demands selectivity. With the market expanding at ~5.6% CAGR in our base forecast, executives can justify capex and strategic M&A to capture share — provided these moves are targeted at durable margins and distribution advantaged positions.
-
Channel rebalancing is an imperative. As consumers continue to fragment spending across experiential and convenience channels, firms must rebalance investments between on-premise premiumization and high-efficiency retail/DTC funnels.
-
Cost volatility requires active sourcing strategies. Recent and preliminary industry indicators point to easing input costs in several origins, but the trajectory is uneven. Buyers and producers should lock in flexible contracts, explore blended sourcing, and accelerate cost-to-serve reduction programs.
-
Regulatory shocks alter competitive landscapes. Trade measures implemented in prior years have reshaped competitive dynamics; companies with diversified sourcing and localized production alternatives are better positioned to protect margins and shelf presence.
Competitive landscape — what leading firms are doing
-
E. & J. Gallo Winery — As the world’s largest family-owned winery, Gallo operates across the full spectrum of price tiers and channels. Their dual emphasis on premium brand stewardship and high-volume retail/value delivery provides a resilient revenue base. For competitors, Gallo’s scale matters: it accelerates private-label partnerships, drives route-to-market leverage with major retailers, and enables supply-chain optimizations that compress unit costs.
-
The Wine Group — With a strong foothold in everyday and value-oriented formats (including boxed wine and mass-market brands), The Wine Group exemplifies the defensive playbook: broad portfolio breadth, cost-efficient packaging innovations, and channel penetration focused on high-velocity retail. Their model highlights the margin trade-offs between scale-driven cost leadership and the need for constant SKU rationalization.
-
Jackson Family Wines — A premium-focused estate operator with global vineyard footprints, Jackson illustrates the growth premium for terroir-differentiated portfolios and experiential DTC channels. Their strengths are in brand storytelling, estate tourism, and high-margin reserve bottlings — an archetype for companies pursuing premiumization and consumer loyalty via experiential assets.
Near-term developments and industry signals to act on in 2026
-
Competition outcomes and awards season (early 2026) matters for short-term premium demand and retailer assortment. Recent competition results have amplified visibility for certain domestic and import producers, temporarily increasing demand for awarded SKUs and pressuring supply for adjacent tiers.
-
Raw-material signals — Producer Price Index movements and national crush reports indicate that grape input prices have moderated in selected origins. These signals create opportunities to reprice or invest in margin-enhancing initiatives, but they also demand caution: the moderation has not been uniform across all geographies.
-
Regulatory risk — Reciprocal tariffs and trade policy shifts implemented in recent years have realigned sourcing economics. Companies should update landed-cost models, renegotiate terms with distributors, and stress-test price elasticity should tariffs persist or escalate.
Practical 90‑day actions for executives
-
Run a rapid pricing and promotion audit: identify SKUs with the highest margin sensitivity to input-cost swings and test limited price adjustments in controlled markets.
-
Lock in flexible supply agreements: prioritize contracts with optionality (volume bands, call/put features) in key grape-sourcing regions and packaging suppliers.
-
Reassess channel investments: allocate a measurable fraction of incremental marketing dollars to DTC conversion experiments and on-premise experiential pilots that can demonstrate ROAS within 6–9 months.
-
Triangulate M&A targets: use our shortlist framework to map high-priority targets that add distribution or premium credentials without overleveraging balance sheets.
What we intentionally withhold here — and why
This preview is deliberately structured as a “trailer”: it surfaces methodology, strategic implications, and executive actions while withholding the granular splits and proprietary subsegment matrices that underpin our recommendations. The full report contains detailed regional and channel breakdowns, elasticity matrices, SKU-level margin modeling, and prioritized target lists — all essential for transaction due diligence, market-entry decisions, and operating model redesign. Those high-value datasets and scenario worksheets are available in the full PW Consulting Wine Market offering.
How PW Consulting supports 2026 strategy execution
-
Data-to-decision workshops — Rapid workshops that thread our model outputs into executive planning cycles and capital allocation processes.
-
Custom scenario modeling — Tailored stress tests (trade disruptions, weather/climate shocks, demand shocks) to quantify downside risk and identify hedges.
-
Integration and PMI support — End-to-end deal support for acquisitions, joint ventures, and distribution partnerships, including synergy tracking and operating-model redesign.
In short, 2026 is a year for selective aggression: firms that combine disciplined portfolio management, flexible sourcing, and targeted channel investment will capture disproportionate share gains in a market that is expanding but becoming more complex. Our full Wine Market report equips leaders with the granular diagnostics and executable playbooks required to convert this opportunity into sustained advantage.
To obtain the complete analysis, including proprietary subsegment datasets, scenario workbooks, and the prioritized M&A shortlist, please access the PW Consulting Wine Market report on our website or contact our industry practice team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Wine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com