

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cold Chain Logistics to grow at 12.97% CAGR (2026-2032)

Cold Chain Logistics Market: Strategic Imperatives for 2026 Decision‑Makers
Executive preview
The cold chain logistics sector is entering a decisive growth chapter. Our market modeling — calibrated to a 2025 base year and tracking historical performance from 2020 through 2025 — shows a multi‑year expansion trend that continues into the 2026–2032 forecast window at a compound annual growth rate of 12.97%. From an already substantial global footprint in 2025, the market is projected to expand materially over the coming six years. For executives preparing capital allocation, strategic partnerships, or M&A playbooks in 2026, understanding the drivers behind this trajectory is essential.
Cold Chain Logistics Market
Market trajectory and strategic implications
Between 2020 and 2025 the market demonstrated strong acceleration, reflecting both demand‑side forces (expanded perishable food trade, rising pharmaceutical cold chain needs) and supply‑side evolution (new capacity, automation, and integrated logistics services). With 2026 marking our forecasted inflection point as the market pushes toward the mid‑single to high‑single‑hundreds‑of‑billions range in subsequent years, the strategic implications are clear:
Cold Chain Logistics Market
- Capacity planning must be anticipatory. Firms that align capex cycles with projected demand curves will avoid costly reactive buildouts or lost service opportunities.
- Technology and traceability investments are no longer optional; they materially affect access to regulated segments and premium customers.
- Fragmentation persists at the supplier level, creating opportunities for scale players, specialized regional operators, and vertically integrated offers to capture premium margins.
Why 2026 is an inflection moment
Three converging dynamics make 2026 a strategic hinge year for cold chain participants:
Cold Chain Logistics Market
- Regulatory tightening. New traceability mandates require digital monitoring and documented chain‑of‑custody for high‑risk perishable products. Compliance timelines mean that companies must move from pilots to enterprise deployments within quarters, not years.
- Technology mainstreaming. Robotics, robotics‑enabled storage automation, IoT sensors, and cloud‑native visibility platforms have moved from niche proofs‑of‑concept to scalable operational levers that materially reduce per‑unit handling costs and shrink spoilage risk.
- Capital and infrastructure expansion. Public grant programs and private investment are expanding temperature‑controlled capacity in targeted corridors and hubs; this creates short‑term pockets of overcapacity alongside long‑term network realignments.
What PW Consulting’s Cold Chain Logistics Market study delivers (practical contents)
This study is structured for leaders who must translate market intelligence into executable strategy. Key deliverables include:
- Robust market sizing and growth scenarios — base year 2025, historical series (2020–2025), and probabilistic forecasts through 2032.
- Demand heatmaps and network optimization tools that show where incremental capacity delivers the highest ROI under multiple demand and disruption scenarios.
- TCO and ROI templates for automated warehousing, refrigerated transport, and thermal packaging investments that allow quick sensitivity testing of CapEx vs. OpEx tradeoffs.
- Regulatory compliance playbooks (including digital traceability checklists and ISO alignment guidance) to operationalize FSMA‑class traceability requirements and evolving international standards.
- Vendor selection frameworks, technology evaluation scorecards, and contractual templates for outsourcing vs. insourcing decisions.
- M&A screening matrices and integration blueprints focused on value capture in a market where the top few players comprise a modest share of total volume — creating consolidation opportunities for strategic buyers.
- Executive‑ready dashboards and KPI sets to monitor spoilage, on‑time temperature compliance, utilization, and energy efficiency across mixed portfolios.
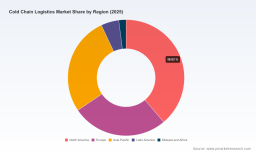
We intentionally omit granular regional and application splits in this preview; the full report provides the underlying segment detail and downloadable models for subscriber use.
Competitive landscape — positioning and strategic moves
The cold chain ecosystem combines global integrators, specialized providers, and highly automated newcomers. The market concentration metrics reflect a fragmented competitive field: a small handful of large players influence pricing and standards, but a broad long tail of regional specialists participates in local fulfillment and niche product flows.
- Lineage Logistics — As a temperature‑controlled 3PL with extensive global reach, Lineage leverages scale, data integration, and a broad warehouse network to serve high‑volume food customers. Their strengths lie in cross‑border orchestration and integrated service bundles.
- Americold Logistics — Operating as a REIT‑aligned cold storage owner‑operator, Americold’s model emphasizes real estate optimization and long‑term customer contracts, making them a key landlord and operations partner for food supply chains.
- United States Cold Storage (USCS) — With deep historical presence, USCS combines legacy market relationships with incremental modernization; their value is rooted in trusted service continuity for major food distributors.
- NewCold — Distinguished by aggressive automation and large‑scale, purpose‑built automated warehouses, NewCold is advancing throughput and energy efficiency benchmarks that challenge traditional labor‑centric models.
- DHL, UPS, Maersk, DSV, Kuehne + Nagel, CEVA — These global logistics integrators are expanding cold chain offerings as part of broader end‑to‑end supply chain propositions, combining transport, customs, and cold storage in single contracts to simplify retailer and manufacturer sourcing.
- C.H. Robinson, Burris Logistics, Preferred Freezer Services — These players maintain differentiated positions: supply chain orchestration, regional specialization, and frozen‑food warehousing respectively — all attractive acquisition targets or partners for firms seeking immediate capability expansion.
Recent facility investments and launches across the industry — from automated warehouses to IoT‑equipped regional hubs — underscore a dual trend: incumbents defending share through capital upgrades, and new entrants using automation to undercut operating costs. These moves create both competitive pressure and partnership opportunities for strategic buyers and suppliers.
Regulatory and operational risk landscape
Two regulatory trends deserve immediate attention. First, new traceability mandates require digitized, auditable records for specific high‑risk perishable items. Second, international standards for temperature monitoring and carriage are converging, raising minimum compliance bars for cross‑border flows. Operationally, rising labor costs and skill scarcity are accelerating automation investments — but automation introduces integration and reliability risks that must be managed through staged rollouts and vendor governance.
Actionable strategic priorities for 2026
For commercial and operational leaders, the following priorities should guide 2026 decisions:
- Accelerate traceability deployments tied to revenue streams: prioritize segments where regulatory compliance unlocks premium contracts.
- Adopt a rent‑vs‑buy decision framework for capacity: use our network optimization tools to identify corridors where owned capacity yields long‑term advantage versus markets better served by 3PL partners.
- Invest in targeted automation pilots with explicit payback gates: pair automation with workforce upskilling and redundancy planning to protect throughput during integration.
- Pursue bolt‑on acquisitions that close capability gaps (automation, last‑mile cold transport, or regional warehousing) rather than market share for its own sake.
- Standardize KPIs across partners and customers to reduce dispute costs and improve collaborative planning.
- Design energy and sustainability programs that reduce operating volatility and meet buyer ESG expectations — refrigeration efficiency will be a differentiator in tender processes.
Why PW Consulting’s study matters to your 2026 planning
Our study blends top‑down market modeling with bottom‑up operational benchmarks and executable tools. Subscribers receive the full dataset, scenario models, and a prioritized implementation roadmap tailored to four strategic archetypes: owner‑operator, asset light integrator, specialist regional champion, and investor/portfolio operator. The executive preview here highlights trends and implications — core subsegment numbers, regional and application splits, and proprietary company market share estimates are intentionally reserved for the full report and client briefings.
Next steps
If your board is setting capex for 2026, preparing for regulatory compliance, or evaluating M&A options, now is the time to convert strategy into a 12–24 month execution plan. Access the full Cold Chain Logistics Market study to obtain the detailed regional and application intelligence, downloadable optimization models, and a prioritized list of transactions and partnership targets curated for immediate action. Contact PW Consulting for a tailored briefing and to receive the subscriber toolkit that turns the study’s forecasts into executable projects.
For detailed analysis of this topic, please visit the official page: Cold Chain Logistics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com