

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hotmelt Adhesives to hit USD 12.9B by 2032 at 5.32% CAGR

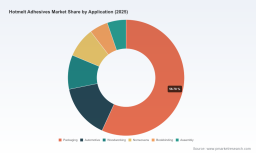
Hotmelt Adhesives Market Outlook — Strategic Imperatives for 2026
As PW Consulting’s senior industry analyst, I present a concise strategic preview of our Hotmelt Adhesives Market study (base year 2025, historical 2020–2025, forecast 2026–2032). This briefing is designed to equip executives, investors, product leaders and supply‑chain strategists with the high‑level intelligence they need to set 2026 priorities. It demonstrates the analytical depth of our research while intentionally withholding the detailed segment tables and numerical splits that are included in the full report — those granular insights remain behind the paywall to preserve the utility of this preview as a “trailer”.
Hotmelt Adhesives Market
Snapshot: Market Scale and Trajectory
The hotmelt adhesives market has moved from an estimated USD 7,166 million in 2020 to USD 8,950 million in 2025, underpinned by steady demand across packaging, industrial assembly, woodworking and hygiene segments. Our forecast projects continued expansion through the 2026–2032 horizon, with an expected market value of approximately USD 9,428 million in 2026 and reaching roughly USD 12,895 million by 2032 — reflecting a compound annual growth rate of about 5.32% over the forecast period.
Hotmelt Adhesives Market
Two structural observations emerge from the topline data: first, the market’s growth is durable, driven by secular shifts in packaging sustainability and light‑weighting in automotive and electronics; second, concentration ratios indicate a fragmented competitive landscape (CR3 ≈ 25.3%, CR5 ≈ 38.6%), leaving strategic room for premium positioning, regional champions, and consolidation plays.
Hotmelt Adhesives Market
Why This Study Matters for 2026 Decisions
- Regulatory inflection points demand urgency: New packaging regulations and chemical restrictions across major markets are accelerating product reformulation and creating short time windows to certify new low‑VOC, recyclable, and PFAS‑free systems.
- Input cost volatility is a business risk: Feedstock swings (notably crude oil-driven volatility) are increasing the operational and margin risks of EVA and polyolefin‑based systems — active hedging and alternative raw material strategies will be decisive.
- Product innovation is a route to premium value: Advances in reactive PUR, low‑viscosity polyamides and bio‑based chemistries are unlocking higher margin applications in electronics, appliance assembly and performance packaging.
- Fragmentation creates M&A and partnership opportunities: With sub‑40% CR5, there is tactical space for bolt‑on acquisitions, exclusive supply agreements, and co‑development partnerships to scale differentiated technologies quickly.
Key Market Dynamics — Drivers and Headwinds
- Raw material pressures: Since 2020 benchmark crude oil prices have shown dramatic swings, periodically trading between approximately USD 60 and USD 130 per barrel. Those swings have materially impacted EVA and polyolefin feedstocks, altering cost curves and forcing suppliers to re‑price formulations or absorb margin compression.
- Regulatory acceleration: North American and European frameworks — from U.S. EPA VOC guidance to the EU’s Packaging and Packaging Waste Regulation and PFAS restrictions — are accelerating demand for low‑VOC, non‑fluorinated, and recyclable adhesive solutions. Simultaneously, REACH/ECHA restrictions on solvent chemistries are nudging industrial customers away from solvent‑borne systems toward hotmelt alternatives.
- Sustainability requirements: Brand owners and packaging converters are asking for adhesives that enable recycling streams or facilitate mechanical/chemical recycling. This is stimulating investment in bio‑based chemistries and biodegradable solutions, but also raising questions about lifecycle trade‑offs and certification pathways.
- Application evolution: Automotive light‑weighting, higher throughput packaging lines, and miniaturized electronics assembly each impose different performance demands (temperature resistance, bond flexibility, set time), creating a landscape where one‑size‑fits‑all products are increasingly uncompetitive.
Competitive Landscape — Strategic Profiles and Implications
The market combines global diversified chemical majors, adhesive specialists and regional suppliers. Below is a strategic read on the leading participants covered in our study and recent moves that illustrate the direction of competition.
- Henkel Adhesive Technologies (Duesseldorf): Henkel’s Technomelt portfolio — including recent launches (e.g., ultra‑low viscosity polyamide and in‑process debonding PUR systems in 2026) — demonstrates a push toward high‑performance, application‑specific solutions for electronics and appliance assembly. Strategy implications: invest in application R&D and co‑engineering to stay embedded with OEMs.
- 3M Company (St. Paul): 3M leverages strong materials science and cross‑industry platforms (Scotch‑Weld range) to serve electronics and automotive. Their advantage is systems integration and channel breadth; competitors should anticipate rapid commercialization cycles and high expectations for technical support.
- Dow Inc. (Midland): Dow’s role as both raw material provider and formulator creates vertical leverage. Their influence on resin availability and pricing is an important input to scenario planning for converters and specialty formulators.
- H.B. Fuller (St. Paul): A broad end‑market footprint (nonwovens, hygiene, packaging) positions H.B. Fuller to capitalize on volume growth while investing selectively in differentiated, higher‑margin technologies.
- Arkema / Bostik (Colombes): Bostik’s emphasis on bio‑based specialty products and recent soft‑flooring solutions demonstrates the commercialization pathway for sustainability‑driven innovation.
- Sika AG (Baar): Sika’s strength in construction and industrial bonding situates it to gain from building renovation cycles and adhesive systems that meet new façade/window regulations.
- Jowat SE (Detmold): Certification wins (e.g., KOMO in early 2026) underscore the importance of standards compliance in building applications — a differentiator where small suppliers can win premium positions.
- TEX YEAR Adhesive Technologies (Taoyuan) and regional specialists: Regional players are effective in niche verticals such as labels, filtration, and mattresses, often competing on responsiveness and cost efficiency.
- Kraton and Avery Dennison: Kraton’s polymers are enabling higher performance formulations, and Avery’s label/tape franchise highlights adjacent growth paths for hotmelt adhesives in specialty converting.
Recent Signals to Watch (Jan–May 2026)
- Henkel’s 2026 product launches (low‑viscosity Technomelt PA 6370 and Technomelt PUR 9015) signal intensified competition in electronics and appliance assembly.
- Jowat’s KOMO certification (Feb 2026) and Bostik’s soft‑flooring product introductions (Jan 2026) illustrate how compliance and product performance are being commercialized as differentiators.
- Independent launches of biodegradable options in 2025–2026 indicate that sustainable formulations are crossing from lab to certified application — but scale and cost remain constraints.
What the Full PW Consulting Report Contains (Practical, Actionable Deliverables)
- Market sizing and validated forecasts (2020–2032) with scenario‑based sensitivities for high/low raw material paths.
- Granular segmentation by region, adhesive chemistry and application; supply‑side maps and capacity overlays (note: detailed splits are intentionally not disclosed in this preview).
- Company scorecards and capability matrices for the top global players and selected regional challengers.
- Commercial playbooks: go‑to‑market roadmaps, pricing models, and product roadmaps tied to regulatory milestones.
- Supply‑chain risk diagnostics, raw material cost modelling templates and hedging recommendations.
- IP and patent landscape, plus a prioritized list of technology acquisition targets and strategic partnership candidates.
- Investor‑grade M&A screen, including synergies, integration risks and expected payback timelines under multiple price scenarios.
- Interactive dashboards for rapid scenario simulation and executive briefings.
Recommended Strategic Moves for 2026 (Executive Checklist)
- Run three scenario simulations (base, high‑feedstock, fast‑regulatory) to stress test product portfolios and pricing strategies.
- Prioritize reformulation projects that address low‑VOC, non‑PFAS, and recyclability objectives; secure pilot agreements with key converters.
- Establish raw material hedges or alternative sourcing contracts for EVA/polyolefin feedstocks to stabilize gross margins.
- Design an M&A screen focused on regional converters and specialty chemistries that accelerate access to sustainable credentials or certification pathways.
- Invest in demonstrator projects with brand owners to embed adhesives as an enabler of recyclability claims — secure co‑funding where feasible.
- Optimize manufacturing footprint: combine closer‑to‑market compounding with centralized R&D to reduce lead times and speed qualification.
- Create regulatory watch‑posts and a rapid response regulatory compliance team to accelerate time‑to‑market for new formulations.
Closing — How to Use This Preview
This briefing is a strategic summary intended to inform board‑level priorities and sharpen 2026 execution plans. The full PW Consulting Hotmelt Adhesives Market report contains the detailed segmentations, regional breakdowns, unit economics and company benchmarking that commercial and product teams require to translate strategy into operating plans. Those granular datasets and actionable templates are deliberately held for subscribers and clients; they are the tools that convert insight into measurable advantage.
For immediate next steps, stakeholders should (1) request our scenario pack to run 90‑day margin and product‑mix stress tests, and (2) commission an M&A or partnership scan if consolidation or capability acceleration is under consideration. PW Consulting is available to present a tailored executive briefing to convert these market signals into a concrete 2026 roadmap.
For detailed analysis of this topic, please visit the official page: Hotmelt Adhesives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com