

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Stairlift market poised for 5.81% CAGR through 2032

Stairlift Market — 2026 Strategic Preview
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, this preview frames the strategic value of our Stairlift Market research for corporate decision-makers planning through 2026. The goal is to surface the analytic themes, operational implications and priority moves that senior leaders must weigh — while preserving the full segmentation intelligence and proprietary scenarios contained in the complete report. Consider this a high‑fidelity trailer: deep enough to inform strategy conversations, but intentionally reserved where transaction‑level detail and model outputs reside.
Stairlift Market
Market snapshot: scale, trajectory and structure
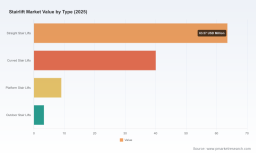
The stairlift market has moved from niche to formative scale over the past half‑decade. Using 2025 as our base year, the market reached approximately USD 116.0 Million and has grown steadily from the 2020 baseline. Under the central forecast the market is expected to expand at a compound annual growth rate (CAGR) of c. 5.8% through the 2026–2032 horizon, reaching approximately USD 171.4 Million by 2032 under current assumptions. This pace reflects the interplay of demographic tailwinds, expanding subsidy programs, and rising expectations for home‑based accessibility solutions.
Stairlift Market
Concentration is notable: the industry exhibits a mid‑to‑high level of supplier concentration, with the top three and five vendors controlling a majority of revenue. That structure creates both competitive pressure and opportunity — incumbents enjoy scale benefits in service and distribution, while challengers can carve profitable niches through specialization, faster installation models, or disruptive service offerings.
Stairlift Market
Why this matters for 2026 decision cycles
- Investment prioritization: capital allocation decisions must balance product R&D, dealer & service expansion, and regulatory compliance investment. The estimated CAGR and trajectory provide a disciplined baseline for return expectations across those initiatives.
- Route‑to‑market strategy: dealers, OEMs and private equity backers must choose between scale‑driven national rollouts or concentrated, high‑margin local plays. Both are viable — but the optimal choice depends on service economics and the company’s ability to achieve fast, quality installation.
- Product and service differentiation: the industry is bifurcating between modular, quick‑install systems and bespoke, high‑end solutions. Companies must decide whether to pursue standardization to reduce unit costs or customization to capture premium margins.
- Regulatory and reimbursement risk: new ISO safety standards (ISO 9386, 2025) and uneven public reimbursement policies materially affect product design, go‑to‑market timing, and the cost base. Firms that front‑load compliance and demonstrate clear safety credentials will reduce order‑to‑install friction and build trust with institutional buyers.
Demand drivers and the dynamics that will shape 2026 strategies
- Demographics and healthcare shift: growing numbers of older adults choosing to age in place, combined with outpatient rehabilitation trends, are expanding residential and healthcare channel demand. Home modification subsidy programs in several markets are accelerating adoption.
- Standards and safety certification: ISO 9386 (2025) raises the bar for safety features and test documentation. Compliance is not optional for companies seeking institutional contracts or commercial deployments.
- Reimbursement realities: major public payors (e.g., Medicare) currently do not cover stairlift purchase or installation, which keeps consumer financing, subsidies, and private insurance arrangements front‑and‑center in pricing strategies.
- Service economics and installation speed: “next‑day” or same‑week installation propositions — enabled by modular design and robust dealer networks — materially improve conversion and lifetime customer value.
- Climate and product breadth: demand for weather‑resistant outdoor units is growing in specific markets; firms that can extend product portfolios without diluting core service capabilities capture additional adjacent revenue pools.
Competitive landscape — strategic profiles and implications
The market comprises a mix of established OEMs, regionally dominant specialists, and a scattering of bespoke producers. Below are the strategic positions of the principal competitors and the management implications we draw from their recent moves.
- Acorn Stairlifts (Orlando, FL / UK heritage) — A high‑volume exporter with a proposition built around rapid installation and modular design. Their global footprint and focus on quick time‑to‑service is a model for increasing conversion in the residential market. Strategic implication: invest in logistics and pre‑configured modules to lower installation friction.
- Stannah (Eastleigh, UK) — A premium, family‑governed manufacturer that emphasizes “Made in Britain” credentials and broad model depth. Recent accreditation and product launches underline a brand‑led strategy. Strategic implication: premium branding plus product proliferation can justify higher margin models and institutional partnerships.
- Bruno Independent Living Aids (Oconomowoc, WI) — Emphasizes U.S. manufacturing, a large dealer network, and strong aftermarket warranties. This model is particularly effective in markets where “buy local” and service continuity matter. Strategic implication: service guarantees and dealer density are defensible assets.
- Savaria / Handicare (Laval, QC / Heerhugowaard) — A combined capability across residential and commercial lines with expanding North American service reach. Their multi‑brand strategy provides cross‑sell and channel leverage. Strategic implication: integrating adjacent mobility products can deepen wallet share with institutional customers.
- Specialists and bespoke UK makers (Platinum, Bespoke, Companion) — Focus on slimline aesthetics, custom builds, and local craftsmanship. These players win on unique stair geometries and premium home conversions. Strategic implication: maintain a high‑margin niche playbook and partner with estate remodelers and architects.
- U.S. niche players (Harmar, AmeriGlide, Leaf Home) — Harmar’s recent performance points to resilient demand; Leaf Home’s new outdoor model signals growth in weather‑resistant applications. Strategic implication: product line extensions (outdoor, heavier‑use commercial) unlock new revenue streams but require distribution and service adaptation.
Recent signals worth watching
- Product and brand signaling: Stannah’s 2025 accreditation and model launches reinforce a premium plus breadth play; competitors will respond with targeted product investments or marketing to protect share.
- Product diversification: Leaf Home’s outdoor stairlift launch highlights the value of addressing climate‑exposed markets with engineered solutions, an area where incumbents can either compete or concede specialty segments.
- Financial performance indicators: select manufacturers reported modest top‑line gains in 2025, reflecting steady demand but also cost pressure from labor and component markets. Margin management will be a frontline priority in 2026.
- Standards adoption: ISO 9386’s implementation timeline is a practical gating item for tendering in many institutional and commercial contexts. Companies that can demonstrate compliance will win faster access to large projects.
Actionable strategic options for 2026
- Scale through service: prioritize dealer density, certified installers, and a centralized parts distribution strategy to reduce lead times and installation costs.
- Product architecture optimization: develop a two‑track portfolio — modular, off‑the‑shelf platforms for fast installs, and a premium bespoke line for complex staircases and affluent buyers.
- Compliance as a commercial lever: allocate early R&D and testing budgets to ensure ISO 9386 alignment and publicize certifications as a differentiator for institutional procurement.
- Monetize the installed base: offer maintenance contracts, trade‑in programs, and rental/subscription options to capture recurring revenue and raise lifetime value.
- Targeted M&A and partnerships: use tuck‑ins to secure regional service footprints or acquire specialized outdoor/curved technology rather than attempting organic development in every niche.
- Channel financing and subsidies: build finance products and subsidy‑assistance teams to overcome the barrier created by public payor exclusions and to accelerate conversions in subsidy‑eligible populations.
What PW Consulting’s full Stairlift Market report contains (select highlights)
- Comprehensive sizing and forecast model (base year 2025; historical 2020–2025; forecast 2026–2032) with scenario paths and sensitivity testing tied to key demand levers.
- Product, channel and application playbooks that translate market movement into prioritized initiatives by role: OEM, dealer, investor, and service operator.
- Vendor dossiers including capability mapping, go‑to‑market strategies, warranty and service comparisons, and near‑term strategic signals.
- Regulatory and standards impact assessment (ISO 9386) with compliance cost estimates and implementation roadmaps for product and quality teams.
- Deal pipeline and M&A readiness framework to help corporate development teams identify attractive targets and integration risk levers.
- Operational checklists for installation network scaling, parts logistics optimization, and after‑sales monetization programs.
Note: this preview intentionally omits the full, granular breakdowns across regional, application, and product segments that underpin our forecasting model. Those detailed splits and supplier market shares are included only in the full report to ensure analytical integrity and to support executable go‑to‑market plans.
Final takeaway — the strategic imperative for 2026
The stairlift market is transitioning from a low‑growth, specialty product space into a structured, service‑driven market with multi‑year growth potential. For leaders planning in 2026, the imperative is clear: move beyond product thinking to systems thinking — integrate product, certified service delivery, compliance readiness, and financing to capture durable value. Scale and service density will determine winners in mainstream residential and commercial channels, while product craftsmanship and bespoke capabilities will sustain attractive niches.
For executives preparing capital plans, M&A strategies, or new‑product roadmaps, our full Stairlift Market report provides the operational models, vendor analytics and scenario playbooks needed to convert market trajectory into profitable action. Contact PW Consulting to access the complete intelligence package and the underlying model outputs that support 2026 decision‑making.
For detailed analysis of this topic, please visit the official page: Stairlift Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com