

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Limestone Market to Grow at 3.59% CAGR Through 2032

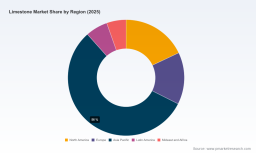
Limestone Market 2026: Strategic Signals for Executive Decision-Making
As PW Consulting’s Senior Strategy Advisor, I present a focused preview of our new Limestone Market study — a decision-grade briefing intended to shape capital allocation, sourcing strategy, and regulatory planning for 2026. The sector is neither static nor monolithic: after steady expansion through the early 2020s, the global limestone market headlined by an estimated USD 88.8 Billion in 2025 is projected to rise into the mid-USD 90s by 2026 and continue growing through our 2026–2032 forecast window at a compound annual growth rate of 3.59%. Those topline dynamics matter, but the real strategic value comes from reading the growth signal through supply structure, regulatory exposure, and transactional activity.
Limestone Market
Why this study matters for 2026 decisions
-
Investment timing: With visible growth but uneven supply-side moves, executives must decide whether to accelerate capacity projects, pursue bolt-on deals, or prioritize efficiency investments. Our study isolates when and where each choice is likely to preserve or create value.
Limestone Market -
M&A playbooks: Market concentration metrics indicate a sector that is modestly consolidated at the top but still highly contestable. The implications for deal valuation, integration risk, and competitive responses are core to 2026 transactions.
Limestone Market -
Regulatory and ESG risk: Tightening emissions and permitting regimes create both compliance obligations and strategic opportunities for early movers. The timing of permit risk and decarbonization spend will materially affect project ROI.
-
Commercial contracting and pricing: Recent commodity price movements and expected pressure on crushed stone pricing require updated procurement clauses, indexation strategies, and hedging approaches in long-term supply contracts.
What PW Consulting’s Limestone Market study delivers
-
Topline market trajectory and demand scenarios for 2026–2032 (base year 2025), combining macro assumptions with construction, industrial, and environmental use-case drivers.
-
Supply-side inventory and capacity analysis, including planned greenfield and brownfield projects, maintenance cycles, and likely commissioning timelines.
-
Competitive positioning maps, with CR3 and CR5 concentration indicators to guide antitrust sensitivity, bidding strategies, and partnership screening.
-
Regulatory risk matrix covering GHG frameworks, permitting bottlenecks, and environmental compliance costs by jurisdiction and facility type.
-
Commercial playbooks: procurement clauses, pricing indexation templates, and logistics optimization for high-volume feedstocks.
-
Practical M&A diligence checklists and valuation scenarios tailored to asset quality, reserve life, and integration complexity.
-
Interactive models and scenario decks that let users stress-test outcomes against commodity price moves, regulatory shifts, and demand shocks.
Market dynamics: what’s driving the near-term picture
Several structural and cyclical forces shape the 2026 landscape. Construction and infrastructure cycles remain the principal demand anchors, supported by industrial uses including cement and certain process applications. Supply remains responsive but localized, meaning logistics, quarry footprint, and access to processing capacity are as determinative as geological endowments.
Price momentum in the broader minerals sector during 2025 was mixed, though authorities have flagged an expected uptick in crushed-stone pricing into 2026. In parallel, raw material availability at scale (for example, national crushed-stone production figures reported in industry surveys) underscores how domestic aggregates continue to feed national construction markets and influence international flows.
On the regulatory front, leading operators have explicitly called out exposure to GHG regulation and Title V-style permitting in advanced markets. Environmental constraints — dust control, water management, and tightening mining permits — are producing longer lead times for new projects and added compliance costs for existing plants. These dynamics compress effective supply elasticity even when headline capacity figures appear ample.
Supply and competition: reading the field
The sector’s competitive topology is best understood as a mix of large integrated miners and specialized lime producers. Leading companies — from major aggregates-focused firms to specialized lime and mineral producers — deploy distinct strategies that shape market access and pricing power.
-
Integrated aggregates leaders anchor regional supply frameworks through broad quarry networks and logistics capabilities. Their scale provides distribution reach and balance-sheet flexibility for capital projects.
-
Specialized lime and mineral manufacturers focus on higher-purity products and value-added processing, servicing industrial, environmental, and specialty markets where technical specification matters more than raw tonnage.
-
European and global industrial players bring technology transfer and product diversification into markets with high environmental standards, accelerating premium product adoption.
Recent corporate actions illustrate these strategic behaviors: capacity expansions at major lime producers signal readiness to meet industrial demand and to capture margin uplifts from specialty grades; acquisitive moves by large aggregates firms reflect a continued appetite for bolt-on assets that improve regional density and logistics; and some multinational cement and minerals players are layering in walling systems and complementary products to extend value chains. Collectively, these moves portend further selective consolidation, localized market power shifts, and increased importance of integration economics.
Regulatory and ESG: the non-price battleground
For 2026, executives should treat regulatory dynamics as a core strategic lever — not merely a compliance cost. Public agencies and operators alike have spotlighted emissions permitting and site-level environmental controls as decisive inputs to project timelines and operating costs. Operators that can demonstrate lower embedded emissions, robust water stewardship, and minimized dust generation will enjoy faster permitting, lower financing costs, and advantaged offtake terms from environmentally sensitive customers.
Scenario thinking: three 2026-ready contingencies
-
Moderate-growth baseline: construction demand tracks expectations, price increases are gradual, and selective capacity additions bring incremental balance. Under this scenario, prioritize operational efficiency and targeted M&A to fill geographic gaps.
-
Regulatory-tightening shock: accelerated permitting constraints and emissions costs compress supply in certain jurisdictions. In this case, prioritize permitting-fast projects, invest in emissions mitigation at legacy sites, and seek longer-term offtake contracts with price protection.
-
Demand disruption: a construction slowdown or commodity price shock reduces volumes. Here, focus on variable-cost reduction, cross-utilization of product lines, and conversion of certain assets to higher-margin specialty applications.
Actionable strategic priorities for 2026
-
Re-run portfolio IRR with regulated-cost overlays: embed permitting delay assumptions and GHG compliance costs into every capital project evaluation.
-
Design a two-track M&A filter: quick density-add bolt-ons with fast payback, and strategic verticals that offer product differentiation and margin expansion.
-
Lock logistics and offtake before greenfield commitments: rail and port access can make or break long-haul supply economics for high-volume quarries.
-
Prioritize decarbonization where it shortens permitting timelines or secures premium contracts; not every asset needs near-term carbon retrofit, but targeted investments can materially de-risk future revenue.
-
Revise procurement contracts to incorporate indexed pricing, volume flex, and force-majeure clauses tied explicitly to permitting or regulatory changes.
-
Deploy asset-level risk heatmaps from our study to prioritize capex and maintenance spend — the highest-return actions are often site-specific.
Competitive moves to watch in 2026
Expect continued bolt-on consolidation by large aggregates players seeking regional density and a steady campaign of vertical integration by firms that supply lime- and limestone-derived specialty products. Watch for capacity additions from specialist producers and targeted acquisitions by multinational industrial mineral groups focused on product quality and market access. Public disclosures from leading operators also underscore near-term execution risks tied to permitting and emissions compliance — factors that will influence M&A timing, divestiture windows, and capital availability.
Closing: the strategic value of granular insight
The 2026 strategic environment for limestone is characterized by modest topline growth, differentiated supply-side moves, and material regulatory uncertainty. For executives making investment, procurement, or M&A decisions this year, the difference between a good outcome and a stranded asset will depend on integrating demand forecasts with site-level permitting realities and competitive playbooks.
Our full Limestone Market report supplies the granular, operational datasets and scenario tools needed to act with conviction — including localized supply maps, asset-level risk assessments, and executable playbooks for procurement and M&A. This preview highlights the strategic signals; the full study contains the actionable intelligence you will need to calibrate 2026 decisions and to stress‑test them across plausible futures. Reach out to PW Consulting to access the report package, interactive models, and a tailored briefing for your leadership team.
For detailed analysis of this topic, please visit the official page: Limestone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com