

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vehicle Camera Module Market to Expand at 13.8% CAGR Through 2032

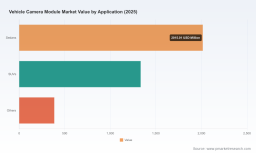
Vehicle Camera Module Market — Strategic Briefing for 2026 Decision-Makers
As senior industry advisors at PW Consulting, we present an executive introduction to our comprehensive Vehicle Camera Module Market study. This briefing distills the strategic implications that matter for boardrooms and product teams in 2026, showing why camera modules are now a core strategic lever across OEMs, Tier-1 suppliers and semiconductor vendors. The full study contains the granular, transaction-grade data and segment-level intelligence that procurement, M&A and R&D leaders will need to act with confidence; this article is a focused “trailer” that demonstrates our depth while reserving proprietary splits and scenario tables for subscribers.
Vehicle Camera Module Market
Market trajectory in context
The camera module market for vehicles is no longer a peripheral electronics segment — it is a foundational component of modern vehicle perception stacks. From a macro perspective, the sector has expanded rapidly over the past half-decade and is forecast to continue at a robust pace. PW Consulting’s modeling (base year 2025) shows growth from roughly USD 1.95 billion in 2020 to approximately USD 3.73 billion in 2025, with market size progressing further into the forecast period; by 2032 the market is projected to approach the USD 9.21 billion mark. The forecast period is modeled at a compound annual growth rate (CAGR) of 13.8% (2026–2032), a rate driven by regulatory mandates, ADAS/autonomy adoption, and the sensorization of vehicle interiors and exteriors.
Vehicle Camera Module Market
Why 2026 is an inflection year
- Regulatory catalysts: New safety regulations (notably Europe’s General Safety Regulation) mandate in-cabin driver monitoring and other camera-enabled safety features from mid-2026. These rules accelerate retrofit and OEM program timelines and shift purchasing from optional to compliance-driven.
- Productization of enabling technologies: Next-generation image sensors and interface standards (e.g., sensors with integrated A-PHY connectivity) are moving rapidly from announcement to sampling and production readiness, shortening integration cycles for system architects.
- Commercial scale and supplier realignment: The market’s underlying economics and supplier concentration metrics indicate a fragmented supplier base with increasing consolidation pressure — creating acquisition and partnership opportunities for scale-seeking players.
Key dynamics shaping supplier economics
Three forces are simultaneously shaping supplier economics and buyer strategies in 2026:
Vehicle Camera Module Market
- Technology standardization and integration: The emergence of sensors with built-in automotive interfaces and higher integration reduces BOM complexity for system integrators but raises the bar for suppliers that cannot rapidly adopt new interfaces and AEC-grade testing practices.
- Component reliability and environmental hardening: Camera modules require specialized materials and features (e.g., hydrophobic coatings, heating elements, ruggedized lenses, automotive-grade packaging). These elements add cost and supplier complexity but are non-negotiable for OEMs operating across diverse climates.
- Regulatory-driven demand vs. differentiated use-cases: While regulations create baseline demand (e.g., mandatory driver monitoring), differentiated ADAS and autonomy roadmaps (surround view, fusion camera-radar modules) drive premium attachments and system-level pricing power.
Competitive landscape — what to watch
The market combines deep-capability semiconductor houses, established automaking suppliers, and specialized camera module manufacturers. Market concentration at the top remains modest (our CR3 and CR5 analysis indicate a low-to-moderate concentration environment), leaving substantial share available to disruptors and fast-scaling partners. Below are strategic profiles of the players we track closely and how recent moves affect 2026 strategies:
- Sony Semiconductor Solutions (Atsugi, Japan): A leader in high-performance CMOS image sensors. Recent announcements around sensors with integrated MIPI A-PHY interfaces signal an industry shift toward simplified system integration and reduced cable complexity. For OEMs, these sensors shorten validation timelines but require close collaboration on interface convergence.
- OMNIVISION Technologies (Santa Clara, USA): Focused on differentiated sensor IP (e.g., TheiaCel). New 8MP automotive sensors moving to sampling and planned mass production provide additional image-quality and low-light options for exterior cameras — relevant for companies targeting premium ADAS calibration performance.
- LG Innotek (Seoul, South Korea): Strong module and in-cabin solutions provider with investments in under-display camera (UDC) technology for driver monitoring. Its joint venture activity with a major systems integrator signals a verticalization trend in module-radar integration.
- Samsung Electro-Mechanics (Suwon, South Korea): Positioning around weatherproofing and reliability, Samsung’s materials and process expertise are a go-to for OEMs requiring global field durability.
- Magna, Bosch, Continental, Valeo, DENSO, Aptiv: These Tier-1 systems integrators are consolidating camera subsystems into broader perception stacks (camera + radar + compute). Their moves shape platform-level procurement decisions and provide bundled alternatives to point-solution vendors.
Recent, tangible developments — such as Sony’s IMX828 sensor (industry-first A-PHY-equipped automotive sensor), OMNIVISION’s advanced sampling cadence, LG Innotek’s under-display module reveal, and the LG–Magna collaboration on camera-radar modules — materially accelerate timelines for certain integration choices. Each announcement compresses the lead time between R&D and production programs, which in 2026 will benefit buyers who have pre-aligned testing and validation processes.
Strategic implications for 2026 decision-making
For executives navigating 2026 program planning, three priority domains should guide capital allocation and partnership decisions:
- Procurement and supplier selection: With component and integration options proliferating, adopt a two-track sourcing strategy: secure compliance-baseline suppliers for mandated features while contracting with innovators for differentiated perception capabilities. Build contract clauses that manage sampling-to-mass-production timelines and include penalty/bonus structures tied to interface-compliance milestones.
- Technology and systems architecture: Evaluate sensor-interface roadmaps (A-PHY adoption, on-sensor processing) against system-level architecture choices (centralized vs. distributed perception). Early alignment with sensor roadmap owners reduces integration risk and test cycles in 2026–2027 programs.
- M&A and partnership playbook: Given modest top-end concentration and rapid technology convergence, 2026 is an opportunistic year for inorganic moves: target bolt-ons that provide proprietary sensor IP, environmental hardening capabilities, or regional manufacturing capacity to accelerate time-to-OEM signoffs.
Operational priorities and risk mitigation
Operational leaders should prioritize three actions in 2026 to de-risk program delivery:
- Validation and compliance acceleration: Invest in early-stage AEC-Q and MIPI A-PHY compliance testing. The cost of late-stage redesigns in camera modules is high due to optics, coatings and mechanical integration.
- Supply-chain resilience: Lock long-lead components and build dual-sourcing for critical optical and sensor parts. Negotiate capacity commitments with semiconductor partners whose advanced nodes are entering automotive sampling phases.
- Localization and cost engineering: Combine global design platforms with local manufacturing and coatings capability to control unit-costs and reduce exposure to freight and trade volatility.
What the PW Consulting report provides (practical deliverables)
Our full Vehicle Camera Module Market study is designed as an operational playbook for 2026. Core deliverables include:
- Market sizing and high-resolution, year-by-year forecasts (historical 2020–2025, base year 2025, forecast 2026–2032) — enabling capex modeling and revenue scenarios.
- Detailed segmentation (by functionality, mounting type, automotive class and geography) with adoption curves and sensitivity analysis for regulatory and technology scenarios — reserved for report subscribers.
- Supplier scorecards and capability maps covering testing, manufacturing footprint, IP position and channel access — actionable for sourcing and M&A teams.
- Technology roadmaps and integration playbooks (sensor interface standards, optics, environmental hardening) including time-to-market, sampling and mass-production windows for key sensors and modules.
- Commercial tools: price-decomposition models, BOM cost drivers, and negotiated terms templates tailored to camera module procurement.
- Risk matrices and mitigation plans focused on regulatory compliance, material cost volatility, and supplier concentration exposure.
How to use this intelligence in 2026
Decision-makers should treat the market intelligence as both a thermometer and a playbook: it measures demand thermals across the entire vehicle lifecycle while prescribing executable moves. Specific recommended next steps for 2026:
- Execute rapid technical vetting programs with any sensor vendor that has announced sampling of next-gen, A-PHY-equipped devices — early lab integration reduces field surprises.
- Prioritize cross-functional alignment between compliance, procurement and systems engineering to convert regulatory mandates into validated product lines with predictable margins.
- Run scenario planning that quantifies the impact of adding or losing a single Tier-1 supplier to capture both upside and downside exposure to CR3/CR5 concentration dynamics.
- Identify one or two strategic partnerships (e.g., radar–camera integration, UDC for cabin monitoring) that can be executed within an 18–24 month window to capture consolidated program wins.
Closing — why this matters now
Vehicle camera modules are morphing from commodity add-ons into strategic system enablers that influence vehicle safety compliance, user experience, and autonomous capability. Our market modeling shows strong, sustained expansion through 2032 (13.8% CAGR in the forecast horizon), but the distribution of value will be neither uniform nor forgiving to late movers. The companies that win in 2026 will be those that align procurement, testing and integration strategies with emerging sensor standards, secure resilient component supply, and move decisively on partnerships and selective consolidation.
For readers who require the full, transaction-ready intelligence — detailed regional and application splits, supplier financials, unit-cost models, and program-level adoption timelines — the complete PW Consulting Vehicle Camera Module Market report contains the proprietary tables and scenario tools needed to operationalize these recommendations. Access to the full dataset and consultancy support is available through our industry services team.
For detailed analysis of this topic, please visit the official page: Vehicle Camera Module Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com