

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Titanium Alloy Market to Reach USD 8.63 Billion by 2032 at 5.18% CAGR

Titanium Alloy Market 2026: Strategic Imperatives for Supply, Sourcing, and Scale
As PW Consulting’s lead industry analyst, I present a focused, executive-grade view of the titanium alloy market that frames the critical choices boards and procurement leaders will face through 2026. Our full Titanium Alloy Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes demand dynamics, supply-side fragility, competitive positioning, and regulatory noise into actionable strategies. In this preview, we surface the high-conviction insights that should shape capital allocation, sourcing policy, and M&A prioritization — while reserving the granular segment tables and price ladders for subscribers to the full report.
Titanium Alloy Market
Why 2026 is a Strategic Inflection Point
The market has moved from recovery into structural growth. Global titanium-alloy revenue rose from approximately 4.5 billion USD in 2020 to about 6.08 billion USD in 2025, and our base-case projection takes the market to roughly 6.29 billion USD in 2026 with a compound annual growth rate (CAGR) of 5.18% across the 2026–2032 forecast window. By 2032 the market is projected to exceed 8.5 billion USD under the report’s central scenario.
Titanium Alloy Market
Those headline numbers mask a market shaped by three simultaneous forces: (1) accelerating aerospace demand as commercial and defense platforms normalize post-disruption; (2) strategic raw-material constraints and trade policy that amplify supplier power; and (3) technology and material-substitution pressures from lightweighting initiatives across automotive and industrial segments. These forces create a high-value environment where supply decisions and contractual choreography materially affect cost of goods, availability, and program risk.
Titanium Alloy Market
Supply-Side Fragility: A New Risk Profile
-
Titanium sponge and primary conversion remain a concentrated, geopolitically sensitive part of the value chain. Recent disclosures show significant softness in sponge output from a major integrated supplier, and broader market reality remains that a handful of producers dominate upstream capacity. Our report models supply disruption scenarios and their asymmetric impacts on lead times and premiums.
-
Trade and regulatory levers are meaningful. U.S. import tariffs and high market share of a small set of exporting nations create a persistent import dependency for aerospace-grade inputs. The practical consequence for buyers: benchmark price signals can disconnect from replacement-cost economics during tightening events.
-
Capital intensity and long project gestation mean rapid capacity scaling is difficult. Even when demand signals justify investment, new production lines and qualification cycles for aerospace-grade material introduce lag and execution risk.
Demand Dynamics: Where the Growth Comes From (and What to Watch)
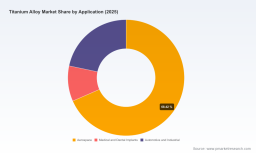
Aerospace remains the demand anchor for premium titanium alloys, but diversification in application and increasing engineering acceptance in automotive and industrial uses are altering the elasticity of demand. Medical and dental implant markets sustain a premium niche supported by high-purity production routes, while industrial adoption of additively manufactured titanium powders is an emerging channel.
For executive decision-making in 2026, the key signals to monitor are orderbooks at OEMs and Tier-1s, inventory-to-shipment ratios across primary producers, and qualification trajectories for new aircraft programs and electric/hybrid vehicle platforms. Our scenario sets analyze how different recovery curves in aerospace translate into order volatility across the upstream chain.
Competitive Landscape and Strategic Implications
The upstream and midstream competitive map is mixed between vertically integrated global titans and specialized regional players. The market concentration metrics point to a moderately fragmented supply base, creating opportunity for both consolidation and differentiation. Leading names we profile in the full study include primary integrated producers and mill-product specialists. Our companion company dossiers evaluate the following themes for each player: vertical integration and sponge access, capacity expansion plans, long-term OEM contracts, technology and product breadth, and geopolitical exposure.
-
Integrated producers with upstream sponge exposure retain an advantage when primary material tightness creates allocation risk. They can protect internal programs and monetize surplus via premium sales — but they also carry geopolitical and regulatory exposure tied to national supply chains.
-
Mill-product specialists that focus on sheet, plate, and billet for aerostructures differentiate through qualification, proximity to OEMs, and the agility to support complex contracts. Recent capacity additions and multi-year supply agreements have solidified market positions for leading mill-product firms.
-
Regional producers and powder specialists compete on supply security, niche high-purity grades, and additive-manufacturing feedstock. Their strategic value to OEMs is often as a flexible second source, though scaling remains a constraint for large production ramps.
Recent Developments That Matter
-
Capacity movements: Major aerospace-focused mill producers have brought new sheet and plate capacity online and secured multi-year agreements with leading OEMs, reinforcing the “supply ladder” for certified aerostructures.
-
Operational adjustments: One of the largest upstream producers has announced workforce and scheduling changes in response to reduced near-term demand, and reported a marked decline in titanium sponge output relative to recent years. That decline is the lowest in a decade for that operator and is a salient input into our tight-supply stress tests.
-
Policy and trade: Import tariffs and the concentration of upstream capacity among a small set of exporting nations remain an immediate operational factor for sourcing teams. Our risk-adjusted cost models incorporate tariff scenarios and alternative routing strategies.
From Analysis to Action: 7 Strategic Moves for 2026
-
Lock strategic runway with layered contracts — combine multi-year base agreements for core volumes with indexed short-term purchase arrangements to capture upside in market softening.
-
Invest in supply diversity — sponsor second-source qualification programs and supplier development in lower-risk jurisdictions to reduce allocation exposure during upstream shocks.
-
Pursue vertical options selectively — for OEMs with sustained titanium intensity, partial upstream integration (e.g., secured tolling or joint-conversion ventures) can be value-accretive when priced against long-term scarcity premia.
-
Hedge via material substitution playbooks — accelerate engineering assessment of alternative alloys and composites where lifecycle economics and certification risk permit.
-
Capitalize on premium niches — prioritize investment and margins in high-purity medical and aerospace qualification lanes where barriers to entry are highest.
-
Prepare M&A and partnership triggers — the market’s mid-tier is ripe for consolidation; identify targets that offer either geographic access or qualification capability as “capability buys.”
-
Operationalize scenario planning — embed supply disruption scenarios into product launch, inventory, and costing models to preserve program continuity when upstream metrics deteriorate.
What the PW Consulting Report Delivers (Operational, Executable)
To support the moves above, our full Titanium Alloy Market report contains:
-
Demand forecasts and scenario matrices (2026–2032) tied to OEM production cases and alternative adoption curves for automotive and industrial use.
-
Supply-chain risk maps, including supplier exposure scores, lead-time heat maps, and sponge availability stress tests.
-
Price-sensitivity and pass-through models reflecting tariff and freight shocks.
-
Practical procurement playbooks: template contract clauses, dual-sourcing qualification checklists, and inventory policy simulations for program managers.
-
M&A target screening framework and valuation benchmarks for strategic and financial buyers in the titanium value chain.
-
Company-level dossiers with capability assessments, recent developments, and strategic posture analysis for the major market participants.
How Executives Should Use This Preview
This briefing is intended as a decision-useful preview: it highlights the high-level numbers, the directional risks, and the types of strategic responses that yield outsized protection or upside in 2026. The full report contains the detailed segment-level tables, regional and application splits, price curves, and supplier scorecards that operational teams will need to execute on these strategies. We deliberately withhold the granular breakdowns here to encourage direct interaction with the evidence base — and to ensure procurement and strategy teams can access the precise models required to convert recommendation into action.
Closing: The Cost of Delay
Market movement is already visible in contract awards and capacity shifts; decisions deferred into late 2026 will face higher uncertainty and narrower tactical options. Whether your priority is securing program supply, defending margin, or selectively investing in vertical capability, the choices made in 2026 will materially affect total cost of ownership through the decade. PW Consulting’s Titanium Alloy Market study gives you the scenario tools, sourcing playbooks, and company intelligence to act with confidence. For the full dataset, supplier rankings, and executable templates, refer to the complete report and our bespoke advisory engagements.
For detailed analysis of this topic, please visit the official page: Titanium Alloy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com