

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
APD market to reach USD 250.4M by 2032 at 4.62% CAGR | PW Consulting

APD (Avalanche Photodiode) Market — Strategic Outlook for 2026 Decision-Makers
As the APD (Avalanche Photodiode) market moves from specialized niche to broader deployments across telecom, sensing, and emerging LiDAR applications, 2026 will be a pivot year for commercial players and strategic investors. Our APD Avalanche Photodiode Market study (base year 2025, historical window 2020–2025, forecast 2026–2032) quantifies a mature-but-accelerating landscape: the market is estimated at USD 181.7 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 4.62% through the forecast window, reaching roughly USD 250.4 Million by 2032. This preview lays out the operational insights and strategic options executives must consider when translating market signals into 2026 action.
APD Avalanche Photodiode Market
Why this study matters for 2026 strategy
- Decision timing: 2026 is the first year many APD-adjacent supply chains reprice and reconfigure following geopolitical, tariff, and material-sourcing shocks that began reshaping supplier economics in 2024–2025.
- Resource allocation: R&D and capex commitments made in 2026 will determine who leads in next-generation low-noise InGaAs and silicon APDs for time-of-flight, telecom, and photon-counting niches.
- Partnering and M&A: With a market structure that shows moderate concentration among leading suppliers, targeted partnerships or bolt-on acquisitions can tip system integrators into leadership positions in key subsegments.
- Risk management: Near-term material and IP risks demand proactive mitigation — procurement, inventory strategy, and licensing frameworks will directly affect delivery schedules and margins.
What the report delivers — practical, actionable content
- Strategic market sizing and scenario forecasts (2026–2032) — top-line trajectories under three macro pathways (baseline, constrained-supply, accelerated-adoption) calibrated to supply-chain and regulatory shocks.
- Competitive concentration and benchmarking — independent CR metrics and capability mapping that identify which suppliers lead on performance, qualification, and scale.
- Technology and product roadmaps — device-level performance trade-offs (sensitivity, dark current, wavelength windows), packaging, and module integration guides that translate device specs into system-level ROI.
- Supply chain heat maps — vulnerability scoring across raw materials (notably indium/gallium exposures), substrate supply, contract manufacturing, and logistics nodes with mitigation playbooks.
- IP and regulatory dossier — patent landscape synthesis, key blocking patents to monitor, and tariff/regulatory scenarios with quantified impacts on chip-level supply and landed cost.
- Commercial playbooks — go-to-market, channel strategies, and pricing architecture tailored to OEMs, system integrators, and defense buyers.
- M&A and investment screening — a prioritised checklist of technical, commercial, and regulatory criteria for deals that accelerate access to critical wavelengths or qualification credentials (e.g., automotive standardization).
Market structure and dynamics to watch
The APD market is at an inflection: steady end-market demand meets episodic supply-side constraints. Key structural takeaways that executives should internalize for 2026 planning include:
APD Avalanche Photodiode Market
- Measured growth with pockets of acceleration — the overall market grows at a mid-single-digit CAGR, but subdomains tied to 1,550 nm lidar and high-sensitivity photon counting exhibit asymmetric upside potential.
- Moderate market concentration — the top-tier suppliers capture a meaningful share of revenue and capability, making supplier strategy (partnering, qualifying second sources) a central procurement priority.
- Material and geopolitical exposure — indium/gallium supply tightness and rare-earth substrate constraints create lead-time and cost volatility. Companies that hedge or vertically integrate these inputs will gain margin and time-to-market advantages.
- Regulatory and IP friction — tariffs and active patents on certain APD architectures constitute near-term commercialization hurdles in some geographies; resolution strategies will shape licensing and product design choices.
Competitive landscape — who matters and why
The competitive map is diverse: legacy photonics houses, diversified semiconductor suppliers, and focused startups. Our research profiles and benchmarks a set of companies that define today’s competitive dynamics and set strategic reference points for 2026:
APD Avalanche Photodiode Market
- Excelitas Technologies (Waltham, MA) — a broad portfolio approach with Si and InGaAs APDs targeted at low-light and photon-counting applications; plays the role of systems-focused incumbent with wide optical component coverage.
- Hamamatsu Photonics (Hamamatsu, Japan) — strength in high-sensitivity Si APDs and arrays, with a reputation for low dark current devices spanning UV to NIR detection; engineered performance and reliability are core assets.
- Laser Components (Austria; production in Arizona) — in-house manufacturing and specialty packaging, including automotive qualification (AEC-Q102), gives it an edge where supply stability and qualification throughput matter.
- Thorlabs (Newton, NJ) — a solutions-oriented supplier of free-space Si APDs and modules optimized for optical-system integrators focused on sensitivity and noise performance.
- Micro Photon Devices (Trento, Italy) — a specialist in single-photon APDs and arrays for time-resolved applications; technical differentiation in timing jitter and array scaling.
- ON Semiconductor (Phoenix, AZ) — offers SiPMs and SPADs alongside APD technologies; breadth across detector families positions it well for integrated sensor modules.
- Phlux Technology (Sheffield, UK) — a newer entrant focused on noiseless InGaAs APDs for infrared sensing and LiDAR; notable for product moves such as the July 2025 launch of an evaluation board for its Aura family that simplifies infra‑red system development.
Industry alerts — supply, IP, and regulatory factors that can change plans overnight
- Raw-material pressures: Indium and gallium supply chain tightness elevates cost and lead-time risk for InGaAs-based devices. Prioritize material audits and contract clauses that address allocation and price pass-throughs.
- Geopolitical and tariff dynamics: Tariff measures slated in recent years are already shaping chip routing and sourcing strategies. Scenario-based landed-cost modeling should be standard in 2026 vendor selection.
- Patent chokepoints: Active EP patents on InP-based APD structures using mesa dark-current suppression create freedom-to-operate constraints in some regions. An explicit licensing and design-arounds strategy is essential for market entry in jurisdictions where these patents are enforced.
- Technology breakthroughs and product cadence: Breakthroughs in low-noise InGaAs and noiseless APD architectures can compress adoption cycles; keep R&D portfolios flexible to rapid component-level performance shifts.
2026 playbook — recommended executive actions
Translate insight into steps that materially reduce risk and create optionality:
- Institute dual-sourcing and a tiered qualification program for APD suppliers—prioritise suppliers that can demonstrate qualified production lines and traceable material supply.
- Hedge raw-material exposure through forward contracts or strategic inventory for indium/gallium; alternatively, explore material substitution or hybrid detector approaches for price-sensitive product lines.
- Invest in IP diligence and licensing early—identify blocking patents, engage in cross-licensing negotiations, and allocate budget for design-arounds where licensing is not feasible.
- Accelerate system-level integration capability—customers increasingly value pre-integrated modules (detector + front-end electronics); companies that migrate up the stack can capture higher margin and defensibility.
- Adopt tariff-aware manufacturing footprints—evaluate onshoring or nearshoring in light of potential duties and logistical risk, balancing CapEx versus recurring margin improvement.
- Shape M&A criteria around qualification assets and unique wavelength capability (e.g., 1,550 nm performance) rather than revenue alone; technical fit and supply stability are now primary value drivers.
How PW Consulting’s APD study de-risks 2026 choices
Our methodology combines bottom-up revenue reconstruction, primary interviews with procurement and R&D leaders, device-level performance benchmarking, plant-level supply-chain audits, and a patent landscape coupled with legal-impact scoring. The analysis includes concentration metrics and scenario-driven sensitivity tests that quantify the P&L and delivery implications of tariff, patent, and raw-material shocks — enabling executives to stress-test budgets and product launch timelines before committing capital.
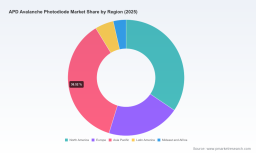
This preview intentionally presents strategic conclusions and executive actionables while withholding the granular segment breakouts and line-item tables that underpin our forecasts — the granular regional, type, and application splits are reserved for the full report and downloadable datasets. That design preserves the “trailer” function of this piece: build confidence in analytical rigor, while prompting direct access to the source for the detailed, transaction-grade intelligence necessary for procurement contracts, product roadmaps, and M&A diligence.
Next steps
For senior leaders preparing 2026 budgets, procurement cycles, or R&D roadmaps, the complete APD Avalanche Photodiode Market report provides the segment-level tables, supplier scorecards, and executable playbooks required to operationalize the above recommendations. Access to the full dataset and bespoke advisory briefings is available through PW Consulting’s market intelligence portal.
For detailed analysis of this topic, please visit the official page: APD Avalanche Photodiode Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com