

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
BDD Electrode Market to Reach USD 456 Million by 2032 — PW Consulting Insight

Boron Doped Diamond Electrode (BDD) Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
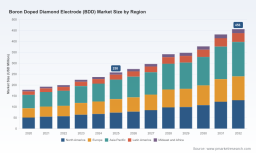
As PW Consulting’s lead industry analyst, I present a concise, decision-focused preview of our full Boron Doped Diamond Electrode (BDD) Market study (base year 2025). The BDD market has moved from a niche electrochemical specialty into a strategic enabling technology for industrial and municipal water treatment, analytical electrochemistry, and advanced synthesis. Our modelling—grounded in primary interviews, vendor cost benchmarking, and plant-level capacity analysis—shows a robust mid‑single‑digit to high‑single‑digit growth profile through the forecast period (2026–2032), with an enterprise‑grade compound annual growth rate (CAGR) of 8.5%. By 2025 the market reached a clear inflection point; our base-case projection anticipates continued expansion to a materially larger market by 2032 (all values expressed in USD Million, detailed breakdowns are available in the full report).
Boron Doped Diamond Electrode (BDD) Market
Why this matters for 2026 corporate strategy
- Regulatory-driven demand acceleration: Tightening regulation on persistent organic pollutants (notably PFAS) has elevated BDD-based electrochemical oxidation from pilot‑scale remediation to operationally preferred solutions for refractory contaminant destruction. Organizations planning 2026 capital cycles must treat BDD capability as a regulatory mitigation lever, not merely a technology option.
- Unit‑economics are now trackable: Over the last five years we observed a maturing supplier base and standardized cell architectures that make comparative total cost of ownership (TCO) assessments actionable. Buyers can move from qualitative vendor differentiation to procurement-enabled cost-per-pollutant metrics in 2026 negotiations—provided they access robust benchmarking data and validate on-site performance.
- Supply-chain and raw‑material sensitivity: The upstream boron market experienced volatility in late‑2025 across major producing regions. Procurement teams must incorporate hedging or supplier diversification into 2026 sourcing strategies to avoid short‑term price shocks that can erode project returns.
- Scale economics are real: The market’s trajectory indicates increasing returns to scale for manufacturers that integrate electrode fabrication with modular oxidation cells. Investors and industrial consumers evaluating partnerships or captive manufacturing should prioritize partners with demonstrable cell-level integration and service capabilities.
Market trajectory — what the headline numbers tell you
Historical evidence (2020–2025) shows accelerating adoption as technology readiness and regulatory pressures converged. Our forecast window (2026–2032) projects continued expansion at an 8.5% CAGR. For corporate planners, two takeaways are immediate: (1) the BDD market is no longer experimental—by mid‑decade it has reached scale that justifies dedicated R&D and procurement programs; (2) a multi‑scenario outlook is essential as the technology sits at the intersection of environmental regulation, raw‑material supply and modular manufacturing economics.
Boron Doped Diamond Electrode (BDD) Market
Competitive landscape — capabilities, gaps and strategic moves
The BDD vendor ecosystem combines specialist manufacturers, advanced materials incumbents, and technology integrators. Four players illustrate the spectrum of strategic postures we profile in depth:
Boron Doped Diamond Electrode (BDD) Market
- Boromond (Changsha, China) — A high‑velocity manufacturer with a broad portfolio spanning custom anodes, foam electrodes and integrated electrochemical oxidation modules targeted at industrial wastewater. Their active global trade show program and project marketing indicate a growth strategy focused on volume and turnkey solutions for high‑organic load effluents.
- pro aqua Diamantelektroden Produktion GmbH (Austria) — Patented and certified BDD technology aimed at sustainable water and process water applications. Their positioning is differentiated by regulatory-compliant certifications and systemization for municipal and pool water disinfection niches—appealing to operators prioritizing demonstrable compliance and long lifecycle performance.
- NeoCoat SA (Switzerland) — Supplier of polycrystalline BDD electrodes that bridges water treatment and analytical chemistry markets. Their value proposition centers on precision manufacturing and tailoring electrodes for analytical and synthesis applications where reproducibility and electrochemical characteristics are paramount.
- Element Six (Santa Clara, USA) — An advanced materials incumbent providing free‑standing polycrystalline BDD integrated into Diamox electrochemical oxidation cells, explicitly targeting advanced wastewater treatment and PFAS destruction. Element Six demonstrates how legacy materials capabilities can be translated into systems-level offerings with high technical credibility.
Strategically, these firms illustrate three viable go‑to‑market approaches for 2026+: (a) volume turnkey supplier, (b) certified systems provider for regulated municipal markets, and (c) high‑precision electrode specialist for analytical and synthesis end‑users. Corporates evaluating partnerships in 2026 should map their procurement and commercialization objectives to these archetypes.
Recent signals and what they reveal
- Commercial momentum and market outreach: Boromond’s participation in multiple 2025 trade shows signals proactive global commercialization efforts and a focus on project pipeline building outside core domestic markets.
- Academic‑industry integration: A recent on‑site inspection of a BDD technology project completed in partnership with a major Chinese university highlights ongoing collaboration patterns that accelerate process innovation and localized scaling—an important trend for firms seeking early access to application‑specific IP.
- Policy tailwinds: The tightening global regulatory framework around persistent pollutants is shifting procurement behavior from incumbent treatment arrays toward advanced oxidation. This change is particularly material for 2026 capital allocation cycles where compliance risk translates into faster payback expectations for BDD retrofit projects.
Risk profile — where executives must focus in 2026
- Input-cost volatility: Boron feedstock experienced an upward repricing episode in late 2025 across key supply basins. Buyers should model sensitivity of project economics to feedstock cost and engage in multi‑tiered supplier contracts or strategic inventory policies.
- Concentration versus commoditization: The market exhibits moderate concentration with several technically capable suppliers commanding meaningful share, yet the technology base is expanding. Competitive dynamics may compress margins for commoditized electrode formats while premium cell/system bundles retain pricing power.
- Validation and performance risk: Not all BDD implementations produce equivalent destruction rates for refractory pollutants. Corporates must insist on operational performance data under representative influent conditions and negotiate trial-to-scale contractual milestones.
Operational playbook for 2026 (recommended actions)
- Run prioritized pilot(s) now: Execute small‑scale, instrumented pilots across the highest‑impact sites (PFAS hot spots, high‑COD industrial wastewater). Collect electrochemical efficiency, maintenance cadence, and cell degradation data under production loads to de‑risk scale decisions.
- Procurement redesign: Move from unit price negotiations to TCO contracting—tie vendor compensation to pollutant removal metrics and service SLAs. Consider multi‑year supply agreements with indexed feedstock clauses.
- Partnerships over purchases: For organizations without core electrochemical expertise, prefer strategic partnerships or O&M joint ventures with system integrators that can warranty performance and assume technology risk.
- Hedge upstream exposure: Integrate raw‑material scenario planning into capex approvals. Where feasible, secure long‑term boron supply or evaluate alternative dopant strategies as contingency pathways.
- Technology scouting and IP due diligence: Prioritize vendors with verified cell architectures and demonstrable scaling roadmaps. For corporate venturing groups, early‑stage investments in electrode materials or modular cell innovations can accelerate strategic optionality.
What the full PW Consulting BDD report delivers (practical contents)
- Detailed market sizing and verified historicals (2020–2025) and granular forecasting scenarios for 2026–2032, inclusive of sensitivity and policy‑shock permutations.
- Supplier benchmarking with scorecards on technology, manufacturing scale, service models, and proven applications—designed for procurement and M&A diligence.
- Operator case studies and pilot data templates to fast‑track on‑site evaluation and third‑party verification protocols.
- Unit‑economics and TCO models for common deployment archetypes (retrofit, modular skid, centralized plant), including capex/opex drivers and break‑even horizons under multiple feedstock price scenarios.
- Regulatory mapping and scenario planning focused on PFAS and POPs dynamics, plus recommended compliance strategies for water utilities and industrial operators.
- Strategic playbook for investors, technology acquirers and industrial buyers covering partnerships, vertical integration, and carve‑out opportunities.
Note: To preserve the strategic value of the analysis and to align with our “teaser” approach, the full report contains the granular regional and application-level splits, vendor market share tables, and modelled price curves required for transaction-grade diligence.
Closing recommendation — the 60‑day checklist for CxOs
- Authorize at least one instrumented pilot targeting a regulatory‑driven use case (e.g., PFAS or refractory industrial organics).
- Initiate supplier pre‑qualification focusing on system warranties, performance guarantees and raw‑material sourcing resilience.
- Embed feedstock price sensitivity into 2026 capex approvals and require vendors to demonstrate feedstock pass‑through mechanisms where appropriate.
- Schedule a strategic vendor workshop (technical + procurement) to align on KPIs, trial acceptance criteria and commercial models.
Our full PW Consulting BDD Market report is structured to convert these strategic imperatives into executable plans—complete with the quantitative inputs, vendor scores and scenario models required for procurement, investment and regulatory compliance decisions in 2026. For access to the granular datasets, regional and application splits, and downloadable financial models, please visit the PW Consulting report page or contact our industry desk for an executive briefing.
For detailed analysis of this topic, please visit the official page: Boron Doped Diamond Electrode (BDD) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com