

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: HPC market at USD 2,310.7M in 2026; 2.45% CAGR

Hydro‑processing Catalysts (HPC) Market: Strategic Briefing for 2026 Decisions
As Senior Strategy Consultant and Chief Industry Analyst at PW Consulting, I present a focused, executive-grade briefing on the Hydro‑processing Catalysts (HPC) market intended to frame the strategic choices that matter in 2026. This briefing synthesizes our proprietary market modeling (base year 2025, historical window 2020–2025, forecasting through 2026–2032) and translates technical and regulatory complexity into clear decision levers for refiners, catalyst manufacturers, investors and engineering partners.
Hydro-processing Catalysts (HPC) Market
Why this study matters now
The HPC market is in a phase of steady, structurally driven evolution. Our top‑line model shows a market that expanded from roughly USD 2.0 billion (2020) to about USD 2.27 billion (2025), and — under our central scenario — is forecast to continue growing to an upper‑mid single‑digit trajectory by the end of the 2026–2032 horizon (model CAGR: 2.45% in USD terms). The market exhibits moderate concentration (CR3 ~55%; CR5 ~70%), meaning strategic interactions among a handful of global suppliers will materially affect price, availability and technology diffusion for buyers.
Hydro-processing Catalysts (HPC) Market
Why should executives care? Because these aggregate dynamics mask high strategic asymmetries: small improvements in catalyst life, sulfur removal efficiency, or resistance to contaminant-induced deactivation can change refinery margins on fuel pools and accelerate decarbonization paths for renewable diesel and SAF (Sustainable Aviation Fuel) projects. The choices organizations make in 2026 around supplier selection, pilot‑to‑commercial scale validation, and feedstock management will determine performance and unit economics for the next decade.
Hydro-processing Catalysts (HPC) Market
What the PW Consulting report delivers (practical modules)
- Market sizing and demand scenarios — transparent methodology for historical (2020–2025) and forecast (2026–2032) outlooks, with sensitivity runs reflecting regulatory and feedstock shocks.
- Commercial readiness & piloting playbook — step‑by‑step guidance for pilot plant testing, scale‑up pitfalls, and KPI templates (activity, selectivity, conversion, cycle length) to validate vendors before capital commit.
- Supplier benchmarking and negotiation toolkit — qualitative and quantitative supplier scorecards, performance proxies and contracting levers tailored for short‑ and long‑term procurement strategies.
- Feedstock & operational risk map — practical mitigation actions for chloride loading, metals deposition and other feed contaminants that materially shorten catalyst life.
- Compliance and market access roadmap — regulatory impact matrix (including RED and EPA implications), compliance cost estimates, and prioritized responses by market segment.
- M&A and partnership screening— acquisition targets, bolt‑on technology plays and JV models to gain catalytic capability in renewable fuels and resid upgrading.
- Investor due diligence annex — key commercial metrics, break‑even sensitivity and an investment checklist for private equity and strategic buyers.
Core market dynamics shaping near‑term decisions
- Regulatory tightening is a determinative force. The move from voluntary low‑sulfur initiatives to binding regimes — including intensified enforcement and evolving EU renewable mandates — is changing minimum performance requirements for hydrotreating and hydrocracking catalysts. Compliance is necessary but not sufficient: the most advantaged refiners will require catalysts that enable lower total cost of ownership (longer cycle lengths + higher conversion under tougher feedstocks).
- Feedstock complexity and contaminant sensitivity. Elevated chloride levels and other contaminants continue to be a dominant technical challenge. These impurities accelerate corrosion and plugging, and they cause non‑linear declines in catalyst activity. Our field surveys show that pre‑emptive feedstock conditioning and targeted catalyst formulations materially extend cycle life.
- De‑risking through pilot validation. Pilot plant testing remains indispensable; bench tests and vendor claims are necessary but insufficient. Commercial deployment must be preceded by pilot validation of activity, selectivity and conversion under representative contaminated feeds — and by rapid feedback loops between operations and R&D.
- Supplier economics and market concentration. A moderate supplier concentration means supply shocks, pricing moves, or a single vendor’s process breakthrough can ripple through contract negotiations and CAPEX plans. Expect suppliers to leverage bundled offerings (catalyst + services + spent catalyst management) to protect margins and lock in customers.
Competitive landscape — strategic implications
The HPC supplier base blends long‑established catalyst innovators with service specialists and integrated chemical companies. Key players active in the market include Advanced Refining Technologies (ART Hydroprocessing), Ketjen Corporation, Haldor Topsøe, Axens, Johnson Matthey, Evonik and Albemarle among others. Each brings distinct strengths:
- Technology leaders (e.g., Haldor Topsøe, Axens, Johnson Matthey) — deep IP in hydrotreating/hydrocracking catalysts and integrated licensing/engineering support; advantageous for complex grassroots or revamp projects.
- Specialists and solutions providers (e.g., ART Hydroprocessing) — focus on resid/upgrading and ebullated bed solutions; valuable in high‑contaminant resid applications and renewables conversion.
- Service and lifecycle players (e.g., Evonik) — differentiated by spent catalyst management, regeneration and value recovery services that reduce total environmental and economic footprint.
- Consolidators (e.g., Albemarle integrating Ketjen) — M&A and portfolio rationalization increase scale but may compress pricing flexibility; watch for post‑acquisition integration risks and potential shifts in product roadmaps and customer service models.
Notably, a January 2026 pricing adjustment announced by a major supplier underscores that pricing and contractual structures remain fluid; buyers should build flexible procurement clauses and staged purchase commitments to mitigate short‑term cost shocks while preserving access to critical technologies.
Actionable agenda for 2026: 90‑day and 12‑month priorities
- Next 90 days — Tactical triage
- Initiate pilot plant engagements for any new catalyst technology under consideration; require representative feedstock runs and vendor KPIs contractually.
- Inventory and test feedstock impurity levels (chlorides, metals); prioritize conditioning investments where impurity loads materially reduce catalyst life.
- Review existing supplier contracts for indexation clauses and flex provisions; negotiate short‑term options to insulate against announced price adjustments.
- Next 12 months — Strategic positioning
- Launch a total cost of ownership (TCO) benchmarking exercise across existing units vs. alternative catalyst technologies, including service and spent catalyst recovery economics.
- Pursue strategic partnerships or co‑development agreements with supplier(s) that align on renewable fuel roadmaps (renewable diesel / SAF) to secure preferential access to next‑gen formulations.
- Embed regulatory scenario planning (RED III, state and national sulfur mandates) into capital planning and feedstock procurement.
How operators, suppliers and investors should read this report
- Refinery operators: Treat catalyst selection as a portfolio decision. Balance immediate sulfur/compliance needs with long‑run renewables and resid upgrading pathways. Operational practices (feed pre‑treatment, cold‑start protocols, monitoring) often yield more value than incremental per‑kg catalyst savings.
- Suppliers & OEMs: The premium sits with partners who bundle predictable cycle life with upstream feedstock services and downstream spent catalyst solutions. Demonstrable field data from pilot deployments will accelerate commercial uptake.
- Investors & acquirers: Look beyond headline market growth. With CR3/CR5 concentration and differentiated IP, value creation will come from owning service networks, regeneration capabilities and targeted tech that reduces OPEX and compliance cost for refineries.
What we withheld — why you will want the full report
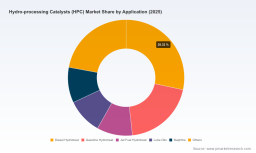
In keeping with a “trailer” approach, this overview surfaces the strategic signals and executive actions that matter in 2026 while intentionally withholding the underlying granular segmentation and proprietary scenario tables: detailed regional and application splits, vendor‑level market shares, price‑sensitivity matrices, and the full supplier scorecards are reserved for the complete study. Those datasets are the operational weapons that enable contract clauses, CAPEX sizing, and M&A valuation adjustments — and they are best accessed through our full report where we provide model files, sector‑specific playbooks and validation checkpoints.
Concluding recommendation
Hydro‑processing catalysts sit at the intersection of regulatory pressure, feedstock evolution and technology differentiation. The 2026 inflection point is real: organizations that combine rigorous pilot validation, disciplined procurement design and selective strategic partnerships will unlock outsized operational and economic outcomes. PW Consulting’s full HPC Market study provides the data, scenarios and tactical playbooks required to convert that strategic imperative into measurable results.
For procurement teams, operations leaders and investors preparing 2026 budgets and M&A pipelines, the question is not whether to engage — it’s how quickly you can put pilot‑validated, cost‑of‑ownership analyses and flexible supplier agreements in place. Our report gives you the framework and the empirical inputs to do exactly that.
For detailed analysis of this topic, please visit the official page: Hydro-processing Catalysts (HPC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com