

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Nylon Cable Ties Market to hit USD 202.57 Million in 2026, 5.71% CAGR

Nylon Cable Ties Market — Strategic Outlook for 2026 Decision‑Makers
As corporate procurement cycles, capex debates, and product roadmaps intensify for 2026, nylon cable ties — a deceptively simple category — are at a strategic inflection point. PW Consulting’s latest Nylon Cable Ties Market study (base year 2025, historical coverage 2020–2025, forecast 2026–2032) synthesizes demand, supply, regulatory shifts, and competitive moves into an operational playbook designed for senior leaders who must convert modest unit-cost products into reliable margin and risk levers.
Nylon Cable Ties Market
Why this report matters for 2026 decisions
The global nylon cable ties market is not a static commodity market; it is growing and evolving. Our topline projection shows the market expanding at a compound annual growth rate (CAGR) of 5.71% over the forecast window, with overall market value rising from the mid‑hundreds of millions (USD, Million unit basis) in 2025 into materially higher levels by the early 2030s. That growth, while moderate, masks critical inflection drivers — raw material volatility, product differentiation (UV‑resistance, flame retardancy, detectable/releasable designs), and an uneven regional manufacturing footprint — each of which carries actionable implications for sourcing, pricing, and capacity planning in 2026.
Nylon Cable Ties Market
What executives will find actionable
-
Procurement playbook: a short list of hedging and contract structures calibrated to a market where PA66 feedstock prices experienced meaningful upward pressure during 2023–2024.
Nylon Cable Ties Market -
Product strategy levers: prioritized design attributes and certification pathways that materially improve acceptance in electrical, automotive, and industrial end markets without a proportional increase in unit cost.
-
Manufacturing & footprint decisions: a decision tree that weighs the economics of localized capacity versus centralized low‑cost production, taking into account trade policy, talent availability, and growing regional demand pockets.
-
M&A and partnering targets: a screened list of candidate OEMs and toll‑manufacturing partners that could close capability gaps for UV‑resistant, flame‑retardant, or recycled‑content product lines.
-
Regulatory & sustainability route maps: step‑by‑step compliance and product labeling interventions to serve eco‑conscious procurement specifications being introduced in multiple advanced markets.
Core market dynamics — distilled for strategy
Three dynamics are shaping near‑term commercial choices:
-
Raw material volatility: The PA66 resin squeeze of 2024 — with feedstock costs rising materially versus the prior year — compressed margins across producers, particularly those with thin pricing power. That dynamic increases the value of multi‑year purchase agreements, resin pass‑through clauses, and vertical supplier partnerships in 2026 procurement negotiations.
-
Product premiumization & compliance: OEMs and industrial buyers are increasingly specifying higher‑performance attributes (UV resistance, flame retardancy, detectable materials, recyclable content). This is elevating R&D and tooling spend into the center of competitive differentiation and creating opportunities for suppliers who can combine performance with traceable sustainability credentials.
-
Localization and capacity reshaping: Large suppliers have continued to invest in regional manufacturing footprints to capture lead times, local content mandates, and on‑the‑ground engineering support. These investments change the calculus for buyers evaluating total cost of ownership (TCO) versus unit price.
Competitive landscape — not just names, but strategic postures
The market exhibits moderate concentration (top‑three players command a material share while the top five accumulate a clear majority). That structure creates a dual dynamic: established majors can set technical and quality benchmarks, while a broad long tail of regional players competes on price, service, or niche capabilities. Below is a concise profile of the strategic postures we evaluated.
-
Panduit Corp. — A specialization strategy focused on engineered nylon 6.6 products and low‑carbon recycled options. Their value proposition centers on higher performance, lifecycle emissions reduction, and application engineering for electrical and networking systems.
-
HellermannTyton — Diversified product breadth with an emphasis on industrial and automotive specifications. Recent investments in advanced manufacturing and digital tagging (RFID) indicate a play for systems‑level integration and traceability that appeals to automated assembly environments.
-
ABB Ltd. (Thomas & Betts) — Global brand leveraging legacy relationships in electrification and industrial wiring. Their product innovations concentrate on labor savings and standardized performance for harnessing and industrial installations.
-
Leading Chinese and regional manufacturers (representative firms across Zhejiang and Wenzhou) — Compete on scale, lead‑time flexibility, and breadth of SKUs, including variants with stainless steel locks and thermal‑shrink accessories. These players are essential partners for global buyers seeking cost levers or high‑volume supply continuity.
Recent developments underline these strategic moves. For example, a major supplier accelerated regional capacity expansion in India during 2025–2026 to support automotive and industrial demand, and another has rolled out RFID‑enabled dual‑lock products with strong uptake across assembly plants. These real‑world actions inform where supply resilience and product differentiation will matter most in 2026 negotiations.
What the full report contains (practical deliverables)
PW Consulting’s full study goes well beyond macro forecasts. It is organized to support immediate decision‑making in procurement, product development, and corporate strategy:
-
Revenue and volume modeling through 2032 with scenario paths for low/high raw‑material cost environments.
-
A vendor matrix and capability heatmap covering mechanical specs, material types, sustainability credentials, and regional footprint.
-
Supply‑chain stress tests that quantify exposure to resin price shocks, container/logistics cost spikes, and single‑source dependencies.
-
Pricing curves and margin sensitivity tables to model pass‑through strategies and contract structures.
-
Regulatory tracker and compliance checklists tailored to major markets (electrical safety, recyclability, detectable materials), plus a roadmap to certify new product variants.
-
An M&A and partnership scouting brief with prioritization logic, estimated realization timelines, and integration risk checklists.
-
Operational playbooks for quality assurance, testing protocols, and industrial automation options that reduce labor intensity without sacrificing reliability.
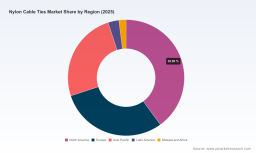
Note: To preserve strategic value for paying subscribers, detailed segment tables and granular regional/application splits are included only in the full report. The summary here intentionally omits those line‑by‑line segment figures, while providing the analytical scaffolding needed to act.
Implications and recommended actions for 2026
Translate insight into immediate action with a three‑track plan tailored to 2026 cycles:
-
Procurement & cost management: Revisit supplier contracts with explicit resin price clauses, secure multi‑tiered supply commitments for critical grades (including PA66), and run a reverse auction for non‑strategic SKUs. Consider pilot long‑term purchase agreements with options for recycled feedstocks to stabilize cost and improve ESG signaling.
-
Portfolio & product strategy: Prioritize a small set of high‑value SKUs (UV‑resistant and flame‑retardant variants) for premium positioning in electrification and automotive markets. Simultaneously, invest in a detectable/releasable line for regulated industries where faster adoption is expected.
-
Manufacturing & partnership design: Evaluate regional capacity expansion or tolling arrangements in target markets to reduce lead times and exposure to freight volatility. For large OEMs, co‑investment models with strategic suppliers can secure capacity while sharing the capex risk.
Risk radar — what could materially alter the outlook
-
Raw material supply shocks or sustained energy cost increases that push PA66 prices above modeled stress thresholds.
-
Rapid tightening of environmental regulations (extended producer responsibility, recycled content mandates) in key buy‑side markets that accelerate product re‑specification cycles.
-
Geopolitical or trade disruptions that make previously reliable low‑cost supply routes uneconomical or unavailable.
Final thoughts — how to use this research in 2026 planning
For leadership teams preparing budgets, supplier scorecards, or product investments in 2026, the choice is not whether to engage with the nylon cable‑tie category — it is how actively to manage it. With a modest but steady market growth trajectory and concentrated incumbents setting technical standards, the category rewards smart combinations of supply certainty, selective product premiumization, and regulatory foresight.
PW Consulting’s Nylon Cable Ties Market study provides the forecast scaffolding, supplier intelligence, and operational templates necessary to convert market signals into defensible commercial moves. The executive summary above highlights the strategic implications and recommended actions; the full report supplies the segment‑level data, vendor comparisons, and scenario tables that procurement and product teams will need to finalize 2026 plans.
Accessing the full intelligence
To obtain the detailed segment breakdowns, supplier dossiers, and the complete toolkit for 2026 decision execution, please consult the full report on PW Consulting’s report page. That content contains the granular tables and data visualizations necessary to convert this strategic preview into tactical steps and measurable targets.
For detailed analysis of this topic, please visit the official page: Nylon Cable Ties Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com