

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: VAE Emulsions to Hit USD 320.42 Million by 2032 at 5.98% CAGR

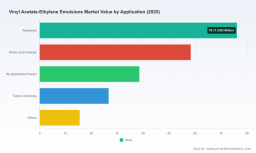
Vinyl Acetate‑Ethylene (VAE) Emulsions: Strategic Intelligence Brief for 2026 Decision‑Makers
PW Consulting’s latest market study on Vinyl Acetate‑Ethylene emulsions delivers a focused intelligence product designed to inform strategic investment, procurement, and product development decisions in 2026. Built on a historical window from 2020–2025 (base year 2025) and forward‑looking through 2026–2032, the study quantifies the market trajectory, identifies structural risks, profiles leading suppliers, and translates technical trends into executable corporate plays. The total market expanded from approximately USD 161 million in 2020 to USD 215 million in 2025 and is forecast to grow to roughly USD 320 million by 2032, representing a compound annual growth rate (CAGR) of 5.98% over the forecast period—figures we use as the foundation for scenario planning and risk stress tests that matter to C‑suite and business‑unit leaders.
Vinyl Acetate-Ethylene Emulsions Market
Why this study matters for 2026 strategy
-
Timing for strategic inflection: 2026 is shaping up as a year when raw‑material volatility and logistics constraints will begin to translate into persistent cost and capacity shifts. Companies that act now — on secured feedstock arrangements, formulation pivots, and targeted M&A — will enter 2027 from a position of advantage.
Vinyl Acetate-Ethylene Emulsions Market -
Actionable, not academic: the report moves beyond descriptive statistics to deliver procurement playbooks, product roadmaps, and an M&A target map calibrated to different risk appetites and balance‑sheet profiles.
Vinyl Acetate-Ethylene Emulsions Market -
Portfolio prioritization: with modest but steady market growth (CAGR ~6%), the choice is not simply to “grow or exit” but to decide where to invest for differentiated returns — higher‑margin specialty VAE chemistries, service‑led formulations, or scale‑driven commodity volumes. We show how to make those allocation decisions based on profitability and resilience metrics.
Key market dynamics and what they mean for 2026
-
Feedstock and logistics pressure: raw material feeds matter. In Q1 2026, global vinyl acetate prices rose on tighter acetic‑acid availability and elevated freight costs (Analysts Insights, March 2026). Simultaneously, ethylene transport challenges are increasing the landed costs of a key monomer (Sector Analysis, 2026). The combined effect is asymmetric: margin pressure on commodity VAE grades and an accelerating premium for formulations that reduce VOCs or enable lower application energy.
-
Supply‑side concentration and fragmentation: the market sits in a middle state of concentration — the top three players account for a meaningful share without creating a classical oligopoly. This structure leaves room for regional champions, but it also means pricing discipline can change quickly when one large supplier compounds outages with aggressive pricing.
-
End‑use demand evolution: demand drivers remain tied to construction cycles, adhesives innovation, and coatings sustainability standards. While overall volume growth is predictable, value growth will increasingly favor specialty emulsions (low‑odor/low‑VOC, redispersible powders, and polymer blends tailored to novel substrates).
-
Regulatory and sustainability momentum: regulatory attention on VOCs and embodied carbon is intensifying R&D commitments. Companies that can demonstrate lower lifecycle emissions or enable product substitution in high‑regulation geographies will command pricing power and access to preferential procurement pipelines.
Competitive landscape — what leading suppliers are positioning to win
Our competitive analysis profiles incumbent and challenger strategies across technology, go‑to‑market, and vertical focus. We assess capabilities, commercial footprint, and strategic intent for core players documented in the market.
-
Mallard Creek Polymers LLC (United States) — https://www.mcpolymers.com Strength: product lines such as Rovene® and Tylac® indicate a deliberate focus on construction adhesives, architectural coatings, and redispersible powder technologies. Strategic posture: deepen integration with construction formulators and capture share in mineral‑bound applications where performance requirements favor tailored chemistries.
-
Celanese Corporation (United States) — https://www.celanese.com Strength: EcoVAE® low‑odor/low‑VOC offerings signal a sustainability‑oriented product strategy that aligns with tightening environmental standards in coatings. Strategic posture: leverage large‑scale petrochemical integration and low‑VOC credentials to win specification contracts with major coatings formulators.
-
Wacker Chemie AG (Germany) — https://www.wacker.com Strength: VINNAPAS® and ETONIS® co‑ and terpolymer dispersions position Wacker across adhesives, architectural coatings, construction, and nonwovens. Strategic posture: combine polymer science leadership with global application labs to convert product innovation into system‑level specifications.
-
Vinavil S.p.A. (Italy) — https://www.vinavil.com Strength: VINAVIL EVA® copolymer dispersions point to a heritage in adhesives and construction markets. Strategic posture: exploit customer intimacy in European construction markets and pursue selective product adjacencies that raise ASPs.
-
Dairen Chemical Corporation (Taiwan) — https://www.dcc.com.tw Strength: breadth across adhesives, construction, packaging, and paints with regional cost competitiveness. Strategic posture: scale regional volumes while exploring premiumization routes through formulation services and specialized grades.
Collectively, these firms illustrate three winning moves in 2026: (1) product differentiation around low‑VOC/sustainability claims; (2) tighter integration with end‑use formulators through co‑development and lab‑as‑service offerings; and (3) supply‑chain initiatives to mitigate feedstock and logistics risk. The market concentration metrics in our study — where the top three and top five players account for substantial shares — imply that competitive actions by a handful of companies will continue to ripple across prices and availability.
What the full report delivers — practical modules in the deck
For executives who need to convert insight into action, the report is organized into operationally useful modules:
-
Market sizing and forecast model (2020–2032) with base‑case, upside, and downside scenarios; interactive spreadsheets allow you to test your own assumptions against our baseline CAGR of 5.98%.
-
Segment playbooks that map commercial levers to margin outcomes — by product type, application category, and route‑to‑market (note: detailed segment tables are reserved for the full report).
-
Procurement and feedstock risk dashboard with supplier heatmaps, contract templates, and hedging alternatives tied to acetic acid and ethylene exposure.
-
Technology and innovation map showcasing R&D pipelines (e.g., redispersible powders, terpolymer architectures, low‑odor emulsions) and their likely commercialization timelines.
-
Competitive profiles and a short list of M&A and joint‑venture targets prioritized by strategic fit and execution risk.
-
Regulatory and sustainability playbook outlining compliance imperatives and value capture opportunities from lower‑carbon products.
Strategic playbook for 2026 — recommended moves
-
Lock in feedstock flexibility: renegotiate supplier contracts to include volume‑option clauses, explore multi‑sourcing or short‑term tolling arrangements, and evaluate backward integration where economics justify. Given the Q1 2026 feedstock tightness, the cost of inaction is asymmetric.
-
Prioritize high‑value formulation lanes: accelerate commercialization of low‑VOC and application‑specific grades that permit premium pricing and longer contract terms with formulators and OEMs.
-
Build service‑led differentiation: offer formulation support, onsite lab pilots, and digital tools (e.g., predictive performance models) to deepen customer stickiness and offset commoditization pressure.
-
Prepare for targeted M&A: identify smaller specialty polymer houses or application‑focused formulators that can add margin accretion and new specification channels; use the deal window created by feedstock volatility to negotiate favorable terms.
-
Stress‑test logistics and route planning: run contingency simulations for transport disruptions—especially ethylene logistics—and re‑route capacity where storage economics allow to smooth supply.
-
Embed sustainability into the product P&L: quantify the price uplift achievable for low‑carbon or low‑VOC variants and incorporate lifecycle metrics into customer negotiations when seeking long‑term contracts.
How executives should use this intelligence in 90, 180, 365 day horizons
-
90 days: conduct an exposure sweep—map current feedstock contracts, identify single‑source risks, and begin priority discussions with alternate suppliers.
-
180 days: pilot at least one formulation partnership that targets a premium application; implement short‑term procurement hedges and operational contingency plans for logistics.
-
365 days: execute a resource allocation decision—scale the winning formulation, pursue targeted acquisitions if indicated, and lock in multiyear offtake or specification agreements.
Conclusion and next steps
VAE emulsions represent a mature but evolving market: modest overall growth masks strategic inflection points created by raw‑material volatility, sustainability regulation, and application‑led premiumization. PW Consulting’s study offers the models and playbooks to convert these trends into defensible competitive advantage in 2026 and beyond. For teams preparing procurement cycles, R&D roadmaps, or transaction strategies this year, the report provides the scenarios, supplier maps, and negotiation tools needed to act with confidence.
To review the full segmentation tables, downloadable models, and vendor scorecards that underpin the summary above, access the complete report and supporting client deliverables on our publication page. PW Consulting can also arrange a tailored briefing to align the findings to your balance‑sheet and strategic objectives.
For detailed analysis of this topic, please visit the official page: Vinyl Acetate-Ethylene Emulsions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com