

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Fiber Optic Preform Market to Hit USD 30,000M by 2032 at 20.39% CAGR

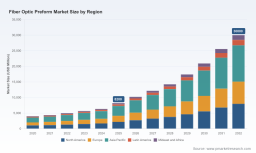
Fiber Optic Preform Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As global bandwidth demand accelerates and network architectures evolve, the fiber optic preform market is entering a decisive growth phase. PW Consulting’s latest study (base year 2025, forecast 2026–2032) shows the industry transitioning from a multi-year recovery toward structurally higher growth — driven by densification of access networks, hyperscale data center expansion, and renewals of long-haul infrastructure. The market’s compound annual growth rate is estimated at roughly 20.4% going into the 2026–2032 window, and the overall market scale moves from early-decade billions to a materially larger market by the end of the forecast. This preview explains why the study matters for executives making capital, sourcing, and M&A decisions in 2026, and what pragmatic steps fast-moving companies are taking now.
Fiber Optic Preform Market
Why this report matters for 2026 decision-makers
-
Timing an inflection: 2026 is a turning point where demand recovery, price normalization, and persistent supply-side constraints converge. Firms that align procurement, capacity planning, and commercial models to this inflection will avoid the reactive cost and delivery pressures that characterized 2024–2025.
Fiber Optic Preform Market -
High-stakes supply risk: The supply chain for specialty dopants and precursor materials has moved from “manageable volatility” to strategic fragility. Export controls, trade remedies, and concentrated upstream supply put preform producers and their customers on shared risk pathways; informed contract design and source diversification are now board-level issues.
Fiber Optic Preform Market -
Capital allocation clarity: With an expected high-growth trajectory through 2032, decisions on incremental capacity, process upgrades, or strategic partnerships require granular scenario analysis. The study provides the financial cadence and trigger points that help prioritize CapEx vs. contract-based capacity expansion.
Market dynamics shaping 2026 strategy
-
Demand drivers — Beyond headline bandwidth: Demand is not solely about more fiber kilometers. It is being reshaped by higher-specification fibers for cloud fabrics, low-latency metro rings, and specialized industrial/medical applications. This creates differentiated preform requirements that favor manufacturers with process flexibility and rapid qualification capabilities.
-
Raw-material and regulatory shocks: Over recent years, dopant markets and precursor supply chains have tightened and experienced sharp price inflation and trade-policy disruption. Export licensing and prohibitions from key producing countries have extended lead times and amplified unit-cost risk. Procurement strategies that rely on single-source dopant supplies are now a source of margin volatility.
-
Price normalization and margin pressure: After a trough in fiber pricing, market prices have been on a strong rebound. That rebound will coexist with higher input costs and shifting freight/regulatory tariffs — creating windows for margin recovery but also scenarios where price pass-through and contractual indexation will determine winners and losers.
-
Technology and process competition: Multiple deposition and preform production routes remain commercially relevant. Companies that maintain a portfolio of process capabilities (axial and radial vapor deposition variants, preform machining and synthetic quartz approaches) have greater optionality to respond to raw-material constraints and product-quality requirements.
What our report delivers — practical, decision-grade assets
-
Actionable market-sizing and forecast model calibrated to 2025 actuals and stress-tested across three demand scenarios for 2026–2032.
-
Supplier and technology scorecards that benchmark throughput, process mix flexibility, vertical integration, and qualification timelines for specialty fibers.
-
Supply-chain heatmaps that identify single points of failure — including dopant and precursor concentration — and recommend tactical hedges and contractual structures.
-
CapEx playbook with go/no-go triggers, lead-time calendars, and ROI sensitivity tied to market-price recovery and capacity utilization assumptions.
-
Commercial playbook for buyers and sellers: indexation clauses, step-up volume discounts, inventory financing options, and fast-track qualification plans for new preform suppliers.
-
M&A and partnership scanner identifying target types, valuation lenses, and integration risks for firms seeking to secure feedstock, expand capacity, or acquire process know-how.
Competitive landscape — how incumbents are positioned
The market features established manufacturers with deep process expertise and scale, alongside regional challengers focused on price and local delivery. Leading global names are deploying different strategic responses:
-
Corning Incorporated leverages large-scale vapor deposition capabilities and integrated fiber drawing to serve telecommunications and data-center customers; its scale and process know-how make it a logical counterparty for long-term supply agreements.
-
Japan-based industrial groups such as Sumitomo Electric and Fujikura emphasize high-quality VAD and specialty preforms tailored to telecom and industrial use cases, focusing on reliability and qualification speed.
-
Materials specialists like Shin-Etsu hold unique positions through advanced synthetic quartz preforms and large-diameter capabilities, which matter for certain high-performance fiber applications and downstream diversity.
-
Cable and systems manufacturers (including major European and Chinese groups) use vertical integration and contract manufacturing strategies to control final product cost and delivery. Some combine in-house preform production with third-party sourcing to manage flexibility.
-
Regional manufacturers in Asia are expanding capacity and pursuing aggressive commercial offers; for buyers, this increases sourcing options but also requires rigorous qualification and contractual risk management.
In aggregate, the market’s competitive dynamics point to concentrated capability at the top with meaningful room for niche and regional players — creating opportunities for offtake agreements, tolling arrangements, and strategic partnerships rather than outright greenfield expansion for every participant.
Recommended 2026 playbook — nine practical moves
-
Move from spot buying to layered contracts: blend short-term flexible volumes with locked long-term offtake to balance price exposure and guaranteed capacity.
-
Secure alternative dopant pathways: invest in qualification of substitute chemistries and secondary suppliers to reduce single-point concentration risk.
-
Implement dynamic pricing clauses: tie pass-through mechanisms to validated input indices and add short-term repricing windows for sharp input dislocations.
-
Stage capital investments to trigger points: use our scenario model to define utilization thresholds that justify expansion versus contracting capacity.
-
Forge manufacturing partnerships: consider tolling, joint ventures, or capacity reservation deals to accelerate access to qualified preforms without full greenfield exposure.
-
Prioritize qualification speed: shorten product-qualification cycles through joint qualification labs and pre-approved test protocols to unlock supply faster.
-
Enhance inventory and logistics playbooks: centralize critical dopant inventory, ensure alternate freight lanes, and model tariff impacts in landed-cost scenarios.
-
Scan for bolt-on M&A: prioritize targets that provide dopant/specialty-material access, process IP, or fast-entry into strategic geographies.
-
Stress-test commercial relationships against regulatory shocks: design termination, force majeure, and substitution clauses cognizant of export controls and trade measures.
Decision calendar: what to act on in H1–H2 2026
-
H1 2026 — procurement and contracting: finalize layered contract frameworks and secure preliminary supply reservations tied to critical product families.
-
Mid-2026 — capacity and partnerships: commit to staged capacity expansions or preferred-supplier partnerships once utilization and price-recovery signals reach defined thresholds.
-
H2 2026 — capital allocation and M&A: execute on targeted investments and selective acquisitions when scenario-based NPV analyses validate deployment versus leasing or tolling alternatives.
Where PW Consulting adds unique value
Our study combines a high-granularity forecast model calibrated to 2025 outcomes with supplier benchmarking, regulatory-impact simulations, and commercial playbooks designed for rapid implementation. We translate macro trajectories and supply shocks into a short list of executable decisions — contract terms, sourcing hedges, and CapEx triggers — that executives can place on the 2026 boardroom agenda. To preserve commercial sensitivity, this preview highlights strategic themes; the full report provides the underlying tables, process-level demand curves, supplier scorecards, and actionable templates that procurement, operations, and corporate development teams need to execute confidently.
Next step
For companies making sourcing, capacity, or M&A decisions in 2026, the questions are no longer whether the market will grow, but how to capture value while managing concentrated upstream risk and evolving regulatory constraints. PW Consulting’s complete Fiber Optic Preform Market report delivers the granular inputs and executable playbooks required to convert the sector’s projected growth into sustainable margin and capacity advantage. Contact our team to access the full analysis, including the detailed segmentation, supplier matrices, and scenario-model workbooks that underpin the recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Fiber Optic Preform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com