

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Steam Trap Valve Market Poised to Hit USD 549M by 2032 at 4.4% CAGR

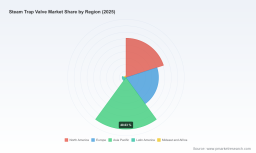
Steam Trap Valve Market — Strategic Outlook for 2026 Decision‑Making
As companies set capital allocation and procurement priorities for 2026, steam trap valves are resurfacing as a discreet yet high‑impact lever in energy, process efficiency and compliance strategies. PW Consulting’s latest Steam Trap Valve Market study (base year: 2025; historical: 2020–2025; forecast: 2026–2032) synthesizes market dynamics, vendor evolution and operational playbooks that executives need to translate a modestly growing market into outsized operational value. The global market — measured in USD Million — progressed from a documented baseline in 2020 to USD 407.6 Million in the 2025 base year and is projected to continue expanding at a compound annual growth rate (CAGR) of 4.4% through the 2026–2032 forecast window, reaching an expected USD 549.0 Million by 2032. This trajectory underpins near‑term choices on capex, aftermarket services and digital investments.
Steam Trap Valve Market
Why this matters for 2026 planning
-
Energy efficiency and cost control are converging with digitalization. Steam systems remain a prime vector for measurable energy recovery, and improvements in steam trap selection, monitoring and maintenance translate directly into reduced fuel consumption and lower CO2 emissions — outcomes that are monetizable in 2026 planning cycles.
Steam Trap Valve Market -
Regulatory tightening and verification requirements are shifting responsibility from facility managers to corporate compliance teams. Codes such as ASME requirements and recent regulations (e.g., California’s Title 24 updates) increase the need for documented acceptance testing, certified installations and traceable failure detection — all of which affect procurement specs and vendor selection.
Steam Trap Valve Market -
Supply‑side pressures (notably inflationary movement in stainless steel and copper during 2024–2025) change negotiating dynamics with OEMs and component suppliers, creating an opportunity for buyers to lock favorable terms or redesign for alternative materials where appropriate.
Market trajectory & strategic implications
The market’s steady recovery and forecasted expansion at a 4.4% CAGR belies important structural shifts. Growth is not being driven purely by volume replacement; it is being shaped by three converging forces: sensorization and predictive maintenance, heightened regulatory scrutiny, and differentiated product engineering (e.g., high‑capacity and alloy‑rated designs for extreme conditions). For 2026 decision‑makers, the implication is clear: procurement that treats steam traps as “commodity” items is missing a broader value chain — one that includes digital monitoring, lifecycle services and performance guarantees.
Practically speaking, organizations should evaluate steam trap programs on a total cost of ownership (TCO) basis rather than first‑cost alone. The incremental spend on IoT‑enabled or wireless‑monitoring traps can pay back quickly through reduced condensate losses, fewer unplanned shutdowns and lower emissions penalties under tightening regulatory regimes.
Competitive landscape — who matters and why
The Steam Trap Valve ecosystem is fragmented, with the top three and top five participants accounting for a relatively small share of global revenue, indicating an active and competitive supplier field. That fragmentation presents choices — and risks — for buyers. Established engineering‑led incumbents continue to dominate high‑spec industrial applications, while regional manufacturers capture retrofit and local service volumes.
-
TLV Co., Ltd. (Tokyo, Japan) — notable for mechanical, thermodynamic and thermostatic architectures and for product moves toward larger capacity float traps suited to heavy condensate loads. Recent launches underscore a push into higher‑throughput segments.
-
Spirax Sarco Engineering plc (Blythewood, SC, USA) — combines classic trap technologies (inverted bucket, balanced pressure, thermostatic) with wireless monitoring ecosystems, extending their value proposition into continuous asset health programs.
-
Armstrong International Inc. (Three Rivers, MI, USA) — a leader in trap monitoring and analytics; the evolution of their SteamEye platform reflects the industry’s move toward 24/7 remote failure detection.
-
VELAN Inc. (Montreal, Canada) and Gestra AG (Bremen, Germany) — play to high‑reliability and process‑industry demands, providing alloy‑rated designs and condensate management for power and downstream sectors.
-
Regional specialists (e.g., Pennant Corp , Yoshitake Inc. , Kosen Valve , Dhanwant Metal Corporation ) continue to secure retrofit and service work by offering competitive local supply and rapid aftermarket response.
Recent vendor activity reinforces two themes for 2026 decisions: (1) product innovation continues — exemplified by large‑capacity float traps and upgraded monitoring solutions — and (2) monitoring/platform capabilities are now a differentiator rather than a fringe add‑on. Notable recent launches include a large capacity float trap from TLV (July 2025), enhanced real‑time monitoring from Armstrong (March 2025), expanded trap portfolios from smaller OEMs (early 2025), and explosion‑protected wireless monitoring devices from Yokogawa (October 2024). Each development raises the bar for expected functionality in tender specifications.
Technology, IoT and the new service economy
Industry 4.0 adoption is more than a buzzword in the steam trap market: predictive maintenance and wireless monitoring reduce the estimated energy losses from faulty traps by a material margin. For operators, integrating trap monitoring into existing plant‑level DCS/asset management systems creates a measurable ROI via fewer unplanned outages and lower steam wastage. For vendors, it creates subscription revenue opportunities in condition‑based service agreements.
Procurement teams should therefore evaluate suppliers on three axes: hardware durability and materials suitability (considering high‑temperature/high‑pressure alloys), sensor and communications robustness (including explosion‑protection where required), and analytics/service models (SaaS or managed services vs. one‑time hardware supply).
Regulatory and raw‑material headwinds
Two regulatory facts must be baked into 2026 plans: compliance with pressure vessel and boiler codes (ASME family) remains mandatory in many jurisdictions, and new standards — such as recent updates influencing acceptance testing in major US states — make documented performance evidence a bid qualifier for large projects. Simultaneously, raw material inflation experienced in 2024–2025 — particularly stainless steel and copper — has changed cost baselines, driving design rethink and alternative sourcing strategies.
These dynamics elevate the importance of early supplier engagement, contract clauses for material cost pass‑throughs, and design optimization initiatives that can reduce exotic material exposure without compromising safety or longevity.
What the PW Consulting report provides (practical, not theoretical)
-
Market sizing and modeled demand across the 2020–2032 horizon (base year 2025), with scenario runs for slower and faster adoption of IoT monitoring technologies.
-
Purchasing playbook for 2026: RFP templates, warranty and service‑level language, specification checklists for explosion‑protected and wireless units, and negotiation levers tied to raw‑material indices.
-
Vendor scorecards and supplier risk maps that synthesize product capability, monitoring ecosystem maturity and aftermarket coverage — helping buyers reduce the risk of single‑source exposure.
-
Capex vs. Opex modeling for digital retrofit programs, including payback curves for condition monitoring and sample TCO analyses under multiple fuel‑price regimes.
-
M&A and partnership opportunity scan: identification of targets and archetypal integration approaches for strategic buyers seeking to consolidate fragmented service markets.
-
Regulatory compliance matrix and implementation roadmap for meeting boiler and plant acceptance testing requirements across major industrial jurisdictions.
Note: the report contains granular regional and application segment splits, price and volume sensitivity matrices, and vendor share estimates. This preview intentionally omits those detailed tables to protect strategic granularity — the full intelligence set is accessible via the source for authorized subscribers.
Actionable strategic imperatives for 2026
-
Reframe steam trap procurement from CAPEX line‑item to a cross‑functional program that links energy, operations, and compliance. Mandate TCO and failure‑risk scoring in all tenders.
-
Prioritize trials of wireless monitoring platforms with a focus on integration ease and explosion‑protection when relevant. Set clear KPIs (reduction in steam loss %, failed‑trap detection time, etc.) tied to commercial incentive clauses.
-
Lock in alloy and critical‑component contracts or prequalify alternate suppliers to insulate projects from raw‑material volatility observed in 2024–2025.
-
Assess M&A or partnership options in fragmented aftermarket geographies to secure faster service response and lifetime recurring revenue streams.
-
Update compliance and commissioning protocols to reflect tightened regional standards; require vendor evidence of acceptance testing and traceability as part of final payment milestones.
How to use this insight
Executives and functional leads should treat the highlights above as the strategic outline for 2026. For procurement teams, the immediate next step is to incorporate monitoring and lifecycle clauses into upcoming RFPs. For operations and reliability engineers, pilot one digital monitoring program in a high‑loss steam area and measure results over 90–180 days. For corporate strategy groups, use vendor fragmentation and low market concentration as a signal to evaluate consolidation opportunities or strategic supplier alliances.
PW Consulting’s full Steam Trap Valve Market study contains the detailed segment economics, regional demand models and vendor share tables that will allow you to prioritize investments by ROI, regulatory risk exposure and supply‑chain resilience. This briefing intentionally demonstrates the analytical depth while withholding the segment‑level datasets that are central to tactical contracting decisions — access to the complete dataset and modeling workbook is available through our subscription portal.
Conclusion
Steam trap valves sit at the intersection of energy efficiency, process reliability and regulatory compliance. The market’s measurable growth from 2020 to the 2025 base year and the forecasted expansion through 2032 at a 4.4% CAGR create an environment where targeted investments in monitoring, materials strategy and strategic vendor selection can deliver outsized operational returns. For 2026 planning cycles, the question is not whether to spend on steam‑system improvements, but how to structure investments and contracts so that they drive verifiable energy and risk reductions. PW Consulting’s full report provides the granular market maps and tactical instruments to execute on that strategy.
For detailed analysis of this topic, please visit the official page: Steam Trap Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com