

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Caviar Market Set to Grow at a 7.0% CAGR Through 2032

Caviar Market 2026 Strategic Preview — PW Consulting
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused preview of our Caviar Market research designed to shape executive decisions in 2026. This analysis synthesizes macro trends, competitive moves, and regulatory signals that will determine value capture across the value chain. The piece deliberately demonstrates our methodological depth while preserving the granular segment-level tables and models for subscribers — the intent is to equip leaders with directionally precise, executable insights and to guide them to the full dataset for operational planning.
Caviar Market
Executive snapshot
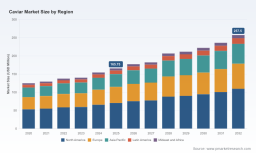
Our base-year calibration is 2025, using a 2020–2025 historical window and a 2026–2032 forecasting horizon. The global caviar market, measured in USD (Million), has shown steady expansion through the first half of the decade and is forecast to grow at a compound annual growth rate (CAGR) of 7.0% over the 2026–2032 period. On a headline basis, the market reached approximately USD 165.8 Million in 2025 and is projected to approach USD 257.5 Million by 2032 under our central scenario. The trajectory reflects a blend of premiumization in developed markets, supply-side institutionalization via aquaculture, and evolving trade and certification dynamics.
Caviar Market
Why 2026 is a strategic inflection
- Consolidation meets premium demand: Market concentration metrics indicate that the top three players control a material share of the market (CR3 ~60%), and the top five firms capture an even larger portion (CR5 ~80%). That structure creates simultaneous opportunities to scale branded value and to pursue bolt-on consolidations that improve supply security and margin capture.
- Transition to farmed supply: Farmed sturgeon now supplies the majority of global production, and a single producing nation contributes more than half of global volume — a structural shift that reduces dependence on wild harvests but adds geopolitical and concentration risk into the supply equation.
- Certification and traceability as price multipliers: Third-party certifications and visible sustainability credentials are becoming commercial prerequisites, especially among premium foodservice and retail channels. Certification can materially change procurement behavior and market access.
Market drivers and dynamics
Demand-side forces are straightforward: premiumization of food consumption, experiential dining, and targeted retail innovations (ready-to-serve formats and hybrid flavor variants) sustain higher per-unit willingness to pay. On the supply side, technology-enabled farming — recirculating aquaculture systems (RAS), selective breeding, and improved hatchery protocols — are compressing production cycles and improving yield predictability. Short-term price signals remain volatile: traditional sturgeon caviar export prices experienced downward pressure in recent years even as value-driven niches command premiums.
Caviar Market
Regulation and trade policy are active contributors to near-term risk and opportunity. For example, travel and customs regimes limit per-person carry-in volumes into key markets, affecting small-batch retail strategies and gifting segments. Export volumes from some origins have experienced marked year-on-year swings, reflecting both policy shifts and changing fleet/processing capacities. For executive teams, incorporating regulatory scenario testing into procurement and market-entry models will no longer be optional.
Competitive landscape — who matters and why
The competitive map blends legacy regional producers and emergent industrial-scale farm operators. Key firms evaluated in our report include global-tier producers, vertically integrated farm-to-distributor players, and regionally important exporters. A select set of strategic observations:
- Large-scale vertically integrated producers: Some firms operate at scale with premium positioning and global distribution reach. Their growth strategies emphasize channel expansion, expanded SKU breadth, and public equity events to fund capacity and brand-building. Recent public-market activity demonstrates investor appetite for scaled, traceable supply chains.
- Premium boutique and certified producers: A subset of farms is differentiating through sustainability credentials and certification. These players are winning access to high-margin foodservice contracts and premium retail assortments by validating supply chain transparency.
- Local champions in developed markets: Domestic RAS producers in high-value markets are strategically important; they sell freshness and locality, two attributes that justify pricing multiples to internationally sourced product.
- Traditional regional exporters: Established exporters from historical fishing regions continue to defend commodity segments while adjusting to certification and traceability pressures.
Representative names highlighted in the full study (profiles and strategic positioning mapped for competitive benchmarking) include leading large producers, certified boutique farms, and the primary US RAS operators. Recent corporate developments we monitor closely — and that feature in our competitive dynamic analysis — include high-profile IPO filings from major producers, new retail flavor introductions targeting mass channels, and the awarding of industry-first certifications that effectively reset procurement criteria for institutional buyers.
Selected recent developments (strategic implications)
- Repeated IPO filings by a major vertically integrated producer signal both maturation and capital intensity in scaling branded global supply; the company’s near-term capital plan focuses on distribution expansion and product innovation.
- Retail product innovation — for example, novel flavor extensions introduced into North American retail corridors — demonstrates the category’s potential for mainstream consumerization when paired with appropriate merchandising and price architecture.
- Certification milestones achieved by certain producers create first-mover advantages for institutional buyers who prioritize supply-chain risk mitigation, placing pressure on competitors to adopt equivalent standards or risk losing premium contracts.
- Geopolitical and trade shifts in some exporting countries have produced double-digit volatility in export tonnages and values, underscoring the need for diversified sourcing strategies and inventory contingency planning for buyers reliant on uninterrupted supply.
Strategic implications for 2026 decision-makers
- Producers: Prioritize certification and traceability investments to secure institutional contracts. For mid-sized producers, consider alliance models with logistics partners to extend shelf-life and market reach rather than capex-heavy capacity expansion alone.
- Retailers & Foodservice: Treat caviar as a dual-category product — both a luxury indulgence and an experiential accessory. Create tiered merchandising strategies tied to provenance and certification to capture both impulse and planned purchase behaviors.
- Private equity & M&A teams: Target acquisitions that deliver supply certainty (owned hatcheries or RAS facilities), route-to-market assets, or differentiated brand equity. Given the concentration metrics, a few well-placed transactions can produce outsized strategic synergy.
- Risk managers: Build flexible sourcing playbooks that incorporate alternative origins, buffer inventory policies for peak seasons, and contract clauses that address certification lapses or sudden export interruptions.
What PW Consulting’s full caviar market report delivers
Our comprehensive deliverable is built to move organizations from strategic questions to board-ready actions. Highlights include:
- Market sizing and forecast model (2020–2032) with scenario layers and sensitivity testing (base, upside, downside) calibrated to changes in production, certification adoption, and trade policy.
- Competitive benchmark matrix covering strategic posture, vertical integration, certifications, channel coverage, and recent corporate moves for the leading producers.
- Supply-chain & margin map identifying cost pools by stage (hatchery, grow-out, processing, cold chain, distribution) and near-term levers to improve gross margin.
- Commercial playbooks for producers, retailers, and institutional buyers: pricing strategies, SKU architectures, certification roadmaps, and marketing positioning frameworks tuned to premium and accessible segments.
- M&A diligence toolkit including an acquisition valuation model, ESG/certification red flags, and integration checklists to accelerate post-merger value capture.
- Regulatory and trade impact scenarios including customs limits, export policy shifts, and certification adoption curves — each mapped to revenue and margin outcomes for 2026–2030 planning.
- Primary research insights drawn from interviews with producers, distributors, importers, and category buyers across major markets, presented as direct implications for contract design and go-to-market prioritization.
Note: This preview intentionally omits the granular regional and application-level splits and price-by-SKU matrices included in the full report. Our subscriber materials provide the complete segmented tables and downloadable models required to operationalize the strategies summarized here.
Decision playbook — how to use this analysis in 2026
- Short-term (0–12 months): Lock in supply via contracts contingent on certification milestones; pilot certified SKUs with select retail partners; evaluate hedged inventory positions for key selling seasons.
- Medium-term (12–36 months): Pursue strategic partnerships or acquisitions that provide RAS capacity or certified processing; invest in brand stories tied to provenance and sustainability; transition margin models to reflect premiumization opportunities.
- Long-term (36+ months): Shape industry standards by participating in certification consortia; co-invest in technology R&D that reduces grow-out cycles; build resilient multi-origin sourcing strategies.
Closing — why access the full report
The macro numbers are clear: a robust growth path (7.0% CAGR across our forecast horizon) and a market that more than halves its value gap between 2025 and 2032 in our base projection. Yet, the competitive advantage in 2026 will hinge on access to detailed, actionable intelligence: verified regional demand curves, SKU-level price elasticity, cost-to-serve across cold chains, and certification adoption timelines. PW Consulting’s full report contains those proprietary data tables, the interoperable financial model, and the acquisition diligence templates necessary to convert strategy into measurable outcomes.
For boards, commercial leaders, and investors planning moves in 2026, the preview above should clarify the strategic inflection points — certification, supply diversification, and channel innovation — while the subscriber materials provide the operational granularity needed to execute. Visit our report page to review the full dataset, download the valuation model, and schedule a client briefing.
For detailed analysis of this topic, please visit the official page: Caviar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com