

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Electric Oil Pump Market to Reach USD 3,813.63M by 2032 at 8.82% CAGR

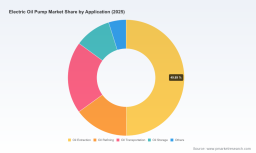
Electric Oil Pump Market 2026: A Strategic Preview for Executive Decision-Making
As PW Consulting’s lead industry analyst, I present a concise, high-impact preview of our full Electric Oil Pump Market study — calibrated to guide boardrooms, product leaders, and procurement chiefs through the critical choices facing 2026. Anchored on a 2025 base year and a rigorous forecast horizon to 2032, our analysis shows the market expanding at a compound annual growth rate (CAGR) of 8.82% through the forecast window. The market has grown from roughly USD 1.48 billion (Million) in 2020 to about USD 2.24 billion (Million) in 2025, and our scenario-aligned baseline projects a rise toward the upper end of the multi-billion range by 2032. This preview surfaces the strategic implications — while withholding granular segment and regional tables reserved for the full report — so you can act with confidence in 2026.
Electric Oil Pump Market
Why this study matters now
-
Acceleration of electrified powertrains and stricter emission mandates are changing the value proposition for electric oil pumps — they are no longer niche components but system-level enablers for efficiency, thermals and electrified driveline reliability.
Electric Oil Pump Market -
Supply-chain shocks and material volatility in 2025–26 mean procurement and product teams must reframe sourcing and design choices as strategic levers, not just cost levers.
Electric Oil Pump Market -
OEMs and Tier-1s are making program-level commitments now; contract award timing and qualification windows in 2026 will govern supplier capture and scale economics through the early 2030s.
Market dynamics shaping 2026 strategy
-
Regulatory push and fleet electrification: New regulatory regimes are accelerating zero-emission adoption timelines and tightening thermal and driveline efficiency expectations. Compliance imperatives are driving wider adoption of electric oil pumps across hybrid and battery-electric platforms as OEMs seek to meet both emissions and fuel-efficiency targets. For leaders, this means earlier integration of pump functions into vehicle thermal strategies and clear alignment between powertrain and thermal-management roadmaps.
-
Materials and cost pressure: In 2025–26, copper price volatility and demand for rare-earth elements used in brushless motors materially raise bill-of-materials risk for pump makers. These swings amplify the importance of material hedging, design-for-material-substitution, and strategic supplier partnerships to stabilize cost-to-serve.
-
Electronics and qualification constraints: Extended semiconductor lead times — with control-module lead times stretching to multiple months — are creating production and costing bottlenecks for transmission and motor-control integrated pumps. Concurrently, API and ISO qualification requirements for submersible and high-durability applications are elevating test and validation spend; programs that front-load qualification reduce time-to-revenue and warranty exposure.
-
Field reliability and recalls: Recent field events have highlighted controller- and sealing-related risks in electric pump subsystems. These incidents underscore two imperatives: tighter supplier quality governance for electro-mechanical interfaces, and investments in condition monitoring and field-data analytics to detect early signs of thermal stress or controller drift.
Competitive landscape — what senior leaders should internalize
The market exhibits moderate concentration: the top three suppliers control a material share of the market, while the top five broaden that footprint further. This structure creates a dual opportunity for challengers — to displace incumbents through technology differentiation and to collaborate with OEMs on integrated-system bids. Below are the strategic positions of leading players that appear across program wins, product roadmaps and systems integration initiatives.
-
BorgWarner Inc. (Auburn Hills, Michigan) — Moving beyond discrete pumps, BorgWarner is positioning integrated motor-and-pump platforms for electrified drivetrains and NEV segments. Recent contract awards in Asia (2025–2026) reflect success in program-level bids where propulsion and thermal management are combined; expect further expansion into regional sourcing footprints aligned with Chinese OEM partnerships.
-
Denso Corporation (Nagoya, Japan) — Denso’s strength is in advanced variable-displacement electric pumps and thermal-management systems optimized for EV and hybrid powertrains. Their engineering cadence favors tightly integrated, vehicle-level thermal controls that resonate with OEMs seeking packaging and efficiency gains.
-
Continental AG (Hanover, Germany) — A premium and commercial-vehicle playbook centers on high-margin thermal-management solutions and variable-displacement pumps. Continental’s systems approach targets OEMs that prioritize durability and integration into vehicle electronic architectures.
-
Hitachi Astemo Ltd. (Tokyo, Japan) — Focused on electrification, Hitachi Astemo is showcasing advanced pump-motor assemblies and is active on exhibition platforms to accelerate adoption. Participation at major shows underscores their go-to-market emphasis on technology visibility and OEM qualification cycles.
-
Nidec Corporation (Kyoto, Japan) — Leveraging motor expertise, Nidec emphasizes pump solutions for e-axle cooling and CVT applications in electrified vehicles. Their motors-first approach supports customers targeting compact packaging and high-efficiency cooling.
-
Magna International Inc. (Aurora, Ontario) — Magna is developing integrated pump-motor assemblies for electric truck thermal systems, reflecting the confluence of commercial vehicle electrification and higher duty-cycle cooling requirements.
Recent program signals you cannot ignore
-
Contract wins and program awards in Asia during 2025–2026 are reshuffling supplier footprints and creating new volume corridors; early winners will lock in design-in advantages for mid-decade production ramps.
-
Industry exhibitions and OEM showcases are serving as de facto procurement accelerators for electrification modules — attendance is now part of the visibility playbook for Tier-1s and component innovators.
-
Supplier consolidation dynamics — while not a fully concentrated market — are placing a premium on scale and cross-program capability to meet OEM expectations for global content and validation rigor.
What the full PW Consulting report delivers (practical, executable content)
-
Proprietary forecast model (2026–2032) with base-scenario, conservative and aggressive adoption tracks, and sensitivity levers for materials, regulatory shifts, and semiconductor availability.
-
Risk-adjusted supplier scorecards and a tactical supplier-selection matrix aligned to program timetables and qualification requirements.
-
Cost-to-serve and TCO frameworks for electric pump architectures across vehicle segments, including break-even and payback analyses for electrified systems.
-
Regulatory compliance playbook mapping Euro 7–era requirements, U.S. ZEV pathways and API/ISO qualification steps to development milestones and testing budgets.
-
M&A and partnership heatmaps identifying fast-track consolidation targets, technology buys, and JV structures by capability and geography.
-
Implementation roadmaps for procurement, R&D and aftersales functions — including recommended contract clauses for commodity-price pass-through, long-lead electronic components and field-data sharing arrangements.
Priority moves for executive teams in 2026
-
Lock down long-lead components: Negotiate multi-year procurement windows for copper and rare-earths where feasible, and secure semiconductor capacity through strategic supply agreements or allocation partnerships.
-
Modularize and standardize: Move toward modular pump-motor assemblies that reduce variant complexity and shorten OEM qualification cycles; standardized interfaces speed OEM integration and reduce program risk.
-
Localize critical nodes pragmatically: Align production and engineering footprints with OEM program locations to reduce logistics risk and to win system-level contracts that favor local content.
-
Elevate qualification and field-monitoring: Invest in accelerated qualification rigs and fleet telematics for early detection of controller and sealing issues; integrate warranty analytics into product development loops.
-
Consider collaborative R&D: Pursue co-development or equity partnerships with motor specialists or thermal-management integrators to access differentiated designs while sharing qualification burdens.
How PW Consulting helps you act in 2026
Our full Electric Oil Pump Market study is designed as an executable decision pack — not an academic exercise. It provides prioritized playbooks, procurement templates, supplier negotiation scripts, and a step-by-step market-entry blueprint tailored to the 2026 program cadence. The document isolates the critical timing gates where investment, contract negotiation, or technology bets deliver disproportionate value.
This preview intentionally omits detailed segment-by-region tables and proprietary split data — those analytics and the supporting datasets are included exclusively in the complete report and interactive dashboards hosted on our platform. If your 2026 strategy depends on reliably navigating supplier risk, product qualification, and program capture in the electric oil pump space, the full PW Consulting deliverable is the operational intelligence you need to convert market growth into competitive advantage.
For detailed analysis of this topic, please visit the official page: Electric Oil Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com