

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Busway-Bus Duct Market to Grow at 5.5% CAGR (2026–2032)

Busway–Bus Duct Market 2026: Strategic Preview for Executive Decision‑Makers
As PW Consulting’s lead industry analyst, I present a strategic preview of our forthcoming Busway–Bus Duct Market study — framed expressly for executives who must make consequential capital, product and M&A decisions in 2026. This preview highlights the granular trends, structural forces and competitive dynamics that will determine winners and laggards over the coming investment cycle, while deliberately withholding core breakdowns to ensure your team accesses the full data set on our portal.
Busway-Bus Duct Market
Why this study matters for 2026 decisions
The busway and bus duct segment has transitioned from a niche electrical-distribution component to a strategic system-level investment for industrial, commercial and hyperscale power environments. The market expanded markedly over the 2020–2025 historical window — rising from just under USD 9.1 billion in 2020 to about USD 11.7 billion in the base year 2025 — and is forecast to grow at a compound annual growth rate (CAGR) of approximately 5.5% through 2032. By the end of our forecast horizon the market approaches the mid‑teens of billions (USD), reflecting steady demand from capacity upgrades, data-center proliferation and industrial electrification.
Busway-Bus Duct Market
For executives evaluating capital allocation in 2026, that combination of steady growth and concentrated supplier power presents two distinct strategic choices: invest behind differentiated platform plays (product + service + compliance) or prioritize supply‑chain and pricing resilience. Our study quantifies the trade-offs and presents executable options for both paths.
Busway-Bus Duct Market
What the full report delivers — practical, transaction‑ready content
- Market architecture and sizing: Clear, reproducible methodology for our historical and forecast series (2020–2025 history; 2026–2032 forecast), with transparent assumptions for unit demand, ASPs and inflation adjustments in USD (revenue unit: Million).
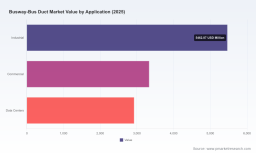
- Segment frameworks (kept high‑level here): Type, application and regional segmentation with demand‑drivers and margin implications. The preview outlines drivers without the detailed segment shares — the full report provides the precise splits.
- Regulatory and standards map: Treatment of recent standard updates and how they affect product certification, warranty and liability exposure across major markets.
- Supply‑chain & cost modeling: Sensitivity analysis to copper and aluminum input shocks, freight rate scenarios and localization thresholds that inform make vs. buy calculus.
- Competitor scorecards & strategy playbooks: Actionable benchmarking across product breadth, systems integration, channel reach, and service models — including M&A appetites and capability gaps for primary vendors.
- Go‑to‑market playbooks: Prescriptive routes for targeting data centers, heavy industry retrofits and new commercial construction with recommended product mixes, pricing ladders and service contracts.
- Investment and M&A pipeline analysis: Target profiles, valuation multipliers and integration risk matrices for bolt‑on acquisitions versus greenfield capacity expansions.
- Operational tools: CapEx priority matrix, product road‑map templates, and bidding calculators that your teams can adapt immediately.
Structural dynamics shaping demand in 2026
Three structural forces drive the medium‑term outlook. First, the ongoing densification of power distribution in data centers and electrified industrial facilities continues to favor modular, serviceable busway systems. Second, global standards and certification updates — notably recent editions of UL 857 and established ANSI temperature‑rise and short‑circuit standards — are raising technical bar for manufacturers and installers, placing a premium on validated testing and warranty certainty. Third, input‑cost volatility — especially copper — remains a persistent profit‑and‑price risk: LME copper averaged roughly USD 9,200 per metric ton in early 2026, and copper busbars continue to dominate material selection because of their electrical performance (accounting for a substantial majority share of the busbar market in 2025).
Together, these dynamics favor suppliers that combine engineering depth, manufacturing scale, and regulatory know‑how. They also increase value for integrated offerings that bundle hardware with commissioning, thermal monitoring and lifecycle service agreements.
Competitive landscape — how leading suppliers are positioning
The market is moderately consolidated. The three largest suppliers capture an appreciable share, and the top five approach a majority position — a structure that enables scale advantages but still leaves room for nimble challengers that can exploit niche specialization or regional supply advantages.
- Schneider Electric (France): Leveraging systems integration capability, Schneider emphasizes turnkey power-distribution platforms and digital monitoring tie‑ins. Expect focus on total-cost-of‑ownership messaging for large commercial and industrial clients.
- Siemens (Germany): Siemens competes on engineered solutions for heavy industry and data centers, differentiating on high‑voltage performance and project engineering services.
- ABB (Switzerland): ABB’s strength is its breadth across electrification and propulsion ecosystems, positioning busway offerings as part of larger electrification projects with integrated protection and switchgear.
- Eaton (Ireland): Eaton emphasizes compliance and reliability — aligning product development with ANSI and UL specifications, and selling through electrical contracting and OEM channels.
- LS Cable and System (South Korea): An aggressive product and footprint player: recent moves include a product catalog that offers DC‑way and tap‑off solutions compliant with US standards and a factory expansion in Mexico to serve North American demand more competitively.
- Legrand (France): Legrand pursues modular, plug‑and‑play busway solutions targeted at commercial and light‑industrial segments, leveraging channel and specification influence.
- Powell Industries (US): Focused on engineered, heavy‑duty bus duct systems for utilities and process industries; strong in project delivery and retrofit scopes.
- EAE Electric (Turkey) and Furukawa Electric (Japan): Regional leaders with engineering edge in asset-intensive industries and local content advantages in their home markets.
- nVent (US), Starline (France) and Starline‑branded systems: nVent and Starline drive differentiated offers around thermal management, enclosure systems and busway accessories with a focus on operational reliability.
- Godrej and Boyce (India): Cost‑competitive plays with growing export orientation and opportunities to capture retrofit volume in emerging markets.
Each of these vendors is navigating the same three imperatives: comply with tightening standards, manage raw‑material input risk, and deliver measurable service economics to large end users.
Recent developments to watch in 2026
- Product diversification toward DC‑capable busways and specialized tap‑off boxes as vendors respond to data‑center and electrified‑transport microgrid requirements.
- Manufacturing footprint adjustments — exemplified by new factory investments in North America — to shorten supply chains and mitigate freight and tariff exposure.
- Regulatory tightening: updated editions of UL 857 (service-entrance, feeder and branch‑circuit busways at ≤600 V) and reinforced ANSI compliance requirements are increasing certification timelines and cost to market.
- Raw material pressures: copper’s price level and the material’s dominant role in busbar selection continue to be central to commercial negotiations and hedging strategies.
What this means for corporate strategy in 2026
For investors and corporate decision‑makers, the principal strategic imperatives are straightforward but execution‑intensive:
- De‑risk supply and lock in input cost stability: Negotiate long‑term supplier agreements, pursue localized production where economically justified, and expand hedging strategies for copper exposure.
- Invest in standard‑compliance engineering: Certification delays and warranty exposures create competitive advantage for firms that can consistently meet UL/ANSI test regimes with low time‑to‑market.
- Differentiate through services: Offer commissioning, thermal monitoring and lifecycle maintenance contracts that convert product sales into recurring revenue and improve lifetime margin capture.
- Pursue bolt‑on M&A selectively: Look for targets that provide regional channel access, complementary manufacturing capacity or niche technologies (e.g., DC‑capable modules) rather than broad platform rollups.
- Targeted commercialization for data centers: Productize plug‑and‑play solutions with fast installation and high density to capture a disproportionate share of the higher‑margin data‑center segment.
How PW Consulting can help
Our full Busway–Bus Duct Market report combines the quantitative backbone (market sizes, CAGR, concentration metrics and forecast by type/application/region) with practical decision tools: pricing models, bid calculators, supplier scorecards and a regulatory compliance checklist aligned to UL 857 and ANSI test regimes. For corporate leadership teams and private equity sponsors aiming to use 2026 as an inflection point for investment, the report provides both the map and the operational playbooks required to execute.
This preview is designed to demonstrate the analytical depth and actionable focus of our work while preserving the core segmentation and data that drive deal and portfolio decisions. Access the full report on our site to obtain the granular segment splits, company scorecards, downloadable financial models and executive briefings your team will need to proceed with confidence.
Executive takeaway
The Busway–Bus Duct market offers predictable, mid‑single‑digit growth underpinned by infrastructure modernization, data‑center capacity growth and regulatory tightening. The winners in 2026 will be those who pair engineering and compliance leadership with strategic supply‑chain moves and service‑led commercial models. Our full study equips you to choose between scaling organically, executing targeted acquisitions, or optimizing margins through product‑service bundles — with the specific metrics and model scenarios required to commit capital.
For access to the full dataset, segment level detail, and proprietary playbooks, visit our report page. PW Consulting’s analysts stand ready to convene a tailored workshop to translate these insights into a 90‑day action plan for your organization.
For detailed analysis of this topic, please visit the official page: Busway-Bus Duct Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com