

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Bovine Colostrum Market to Hit USD 310.3M by 2032 at 6.85% CAGR

Bovine Colostrum Market — Strategic Outlook for 2026: A PW Consulting Preview
Executive snapshot
As businesses plan 2026 priorities in nutrition, supplements, and animal-feed adjacencies, bovine colostrum is transitioning from a niche ingredient to a strategically important, mid‑market category. PW Consulting’s base-year analysis (2025) shows a market that has grown from approximately USD 152.3 Million in 2020 to USD 194.2 Million in 2025 and is forecast to continue expanding, reaching roughly USD 310.3 Million by 2032 — a compound annual growth rate of 6.85% across the forecast horizon. Market concentration is meaningful: the top three suppliers account for the majority share of industry revenue, and the top five consolidate nearly four‑fifths of the market, signaling both barriers to entry and the potential for acquisition-driven scale.
Bovine Colostrum Market
Why this matters for 2026 decision-makers
- Timing: The category is moving from fragmentation into a more consolidated competitive set — presenting windows for selective M&A and JV activity to capture scale benefits before prices and raw-material access tighten further.
- Margins and pricing: Raw-material volatility, trade friction and seasonal supply cycles are already feeding through to input cost swings. Firms that secure predictable sourcing and build specification-driven differentiation will protect margins more effectively.
- Channel leverage: Demand continues to broaden across human health, sports performance and animal nutrition channels. Companies that align product formats, clinical evidence and channel economics now will enter 2026 with defensible go-to-market engines.
Market dynamics: Drivers, constraints and sources of volatility
The market’s recent trajectory reflects a mix of demand expansion and supply-side shocks. After steady growth between 2020 and 2022, the industry experienced a short-term contraction driven by raw-material constraints and trade adjustments; the market then resumed growth into 2024–2025. Looking forward, growth to 2032 is underpinned by growing consumer interest in immune‑support and gut‑health products, rising use in sports nutrition formulations, and steady uptake in animal nutrition for calf health and performance.
Bovine Colostrum Market
At the same time, producers and buyers face four interlocking sources of noise and risk:
Bovine Colostrum Market
- Trade and tariff volatility: Recent tariff adjustments have increased import uncertainties and pushed some buyers to reassess sourcing geographies and landed-cost models.
- Seasonality and biological supply limits: Colostrum supply is inherently tied to calving seasons; trade tensions and logistical delays amplify the effect of these natural cycles on availability.
- Commodity price swings: Dairy‑commodity volatility — particularly in exporter markets — has produced raw‑material cost swings in the mid‑teens percentage range in recent years, translating into occasional price pressure at the ingredient level.
- Regulatory and quality unpredictability: Bovine colostrum remains largely unregulated in certain jurisdictions, which creates potency variability across batches and suppliers unless buyers specify stringent quality and testing regimes.
Segmentation and application trends (high-level)
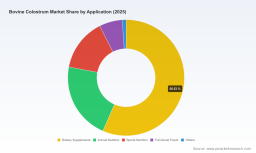
The market supports multiple product formats and end-use applications — from bulk powder for formulators to finished capsule formats for direct-to-consumer health brands, and specialized veterinary-grade material for animal nutrition. While we do not disclose granular segment shares in this preview, two practical implications are clear:
- Format matters: Powder remains the logistical and cost-efficient form for B2B supply chains, while capsules/tablets and ready‑to‑drink formats are driving retail and DTC penetration.
- Application cross‑pollination: Clinical positioning in human health (immune/gut) is lifting consumer acceptance and enabling brand extensions into sports and functional-food formats, which in turn feeds back into demand for higher‑specification raw material.
Competitive landscape — what to watch
The industry is populated by a mix of vertically integrated multinational suppliers, regional specialists with deep raw‑material control, and high‑volume manufacturers focused on export markets. Key competitive archetypes include:
- Vertically integrated global players with large production footprints and multi‑market distribution, offering scale and a range of bioactives — they set benchmarks for supply reliability and commercial terms.
- Regional leaders with collection systems and certifications focused on quality, traceability and premium positioning — they command price premiums where provenance and certification matter.
- High‑volume specialist manufacturers in cost‑competitive jurisdictions that trade on price and turnkey bulk supply for formulators and white‑label makers.
Representative company profiles (illustrative):
- Glanbia Nutritionals — a vertically integrated producer with substantial U.S. manufacturing capacity, positioned to supply both human-grade and animal‑nutrition markets at scale.
- Saskatoon Colostrum Company Ltd (SCCL) — a recognized global supplier with a strong research orientation and established colostrum‑based product lines for humans and calves.
- Colostrum BioTec GmbH — a European premium player with FSSC 22000 certification and continent‑wide collection capabilities, suited to customers prioritizing EU provenance and compliance.
- Regional producers from India, New Zealand and Poland — offering a mix of high‑throughput supply, grass‑fed provenance claims, rapid processing, and certifications such as GMP/ISO/FSSC or DEKRA.
These profiles imply a differentiated landscape where capability — not only capacity — is the scarce asset. Traceability, IgG potency grades, processing windows (freshness) and certification portfolios are the levers buyers should emphasize in procurement and strategic sourcing.
Strategic implications and recommended actions for 2026
For firms setting 2026 budgets and roadmaps, PW Consulting recommends the following priority actions to convert market trends into competitive advantage:
- Secure diversified sourcing with specification‑led contracts: Negotiate contracts that combine fixed‑volume core commitments with flexible spot windows. Insist on specification clauses covering IgG minimums, testing frequency, chain‑of‑custody and recall protocols.
- Invest in quality differentiation: For brands, clinical validation and transparent potency claims materially enhance conversion and pricing power. For ingredient buyers, prioritize suppliers with robust certification stacks and documented collection-to-processing timelines.
- Hedge input exposure tactically: Use a mix of multi‑sourcing, forward purchasing and price‑adjustment clauses to blunt raw‑material volatility driven by tariffs and commodity swings.
- Pursue targeted M&A or strategic partnerships: Given the concentration metrics, acquisitive scale or exclusive supply partnerships can be decisive, particularly if they bring provenance, certification or rapid‑processing capabilities.
- Design channel-specific SKUs and evidence packages: Align format, dosing and clinical evidence to channel economics (e.g., single-ingredient powders for formulators; clinically-backed capsules for premium retail).
What PW Consulting’s full report delivers — practical tools and deliverables
Our complete market study is built for actionable 2026 planning. Highlights include:
- Comprehensive time‑series demand model (historical 2020–2025, forecast 2026–2032) with scenario capabilities to test tariff shocks, supply disruptions and demand accelerations.
- Supplier benchmarking and risk scoring across production capacity, certifications, processing lead‑times, and traceability protocols.
- Commercial playbooks: negotiation frameworks, sample RFPs, contract templates with quality and pricing clauses, and supplier transition checklists.
- Regulatory and claims matrix by jurisdiction, detailing permissible claims, testing expectations and audit readiness steps.
- Opportunity maps across formats and channels, including go‑to‑market recommendations and product feature sets that optimize margin versus conversion tradeoffs.
- M&A screening list and diligence checklist prioritizing acquisition targets that deliver immediate supply resilience, certification breadth or market access.
Use cases: How leading firms will use this intelligence in 2026
- Ingredient traders and CPG R&D teams will accelerate product launches with validated supplier cohorts and format‑specific claims packages.
- Private equity and strategic buyers will use concentration analytics and scenario models to size consolidation opportunities and post‑deal integration plans.
- Procurement leaders will redesign supplier scorecards and contract terms to lock in quality and mitigate seasonality while preserving flexibility.
- Animal‑nutrition companies will refine calf‑health formulations and adjust sourcing windows to align with regional calving calendars and export constraints.
Final note — the strategic window in 2026
By 2026, bovine colostrum will be an inflection category: sufficiently large to matter materially to ingredient portfolios, yet still dynamic enough that supply discipline, quality differentiation and timely strategic moves can generate outsized returns. PW Consulting’s full report turns macro forecasts and competitive profiling into step‑by‑step playbooks for procurement, product, and M&A teams. For teams preparing budgets and growth plans for 2026, the difference between defensive survival and aggressive market capture will be execution on sourcing resilience, clinical differentiation and channel alignment.
To access the dataset, supplier scorecards and tactical playbooks referenced in this preview, visit PW Consulting’s market page for the full study and client briefing options.
For detailed analysis of this topic, please visit the official page: Bovine Colostrum Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com