

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Electric Heating Elements to hit USD 18.0M by 2032, 4.45% CAGR (2025 base)

Electric Heating Elements Market — Strategic Outlook for 2026: A PW Consulting Preview
As industrial processes and end-market use cases demand ever-finer temperature control, the electric heating elements market is entering a stage of steady expansion and strategic reconfiguration. This preview synthesizes the market trajectory, competitive dynamics, and decision-grade implications derived from PW Consulting’s full Electric Heating Elements (Electric Heater) Market study (base year 2025). It is written to support executive teams making capital allocation, product, and M&A choices in 2026 — while preserving the report’s proprietary granular segmentation and model outputs for subscribers.
Electric Heating Elements (Electric Heater) Market
Market trajectory at a glance
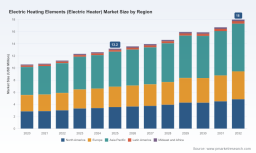
Measured on a total-market basis, the sector has moved from a clear early-decade baseline into a more mature growth phase: our consolidated model places the market at approximately USD 13.2 million in the base year (2025), rising from roughly USD 10.6 million in 2020. Under central assumptions, the market is forecast to expand through our modelling horizon (2026–2032) at a compound annual growth rate of 4.45%, reaching an estimated USD 18.0 million by 2032.
Electric Heating Elements (Electric Heater) Market
Two observations follow for 2026 planning: first, the market’s steady mid-single-digit CAGR masks important pockets of faster adoption and short-term cyclicality tied to end-market capital cycles (semiconductor equipment, plastics extrusion, pharmaceutical manufacturing). Second, our scenario runs capture potential short-term volatility in 2026–2028 while preserving a robust long-term structural tailwind driven by industrial electrification, tighter process control, and demand for certified, high-reliability heating solutions.
Electric Heating Elements (Electric Heater) Market
What the full report delivers — pragmatic, transaction-ready intelligence
- Top-line and bottom-up demand models calibrated to 2020–2025 historical performance and 2026–2032 forecasts, including sensitivity testing under alternate macro and commodity scenarios.
- Practical segmentation and go-to-market playbooks (by product family, application cluster and distribution channel) — note: detailed split tables and unit price matrices are retained for subscribers.
- Supplier and manufacturing maps: process step cost stacks, labor and capital intensity benchmarks (e.g., MgO filling, specialist welding, CNC machining), and recommended automation investments to compress lead times and improve yield.
- Raw material exposure analysis and mitigation strategies (Nichrome/Kanthal alloy sourcing, high-temperature ceramics such as MoSi2 and SiC), with hedging and supplier concentration metrics for procurement teams.
- Regulatory and certification matrix: pathway analysis for UL/CSA/other listings across target markets and the commercial impact of obtaining those approvals.
- Competitive due diligence packages for buy-side and strategic investors: valuation ranges, moat analysis, and prioritized acquisition targets based on capability gaps and geographic reach.
- Service and digitalization playbooks: field-service economics, sensorization, predictive maintenance use-cases, and recurring-revenue models.
- Executive-ready deliverables: one-page investment memos, 100-day integration plans for bolt-on M&A, and board-level scenario decks.
Competitive landscape — who matters and why
The industry remains moderately fragmented: our concentration analysis shows the top three players control roughly a third of market value, while the top five together account for approximately 45%. This structure produces both competitive pressure at scale and attractive consolidation opportunities for players seeking efficiency gains.
Key incumbent profiles that shape near-term competitive dynamics:
- Kanthal (Sweden) — Recognized for a broad portfolio spanning metallic alloys and high-temperature MoSi2 and SiC elements. Their materials and thermally robust product lines make them a reference point for high-temperature industrial applications.
- Tempco Electric Heater Corporation (United States) — A specialist in custom tubular, cartridge, and cartridge-based solutions with in-house MgO filling and precision welding. Recent communications emphasize reliability improvements for high-temperature cartridge applications and process modernization case studies relevant to extrusion customers.
- Wattco (United States) — Broad industrial catalog with product approvals aligned to UL/CSA. Recent thought leadership content indicates strategic focus on semiconductor temperature control and niche process equipment (e.g., freeze-drying loops).
- Indeeco (United States) — Noted for process air heaters and heat-trace systems targeted at hazardous and industrial environments.
- Tutco Heating Solutions Group (United States) — Strengths in electric coils and resistance elements for HVAC and duct applications.
- CRC Progetti S.r.l. (Italy) — European player with armored and cartridge heaters suited for thermal treatment equipment.
- Electricfor (Spain) — Specialist tubular heating elements with a recent expansion of UL certification into industrial refrigeration, effectively broadening addressable segments.
- TAMMAN Electric Heating Elements Co Ltd (Taiwan) — Sheathed and tubular product lines with recent UL listing activity for the Canadian market, signaling an emphasis on certification-driven market access.
Strategic signals from recent developments are clear: certifications and documented use-cases (case studies / technical blogs) are being used as primary market-access tools; content marketing points to an emphasis on high-value, low-volume industrial segments (e.g., semiconductor, pharma); and product differentiation increasingly hinges on serviceability and field performance rather than nominal product specs alone.
Strategic implications for 2026 decisionmakers
For executives and boards preparing 2026 plans, the following priorities convert market intelligence into actionable initiatives:
- Secure material and alloy supply chains. Exposure to Nichrome and Kanthal-class alloys, and to MoSi2/SiC ceramics for high-temperature products, creates procurement risk. Short-term contracts, dual-sourcing, and qualified substitute testing should be prioritized to limit production disruption and margin compression.
- Invest in precision manufacturing and automation. High-mix, low-volume custom manufacturing benefits materially from investments in CNC, automated MgO filling and weld-validation systems — moves that reduce defect rates and accelerate time-to-ship.
- Pursue certifications selectively. UL/CSA approvals materially expand addressable markets, particularly in regulated equipment segments and refrigeration applications. A prioritized certification roadmap tied to revenue-at-risk will maximize certification ROI.
- Productize service and data. Sensorization and predictive maintenance convert one-off sales into higher-margin recurring revenue. Pilot programs should be deployed with top-10 customers in pharma, semiconductor, or other temperature-critical applications.
- Define M&A targets around capability gaps. Given the market concentration profile, disciplined tuck-ins that add channel access (e.g., refrigeration certifications), specialized manufacturing capabilities, or aftermarket service footprints can accelerate scale and margin improvement.
- Embed scenario-planning into the product roadmap. Model impacts of raw-material shocks and cyclical capital expenditure in end markets; design product portfolios that are less material-sensitive or that enable price-pass-through.
Risk and mitigation snapshot
- Raw material price and supply shocks: Mitigate with contractual hedges, strategic inventory, and qualification of alternate alloys and ceramic suppliers.
- Certification and regulatory delays: Start certification processes early and align engineering resources to accelerate test cycles; partner with accredited labs when possible.
- Technological substitution: Monitor alternative heating technologies and invest in protected IP and performance differentiation (e.g., improved response times, longer MTBF).
- Customer concentration and long sales cycles: Expand service portfolios and variable-revenue models to smooth cash flows and reduce reliance on large capital sales.
How PW Consulting’s full study accelerates 2026 execution
Boards and strategic teams will find the full report oriented to execution: it contains prioritized investment cases, a vetted list of acquisition targets with preliminary valuation ranges, manufacturer-level benchmarking worksheets, and buyer-supplier negotiation playbooks. For procurement, the study provides raw material sensitivity matrices and supplier scorecards; for product leaders, it supplies feature–price elasticity estimates and go-to-market sequencing tools; for investor teams, it contains integrated financial models and risk-adjusted return scenarios calibrated for 2026 decisions.
This preview is designed to demonstrate the analytical depth and practical orientation of the full Electric Heating Elements market study. Core segmented models (regional, application, and product-type breakouts), full unit-price curves, and the transaction-ready target list are intentionally reserved for subscribers and clients who access the complete deliverable on our platform.
Actionable next steps
- Commission a targeted procurement stress-test to quantify material exposure over the next 18 months.
- Initiate one pilot for product sensorization with a high-value customer to test a subscription-based service model.
- Develop a two-track certification roadmap (quick-win regional approvals + strategic global certifications) aligned with 2026 commercial priorities.
- Request a tailored M&A screen from PW Consulting to identify 3–5 accretive tuck-in targets that close capability gaps within 12–18 months.
For teams ready to translate this strategic briefing into an executable program, PW Consulting’s full Electric Heating Elements (Electric Heater) Market report offers the models, acquisition maps, and operational playbooks required to make confident decisions in 2026. Access to the complete dataset and transaction toolkits is available through our report portal and advisory services.
For detailed analysis of this topic, please visit the official page: Electric Heating Elements (Electric Heater) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com