

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Asphalt Mixing Plants Market Forecast 2026–2032 at 3.4% CAGR

Asphalt Mixing Plants Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting presents a focused industry briefing that frames the Asphalt Mixing Plants market for strategic action in 2026. Built on a base year of 2025 and a seven‑year forecast window (2026–2032), our analysis synthesizes historical performance (2020–2025), technology trends, regulatory pressure, and vendor dynamics into a single, actionable narrative. The global market has expanded from roughly USD 476.6 million in 2020 to USD 563.3 million in 2025 and is projected to continue growing to an estimated USD 711.8 million by 2032, at a compound annual growth rate (CAGR) of approximately 3.4%. This growth trajectory matters: it changes how capital is allocated, how supply chains are structured, and how product roadmaps are prioritized.
Asphalt Mixing Plants Market
Why this 2026 briefing matters
- Decision velocity: Infrastructure budgets, emissions rules, and raw material volatility are converging in 2026. Executives who align procurement, R&D and aftermarket investments with the near‑term technical and regulatory landscape capture disproportionate margin benefits.
- Risk calibration: Understanding the interaction between permitting timelines, fuel transition readiness, and plant retrofit economics reduces execution risk on both new builds and brownfield upgrades.
- Commercial timing: Growth is steady but not explosive; selective investments in modularity, high‑RAP capability, and emissions controls enable market share expansion without over‑leveraging.
Market dynamics shaping strategy
Three macro forces dominate the 2026 decision agenda: regulatory tightening on emissions, intensifying sustainability requirements (material circularity and low‑carbon fuels), and supply‑side pressures from raw material price swings.
Asphalt Mixing Plants Market
- Regulatory intensity: Hot mix asphalt facilities face federal and state controls that impose tight particulate and opacity limits (for example, under recent EPA NSPS guidance) and require validated fugitive emissions methods. These constraints make emissions control systems and permit readiness a baseline procurement requirement rather than a differentiator.
- Feedstock economics: Binder prices and structural steel costs are elevated and remain volatile, driving a renewed focus on material efficiency, higher recycled asphalt pavement (RAP) integration, and more compact plant designs to reduce capital and operating intensity.
- Operational sustainability: Operators are piloting alternative fuel pathways (including hydrogen‑capable burners and other low‑carbon fuels) and industrial energy recovery to manage operating costs and meet stakeholder expectations on scope 1 emissions.
Technology and product trends — what matters for your product roadmap
- High‑RAP systems: Equipment that tolerates and controls high RAP fractions is no longer niche. Plant designs that combine counterflow drying, intelligent mixing controls, and RAP‑aware process logic reduce binder demand and lower per‑ton costs—vital for long‑term competitiveness.
- Fuel flexibility and decarbonization: Hydrogen‑capable burners and alternative fuel integration are moving from demonstrations to commercial availability. Leading OEMs showcased hydrogen readiness at major 2026 industry events, signaling that fuel flexibility will be a procurement checkbox by 2027 in progressive markets.
- Modularity and mobility: Portable and modular plant architectures allow contractors to reduce logistics, accelerate time to first production, and scale output with project cycles. These configurations are particularly attractive where permitting or site constraints increase time‑to‑first‑mix risk.
- Automation and digital services: Advanced process automation, emissions monitoring and predictive maintenance platforms convert installed plants into ongoing revenue streams. Vendors offering embedded telemetry, remote service and lifecycle analytics command higher aftermarket yields.
Competitive landscape — players to track and what their moves reveal
The market remains moderately fragmented: the top three firms account for a minority share of total revenue and the top five still represent a relatively small consolidated footprint, pointing to opportunity for both consolidation and local champions. Key global players and their strategic emphases include:
Asphalt Mixing Plants Market
- Ammann Group (Langenthal, Switzerland): A broad product portfolio across batch, continuous, mobile and stationary plants. Recent public demonstrations emphasize very high RAP integration and emission control systems, paired with alternative fuel support—positioning Ammann as a leader in sustainable, retrofit‑ready systems.
- ASTEC Industries (Chattanooga, TN, USA): Known for portable, relocatable and stationary systems and continuing innovation on fuel‑flexible burners. ASTEC’s recent product highlights reflect market demand for hydrogen‑capable combustion solutions and integrated support for modified asphalt systems.
- Benninghoven (Wirtgen Group, Germany): Focused on flexible, economical production solutions with proprietary process approaches for energy efficiency and lower emissions—appealing to contractors prioritizing lifecycle cost and environmental performance.
- Marini S.p.A. (Alfonsine, Italy): A strong presence in road construction equipment and continuous mix systems—well positioned where long‑distance supply chains and on‑site production efficiency are strategic priorities.
- Parker Plant Limited (United Kingdom): Emphasizes mobile, modular and static platforms via a portfolio approach that supports rapid deployment and retrofit projects.
Observations from 2026 trade activity underline vendor strategy evolution. Major exhibitions earlier this year saw over 450 exhibitors and a distinct tilt toward sustainability and fuel flexibility. Leading OEMs used these platforms to communicate technical readiness for higher RAP, hydrogen and hybrid fuel solutions—moves that shorten the technology adoption curve for buyers who incorporate these criteria into RFQs.
Report composition — what PW Consulting delivers
Our full study blends quantitative rigor with near‑term tactical guidance. Core components include:
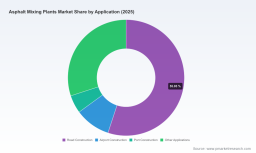
- Granular market models by region, plant type and application with transparent methodology and scenario‑based forecasts spanning 2026–2032 (note: detailed segment figures and region/application splits are included in the full report to support procurement and go‑to‑market planning).
- Vendor scorecards and technology benchmarking across performance, sustainability, modularity and total cost of ownership.
- CapEx/Opex models with sensitivity to binder and steel prices, permitting lead times, and retrofit complexity.
- Regulatory compliance matrixes (federal and state permitting checkpoints, emissions verification methods, and recommended permit‑readiness workflows).
- Case studies and pre‑mortems for new plant projects, upgrades and aftermarket commercialization strategies.
- M&A and partnership playbooks identifying capability gaps and potential bolt‑on targets aligned with low‑carbon and service‑oriented growth strategies.
Strategic actions for 2026 — immediate, tactical and medium horizon
- Immediate (0–12 months): Require emissions and fuel‑flexible specifications in all RFQs; run a short pilot on high‑RAP processing; harden permitting teams with EPA and state permit checklists.
- Tactical (12–24 months): Prioritize modular plant purchases where project cadence is uncertain; negotiate vendor service agreements that include telemetry and predictive maintenance; deploy burner retrofit roadmaps for fuel flexibility.
- Medium horizon (24–48 months): Rebalance capex toward high‑RAP and low‑emissions systems, build local spare‑parts hubs to mitigate steel and supply volatility, and explore strategic partnerships with asphalt binder suppliers to stabilize feedstock costs and quality.
How to use this intelligence in negotiations and capital allocation
- Benchmark vendor proposals against lifecycle models—not just initial capex. Our models quantify the impact of binder savings from RAP, fuel mix changes and emissions compliance costs on unit economics.
- Stress‑test plant economics under multiple regulatory scenarios and raw material price paths; require vendors to honor retrofit pathways for decarbonization upgrades as a contract clause.
- Target aftermarket and service revenue as a profit lever: telemetry, spare parts and performance guarantees materially shift ROI for both OEMs and operators.
Closing perspective
The Asphalt Mixing Plants market in 2026 sits at an inflection point: modest but steady market growth converges with accelerating regulatory and sustainability demands. Organizations that internalize the technical implications—high‑RAP production, fuel flexibility, modular deployment and digital services—can convert regulatory necessity into competitive advantage. PW Consulting’s full study provides the quantified segment views, vendor comparisons and operational models you need to translate these trends into defensible capital and commercial decisions for 2026 and beyond.
For the detailed segment figures, full vendor matrices, and downloadable models that underpin these insights, access the complete PW Consulting report and proprietary datasets on our website.
For detailed analysis of this topic, please visit the official page: Asphalt Mixing Plants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com