

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Aluminum Alloy Wheels Market to Reach USD 344.8 Million by 2032 at 6.98% CAGR

Aluminum Alloy Wheels Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive summary
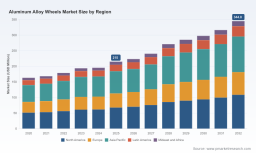
As automotive OEMs accelerate electrification, lightweighting and premiumization agendas, aluminum alloy wheels are transitioning from commoditized metalwork to a strategic component influencing vehicle range, handling and lifecycle footprint. Our market model — calibrated against the 2020–2025 historical run and re‑based to 2025 figures — shows the global aluminum alloy wheels market expanding from roughly USD 163 million in 2020 to approximately USD 215 million in 2025, and continuing toward an anticipated USD 345 million by 2032. That trajectory equates to a compound annual growth rate of 6.98% across the forecast window (2026–2032), underscoring persistent demand momentum and multiple entry points for industrial and financial players in 2026.
Aluminum Alloy Wheels Market
Why this preview matters for decisions in 2026
Strategic choices made in 2026 will determine who captures the most value through the next product cycle. Manufacturers face competing pressures: invest in higher‑margin forged and hybrid technologies, protect margins amid raw‑material and energy cost volatility, and reconfigure global footprints in response to shifting OEM sourcing strategies. For private equity and corporate development teams, the market’s growth profile and structural characteristics imply a diverse set of de‑risked returns — from bolt‑on acquisitions to greenfield capacity built around advanced forming technologies.
Aluminum Alloy Wheels Market
What the macro numbers reveal — and what they hide
High‑level market sizing and growth rates provide a directional compass: steady growth at a near‑7% CAGR signals room for capacity expansion, product premiumization and selective consolidation. However, headline growth masks heterogeneity across product families (cast, forged, advanced flow‑forming and hybrid carbon combinations), application channels (new OEM programs versus aftermarket) and geographies. Our preview intentionally foregrounds these macro signals while withholding granular sub‑segment allocations to preserve the commercial advantage for paying clients — the full report delivers the underlying layered model and segmental breakouts.
Aluminum Alloy Wheels Market
Key structural drivers shaping 2026 strategy
-
Vehicle electrification and range optimization: as EV range becomes a competitive metric, wheel weight contributes directly to system energy efficiency. OEM procurement teams increasingly treat wheel selection as a systems decision rather than a commodity buy.
-
Manufacturing technology bifurcation: conventional casting remains cost‑efficient for volume, while forging and flow forming unlock performance and weight benefits. Advanced composites and carbon hybrid wheels are gaining traction at the premium end following recent technology acquisitions and IP plays.
-
Supply‑chain resilience and localization: OEMs are shortening and regionalizing supply chains, prompting incumbent producers to revisit footprint allocation and flexible manufacturing strategies that support both global platforms and regionally differentiated programs.
-
ESG and lifecycle assessment: OEMs and regulators are pushing lifecycle carbon accounting upstream — from raw‑material sourcing to end‑of‑life recycling — creating new compliance and differentiation requirements for wheel suppliers.
Competitive landscape — who matters and why
The competitive field is a mix of long‑established OEM suppliers, regional specialists and technology‑focused challengers. Leading players bring distinct strategic assets:
-
Superior Industries International — deep OEM relationships and scale in cast aluminum wheels for global platforms, making them a natural partner for large vehicle programs.
-
Maxion Wheels (Iochpe‑Maxion) — global footprint across steel and aluminum, and an active investor in capacity redeployment and product diversification. Recent strategic moves include redeploying assets into South America and initiating serial production of forged aluminum truck wheels in Türkiye (Manisa) in early 2026, signaling intent to capture premium commercial applications.
-
Borbet — long heritage in light alloy manufacturing and an acquisitive push into carbon hybrid technology through the purchase of Dymag assets, positioning them at the frontier of premium composite‑hybrid wheels.
-
Ronal Group and Enkei — European and Asian design and engineering leaders respectively, each combining strong OEM ties with differentiated process know‑how (surface finishes, performance alloys and design IP) that support premiumization and niche aftermarket channels.
-
CITIC Dicastal and Kosei Aluminium — scale suppliers with broad manufacturing footprints and deep capabilities in aluminum wheel and chassis components, important to OEMs seeking integrated sourcing and supply continuity.
Market concentration statistics indicate a fragmented supplier base: the top three and top five players account for a modest proportion of global revenues, leaving scope for localized dominance, technology‑led consolidation and targeted M&A plays. Fragmentation offers both risk (price competition, capacity duplication) and opportunity (consolidation synergies, roll‑up strategies).
Recent industry moves that change the 2026 playbook
-
Iochpe‑Maxion’s South America expansion and stake acquisition in Polimetal (announced late 2025) illustrates how incumbents are redeploying global assets to optimize cost and serve regional OEM programs more competitively.
-
Maxion’s start of serial forged aluminum truck wheel production in Manisa (January 2026) highlights a strategic bet on higher‑value commercial vehicle applications and the importance of local manufacturing proximity to clients.
-
Borbet’s acquisition of Dymag assets (August 2024) accelerates the convergence of metals and composite technologies for premium wheels, creating new product roadmaps and aftermarket differentiation.
What PW Consulting’s full report delivers — practical, transaction‑ready content
The published report is designed to be operational from day one. Key modules include:
- Proprietary market model with historical (2020–2025) calibration and forecast (2026–2032) that powers scenario and sensitivity analysis.
- Technology‑led value map (cast vs forged vs flow‑forming vs hybrid composites) with cost‑to‑benefit matrices and supplier capability heatmaps.
- Supply‑chain and footprint optimization tools: plant economics, utilization sensitivity, and labor/energy input mapping aligned to OEM program cycles.
- Commercial diligence templates for OEM sourcing, aftermarket channel design, and pricing playbooks that codify negotiation levers.
- M&A target screen and integration checklist focused on scale synergies, IP capture, and market access plays.
- Regulatory and ESG compliance playbook, including lifecycle carbon assessment guidelines applicable to supplier contracts and marketing claims.
- 25+ supplier profiles with capability scoring, go‑to‑market posture and recent strategic developments.
To preserve the strategic edge for decision‑makers, the detailed segmental allocations, supplier revenue breakdowns, and the full calibration of our bottom‑up model are included in the full report and dashboard package.
How CEOs, CTOs and investors should apply these insights in 2026
-
OEMs: Treat wheel architecture as an integrated system engineering decision. Allocate program budgets that internalize lifetime energy impacts and select suppliers that can co‑develop designs aligned to modular platforms.
-
Tier suppliers: Prioritize investments where margin and defensibility meet — advanced forming, finishing, and hybrid material integration. Consider localized micro‑factories that blend scale with regional responsiveness for just‑in‑time OEM supply.
-
Private equity and strategic investors: Target roll‑up opportunities in fragmented regional pockets where operational improvements and technology infusions can deliver outsized returns. Due diligence should stress test integration of IP (e.g., composite wheel patents) and post‑deal capex requirements.
-
Aftermarket and retail channels: Differentiate on customization, lifecycle services and verified sustainability credentials. Investments in digital configurators and certified remanufacturing will create stickier customer relationships.
-
Procurement and supply‑chain managers: Build hedging strategies for aluminum and energy exposure, and map second‑tier suppliers to reduce single‑source dependencies during program ramps and commodity shocks.
Final word — a staged approach to capture 2026 value
2026 is a pivotal planning year: the market’s mid‑single‑digit CAGR and the divergent technological pathways create both runway and complexity. Winning players will be those who combine selective capital allocation, tight OEM partnerships, and targeted technology investments — while using data‑driven scenario planning to avoid overcommitment in any single manufacturing pathway.
PW Consulting’s full Aluminum Alloy Wheels Market study furnishes the granular segmentation, supplier‑level economics and executable playbooks required to execute in 2026. For clients planning capital allocation, strategic partnerships or M&A activity this year, the report is structured to move quickly from insight to investment thesis.
Contact PW Consulting to access the full report, interactive model, and tailored advisory engagements that translate market growth into defensible, measurable outcomes.
For detailed analysis of this topic, please visit the official page: Aluminum Alloy Wheels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com