

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: LED Display Market to Reach USD 257.58M by 2032 at 5.41% CAGR

2026 Strategic Preview: LED Display Market — PW Consulting Industry Insights
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a forward-looking executive introduction to our comprehensive LED Display Market study. Grounded in a detailed baseline through 2025 and a robust forecast for 2026–2032, this analysis is built to inform board-level decisions, capital allocation, and commercial strategy for companies operating across the LED display value chain.
LED Display Market
Why this study matters for 2026 decisions
-
Clear, investable growth trajectory: The global LED display market has expanded from a modest base in 2020 and reached a meaningful scale by 2025. Our model projects steady expansion through the forecast horizon, with a compound annual growth rate of 5.41% from 2026 to 2032. This growth supports both organic commercial initiatives and inorganic playbooks for scale-seeking firms.
LED Display Market -
Structural shifts are redefining competitive advantage: Technological progress (mini- and microLED, dvLED, fine-pitch pixel density), service-led monetization (rental, managed services, SaaS content platforms), and new go-to-market configurations (direct enterprise channels, distributor partnerships, event rental ecosystems) are changing how value is captured.
LED Display Market -
Policy and trade shocks are non-trivial: Recent trade policy changes — including reciprocal tariff measures introduced in 2025 and adjustments to Section 232 tariffs in 2026 — have materially raised the cost calculus for cross-border supply chains and capital equipment. These developments increase the premium on supply-chain agility and scenario-based procurement planning.
Market scale and direction (what we modelled)
Our base-year consolidation for 2025 provides a market sizing foundation and a consistent historical series back to 2020. From that base, our forward-looking scenarios project steady expansion through 2032. For executives weighing near-term investments, the headline metrics — a market that has grown meaningfully over the 2020–2025 period and a mid-single-digit CAGR through 2032 — indicate a market large enough to support specialized innovation while remaining competitive.
We also include high-confidence scenario outputs reflecting alternative macroeconomic and policy paths (accelerated regionalization, trade normalization, or demand shocks tied to advertising and events sectors). These scenarios are designed to stress-test capex plans, pricing strategies, and M&A timing.
Competitive landscape — who matters and why
The market remains moderately concentrated: the leading three suppliers capture a meaningful share of market revenues, and the five largest firms account for a clear majority of industry turnover. This concentration creates a strategic environment where scale matters for price leadership, while differentiated technology or service models can unlock outsized margins.
-
Cree LED — Well positioned on high-intensity LEDs and RGB components, their recent product extensions emphasize higher color fidelity and compact packages suitable for dense pixel applications.
-
Neoti — Focused on dvLED solutions for broadcast, control rooms, and mission-critical installs; their expertise underscores the premium end of the indoor fine-pitch market.
-
Daktronics — A dominant name in large-format stadium, outdoor and billboard solutions; their systems competence supports integrated audiovisual projects and recurring maintenance contracts.
-
LG Electronics & Samsung Electronics — These conglomerate players are accelerating premium microLED and modular video wall offerings, bringing scale manufacturing, channel reach, and R&D intensity.
-
Leyard, Unilumin, Absen — Vendors primarily from manufacturing hubs in Asia who specialize in fine-pitch, rental, and commercial displays; their competitive advantage remains speed-to-market and price-performance ratios.
Recent industry developments underline product and market momentum: notable product launches from LED component and display manufacturers have continued into 2026, and certifications and market validations by third parties have altered perception and channel dynamics. These moves are discussed in the report with implications for product roadmaps, aftermarket service strategies, and competitive positioning.
Supply chain and cost dynamics — what boards must model
-
Componentization: LED modules, driver ICs, power management, and high-precision PCBs remain the critical cost anchors. Our bill-of-materials modeling traces how shifts in raw-material tariffs and semiconductor availability ripple into finished display pricing and margin profiles.
-
Tariff and trade risk: With reciprocal tariffs and modified metal tariffs affecting equipment imports introduced since 2025, companies need explicit scenario hedges — from localized assembly to duty engineering and multi-sourcing strategies. The report quantifies the sensitivity of margin to tariff increases and highlights tactical mitigations.
-
Service economics: Aftermarket service, parts replacement, and managed-display subscriptions materially improve lifetime value. We model how a service-led revenue mix changes cash flow profiles and valuation multiples for hardware-first incumbents.
Demand drivers and go-to-market plays
We identify and map the demand levers that will most influence vendor success between 2026 and 2032:
-
Commercial advertising and out-of-home transformation (digitalization of billboards and retail façades).
-
Entertainment, sports venues, and live events — where rental and temporary-install ecosystems are a growth vector.
-
Corporate, broadcast, and control-room installations — higher-margin professional applications with long replacement cycles and premium support requirements.
-
Emerging cases — virtual production, immersive experiences, and residential premium microLED adoption — which are strategic adjacencies with different product and distribution kinetics.
For each demand pocket, the report provides practical GTM frameworks: channel segmentation, pricing benchmarks, procurement playbooks for enterprise buyers, and cross-sell/upsell strategies for systems integrators.
Report deliverables — practical, actionable content
This study is crafted as an operational toolkit for executives and strategy teams. Highlights include:
-
Executive dashboard: rapid-read indicators of market direction, risk flags, and recommended actions for 90/180/360-day horizons.
-
Market sizing & forecast: historical series (2020–2025) and forward projections (2026–2032) with scenario variants and sensitivity testing.
-
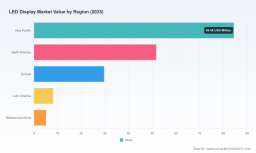
Segmentation frameworks: by region, product type, and application, with strategic implications for product roadmaps (note: detailed segmentation tables and raw breakdowns are available in the full report).
-
Vendor scorecards: qualitative and quantitative assessments of leading suppliers, centered on technology roadmaps, service capabilities, supply resilience, and channel coverage.
-
Supply-chain & BoM analytics: component-level cost modeling and tariff-sensitivity matrices to support procurement optimization and pricing decisions.
-
Go-to-market playbooks: tailored strategies for OEMs, system integrators, rental providers, and content platforms — including partnership archetypes and contract model recommendations.
-
M&A and investment thesis: target screening criteria, valuation considerations, and integration playbooks for buyers seeking scale or technology in-fills.
-
Regulatory impact analysis: direct implications of recent tariff policies and metal tariffs, and contingency plans for scenarios where trade frictions persist or intensify.
-
Appendices: methodology, data sources, and a repository of modeled assumptions (full numerical tables are reserved for report subscribers).
Strategic implications — five priority actions for 2026
-
Reprice with purpose: Revisit contractual pricing models to reflect increased input-cost volatility and differentiate on service rather than headline hardware pricing.
-
De-risk the supply chain: Execute a prioritized supplier-diversification roadmap and prepare localized assembly options for key markets to mitigate tariff exposure.
-
Monetize services: Pilot subscription and managed-service offerings in at least one high-value vertical to test improved lifetime-margin profiles.
-
Invest selectively in differentiation: Target micro/multiLED and control-system integration where the market rewards higher reliability and pixel density with margin premiums.
-
Prepare M&A playbooks: For buyers, develop a short-list of targets that provide either regional scale or product-technology in-fill; for sellers, build evidence of recurring revenue and service attach rates to maximize exit valuation.
How to use this study
Think of this report as a decision-support engine. Boards and executive teams can use it to stress-test capex plans, shape procurement RFPs, benchmark competitor positioning, and identify acquisition targets. Importantly, the report is structured to move from strategic implications down to operational execution — including templates and checklists for procurement, product development trade-offs, and channel segmentation.
To preserve the integrity of client-ready recommendations while providing an accessible preview, this introduction intentionally omits detailed segment-level tables and raw numeric breakdowns (those granular datasets and downloadable appendices are included in the full report). If your team requires the underlying modeling, BoM templates, or vendor scorecards to run internal valuation or procurement simulations, the full dataset and interactive scenario tool are available from PW Consulting.
Closing: what to prioritize now
2026 will be a year where the interplay between technology-led differentiation and policy-driven cost pressures determines winners and losers. Firms that combine supply-chain resilience with service-led monetization and targeted technology investment will expand margins and market share even in a mid-single-digit growth environment. Our full PW Consulting LED Display Market study equips decision-makers with the quantitative foundations, scenario playbooks, and tactical templates needed to act with confidence.
For access to the full report, data workbooks, and a tailored briefing for your executive team, please contact PW Consulting. Our analysts stand ready to align the report’s outputs with your organization’s strategic priorities and operational timelines.
For detailed analysis of this topic, please visit the official page: LED Display Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com