

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
5-HMF market to reach USD 80M by 2032 at 3.8% CAGR — PW Consulting

5-Hydroxymethylfurfural (5-HMF) Market — Strategic Outlook for 2026 Decision-Makers
Executive summary
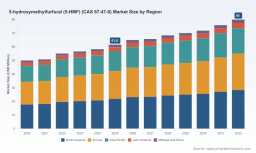
As companies prepare strategic plans for 2026, understanding the trajectory of the 5-hydroxymethylfurfural (5-HMF, CAS 67-47-0) market is a practical necessity. PW Consulting’s latest study synthesizes primary interviews, supply‑side audits and proprietary demand-modeling to produce a clear, actionable view of market direction without exposing the granular segmentation that often clouds commercial judgement. At a macro level, the market expands from an estimated USD 61.6 Million in 2025 to roughly USD 80.0 Million by 2032, reflecting a compound annual growth rate (CAGR) of approximately 3.8% for the 2026–2032 forecast window. This measured but persistent growth presents discrete opportunities for upstream producers, specialty distributors and downstream formulators — provided companies translate top‑line visibility into operational and go‑to‑market choices.
5-hydroxymethylfurfural (5-HMF) (CAS 67-47-0) Market
Why this research matters for 2026 strategic decisions
-
Timing investment in capacity and differentiation: With near‑to‑mid term growth that is steady rather than explosive, capital allocation decisions require nuanced timing. Overinvesting in undifferentiated capacity is a common mistake; conversely, targeted expansion tied to specialty grades or certification can capture disproportionate margin.
5-hydroxymethylfurfural (5-HMF) (CAS 67-47-0) Market -
Mitigating feedstock volatility: The study connects HMF pricing and feedstock dynamics to real procurement levers. Our analysis shows that Q4 2025 experienced price stabilization due to a balance between glucose availability and moderate food demand — insight that matters when negotiating multi‑year supply agreements or designing hedging strategies.
5-hydroxymethylfurfural (5-HMF) (CAS 67-47-0) Market -
Navigating regulatory friction: The regulatory environment is a background force shaping trade and certification decisions. As of late 2025, official guidance (e.g., U.S. Customs updates) does not explicitly place 5‑HMF on reciprocal tariff lists — a positive short‑term signal for cross‑border flows — but evolving chemical safety and labeling regimes remain a watchpoint for exporters and formulators.
Market trajectory and what the headline numbers mean
The market’s progression from the historical period through the base year (2025) establishes a stable foundation: gradual cumulative gains driven by incremental end‑market adoption and improved supply reliability. The forecasted climb to approximately USD 80.0 Million by 2032 at a 3.8% CAGR reflects continued but selective uptake across multiple industrial applications. For executives, the headline numbers should be read as a strategic envelope: there is predictable aggregate demand, but growth pockets will be driven by quality, certification, and integrated supply propositions rather than by commoditization alone.
Competitive landscape — where strategic advantage resides
The 5‑HMF supply base is characterized by a mix of specialized bio‑producers, chemical fine‑suppliers, and research-grade vendors. Market concentration is meaningful: the three largest players control roughly two‑thirds of global supply capacity, and the top five capture roughly three‑quarters of the market. That structure shapes both pricing power dynamics and partnership options.
-
Bio‑based, scale‑oriented producers — Companies investing in hydrothermal and sugar‑feedstock routes (e.g., specialized bio‑manufacturers) are positioned to lead on sustainability claims and large‑volume, consistent supply. This model favors those able to demonstrate feedstock traceability and process reproducibility.
-
Specialty fine‑chemical vendors — Established fine chemical houses with deep customer relationships and custom synthesis capabilities maintain relevance through high‑purity grades, regulatory documentation (including halal/kosher where applicable), and rapid custom‑order responsiveness.
-
Regional manufacturers and exporters — Several Asia‑based manufacturers serve bulk industrial demand and offer competitive lead times for regional formulators. Their strategic value is often transactional cost advantage plus proximity to local intermediates supply chains.
Across these archetypes, strategic differentiation clusters around three vectors: feedstock origin and sustainability credentials, grade/certification breadth, and integrated service (technical support, custom synthesis, logistics). In practice, the fastest path to margin expansion is combining a visible sustainability story with dependable high‑purity product lines and documented regulatory support.
Profiles that matter — tactical takeaways from key players
-
High‑purity bio‑producers — Firms specializing in renewable sugar feedstock conversion and hydrothermal processes have an edge in sustainability‑focused accounts and industrial partnerships seeking bio‑based platform chemicals. Their strategic priority should be securing forward feedstock contracts and accelerating certification pathways to command price premiums.
-
Specialty suppliers with custom capabilities — Suppliers offering custom synthesis and research to scale handholds facilitate co‑development with fragrance, pharma and R&D customers. These players should lock in collaborative development agreements and protect IP around niche derivatives of 5‑HMF.
-
Global distributors and research suppliers — Firms that combine catalog supply with validated documentation and certifications serve as critical access points for small‑batch and research markets. For these companies, expanding logistics footprints and traceable documentation is a low‑friction route to defend revenue.
Market dynamics and supply‑chain signals to watch
Short‑term dynamics are dominated by feedstock cycles and demand seasonality. The Q4 2025 window illustrated how balanced glucose supply and moderate food demand led to price stability for HMF — a useful leading indicator for purchasing teams planning 2026 procurement. Regulatory signals remain benign but not static: absence from recent reciprocal tariff lists reduces immediate trade risk, yet evolving chemical safety assessments, labeling and sustainability reporting obligations could reframe sourcing rationales over the medium term.
What the report contains — practical, operational deliverables
PW Consulting’s full study is designed to be directly actionable for commercial, procurement and R&D leaders. Highlights include:
-
Demand model with scenario analysis (base, upside, downside), including sensitivity to feedstock price and adoption curves across relevant end markets.
-
Detailed supply‑chain maps and critical node risk assessments, identifying logistics chokepoints, single‑source exposures and mitigation levers.
-
Competitive benchmarking and supplier dossiers that score firms on capacity, purity grades, certification, customization ability and go‑to‑market reach.
-
Commercial playbooks for upstream producers (pricing strategy, contracting templates), distributors (inventory and service models) and end users (specification management, substitution pathways).
-
Regulatory & trade matrix with recommended compliance actions and potential cost impacts under alternate regulatory scenarios.
-
Primary interview excerpts and validated market intel gathered from producers, distributors and formulators — giving leaders a real‑world read on intent and capacity.
Strategic implications and recommended moves for 2026
-
Prioritize differentiated capacity over volume . Given the market’s measured CAGR and the concentration of supply, investments that enable higher‑value grades (e.g., certified food/research grades, traceable bio‑origin) yield stronger returns than undifferentiated scale‑outs.
-
Embed feedstock resilience into contracts . Procurement should structure agreements that link feedstock sourcing with price collars and volume flex — a tactical response to predictable short‑term stabilization punctuated by occasional feedstock shocks.
-
Exploit certification as a market access tool . Certifications (quality, religious, sustainability) materially expand addressable customers with limited incremental capital if built into product lines early.
-
Use competitive concentration to negotiate strategic partnerships . The current concentration profile favors joint ventures, tolling arrangements and co‑development pacts that secure priority access to volumes and R&D resources without heavy upfront capital.
-
Monitor regulatory inflection points . Even though 5‑HMF was not listed among reciprocal tariff items through late 2025, regulatory attention to chemical safety and sustainability disclosures can rapidly change supply economics and market access.
Why executives should read the full PW Consulting study
This article is deliberately a “trailer”: it conveys our methodological rigor, market context and strategic takeaways while withholding the granular segmentation slices and company‑level revenue estimates that underpin deal‑level decisions. The full report contains the proprietary splits, primary‑data tables and supplier scoring matrices that procurement teams, M&A advisors and product-line leaders need to finalize 2026 strategies. If your leadership team is deciding between brown‑field expansion, strategic partnerships or premium grade development, the full dataset will materially shorten decision cycles and reduce strategic execution risk.
Next steps
For access to the primary datasets, supplier dossiers and the operational playbooks referenced here, visit the PW Consulting report page or contact our analyst team for a briefing. We will walk through how the forecast envelope and scenario outputs translate into specific capital and commercial actions tailored to your role — whether you lead procurement, manufacturing or corporate strategy.
For detailed analysis of this topic, please visit the official page: 5-hydroxymethylfurfural (5-HMF) (CAS 67-47-0) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com